


 Discount


Today’s Market Recap: Hawkish Fed Minutes Warn of AI Debt Risk as Anthropic Deal Total Hits $90 Billion, Surpassing SpaceX



AI Podcast


US stocks mixed as tech strength countered AI infrastructure weakness and a 1.11% drop in the Dow. Fed October meeting minutes signaled potential further rate hikes, while warning of risks from opaque AI debt financing. Industrial metals experienced a sharp sell-off, driven by rate hike expectations and a stronger dollar, dragging down European miners. In corporate developments, Anthropic completed a record-breaking $90 billion offering, Nvidia addressed leadership transition concerns, Microsoft and Intel partnered on cloud and AI infrastructure, and Apple negotiated a long-term DRAM contract with Samsung. Crude oil prices diverged, spot gold and silver rose, and cryptocurrencies declined broadly.

Tracking Market Trends
TradingKey - The three major US stock indexes were mixed, with the Dow Jones Industrial Average (DJIA) falling 1.11% to 50,198.17; the S&P 500 Index (SPX) falling 0.23% to 7,323.63; and the Nasdaq Composite Index (IXIC) rising 0.42% to 24,429.88.
Advanced Micro Devices (AMD) rose 5.31%, Broadcom (AVGO) rose 3.65%, and Astera Labs (ALAB) gained 2.43%. Despite moderate strength in tech stocks, AI infrastructure providers remained under pressure.
CoreWeave (CRWV) fell more than 4% to close at $47.83; CoreWeave peer IREN (IREN) dropped 3.61% to $15.24, while Nvidia (NVDA) rose as much as 2.7% early in the session before closing down 2.89%.
International crude oil prices continued to diverge. WTI crude (USOIL) rose 0.18% to $81.80 per barrel; Brent crude (UKOIL) fell 1.61% to $89.69 per barrel. Spot gold (XAUUSD) gained 0.78% to $3,753.61 per ounce; spot silver (XAGUSD) rose 1.5% to $45.72 per ounce.
Cryptocurrencies were broadly lower. Bitcoin (BTC) fell 2.29% to $63,184; Ethereum (ETH) fell 1.8% to trade at $1,784; Ripple (XRP) slipped 1.1% to trade at $0.96; Binance Coin (BNB) fell 1.95% to $584.
Market News
On November 18, Xi Jinping delivered a speech at the APEC CEO Summit in Shenzhen, emphasizing the safeguarding of peace and stability, confronting the defining challenges of our time between openness and closure as well as cooperation and division, and announcing tariff cuts, the full implementation of both access and operational rights in manufacturing, and the expanded opening of the services sector. Later that afternoon, Trump arrived in Shenzhen, and Xi greeted him at Bao'an Airport.
Minutes from the Federal Reserve's October meeting released early on November 19 showed that nearly all officials believed further rate hikes could be appropriate based on inflation and employment projections; two officials even noted that if inflation worsened, a rate hike of more than 25 basis points might be considered at the next meeting. The October meeting voted 10 to 2 to keep interest rates unchanged. The minutes also warned that a surge in opaque debt financing for AI could amplify losses if returns fall short of expectations.
The metals market suffered a sell-off on November 18, with LME three-month copper falling 5.7% to $12,471 per ton, hitting its lowest level since early April. LME zinc and tin fell around 5%, while aluminum and nickel dropped nearly 4%; COMEX November copper futures once sank nearly 6% intraday. Rate hike expectations, concerns over AI infrastructure, a stronger US dollar, and technical selling exacerbated the slide, dragging European mining stocks down 4.7%, with Glencore sliding 6.12% and Anglo American tumbling 7.18%.
Anthropic attracted roughly $400 billion in institutional subscriptions and nearly $100 billion in retail subscriptions, closing its order book on Tuesday. The offering price was raised to $83 per share alongside an upsized offering. Combined with a concurrent $26 billion private placement, the total deal size exceeded $90 billion, surpassing SpaceX's IPO this year, which initially raised $75 billion and expanded to $86.2 billion following the exercise of the over-allotment option.
Nvidia interim CEO Colette Kress pledged at the first all-hands meeting following Jensen Huang's departure that salary increases and equity incentives would be brought forward to December to prevent talent attrition. Employees raised concerns regarding compensation and board transparency; the chairman confirmed that an external executive search firm is seeking a new CEO and that Huang will not return. Some senior employees warned that a mishandled transition could risk losing core engineering talent.
On November 18, Microsoft and Intel signed a long-term agreement to advance Azure cloud and AI infrastructure. Intel secured a multi-year supply of Xeon processors (including the next-generation Diamond Rapids) and will provide EMIB-T foundry packaging for Microsoft's proprietary chips, such as the next-generation Maia accelerator and Cobalt CPU. Microsoft stated that Azure M-series v4 virtual machines leverage CXL and Xeon 6 to boost performance by up to 2.3 times, while speeding up SQL backups by up to 2.5 times.
According to South Korea's Maeil Business Newspaper, Apple plans to sign a four-to-five-year long-term DRAM contract with Samsung, with deliveries slated to begin in the first half of 2027. The terms set a minimum supply commitment, with pricing pegged to market prices rather than fixed rates. Apple is currently one of the few tech giants that have yet to sign a long-term DRAM contract with Samsung.
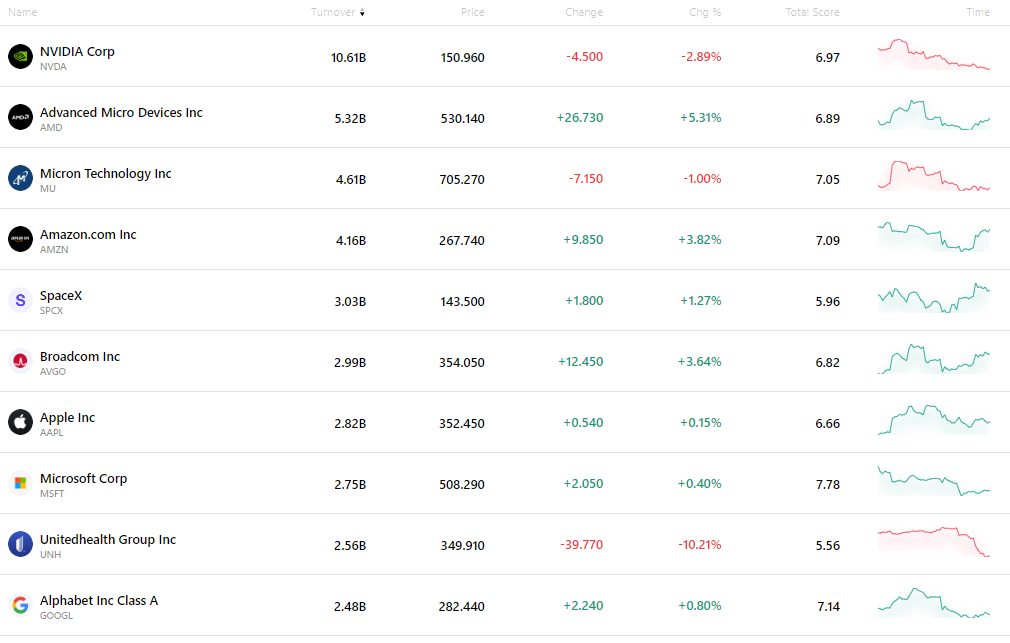
Top 10 Most Active Stocks
The table below lists the ten most actively traded stocks in the latest market. Supported by massive trading volume and exceptional liquidity, these assets have become key benchmarks for tracking global market dynamics.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.