


Nvidia Rival Cerebras Jumps Over 19% in Overnight Trading as Microsoft Reportedly Becomes New Customer, Raises Full-Year Revenue Guidance Cap to $960 Million



AI Podcast


On November 12, Eastern Time, Cerebras Systems shares rose approximately 19% in after-hours trading following strong third-quarter 2026 financial results. Core revenue grew 70% year-over-year to $230.9 million, driven by a 272% surge in cloud computing services. The company raised its full-year Core revenue guidance to $940 million–$960 million and secured a major cloud partnership with Microsoft. Despite a widened GAAP net loss of $161.2 million from rising expenses, management projects improved margins ahead. Key risks include heavy reliance on major clients, high infrastructure costs, and the challenge of converting extensive remaining performance obligations into actual revenue.
TradingKey - On November 12, Eastern Time, AI chip company Cerebras Systems (CBRS) saw its shares rise as much as about 19% in after-hours trading after releasing its third-quarter 2026 financial results. As of press time, Cerebras traded at $116.9 in overnight trading, up about 19.51%.
The company's third-quarter Core revenue grew 70% year-over-year, and it raised its full-year revenue guidance. In addition, the company added one of the world's top three hyperscale cloud service providers as a new customer, reportedly Microsoft (MSFT), with the two parties entering into a cloud computing partnership.
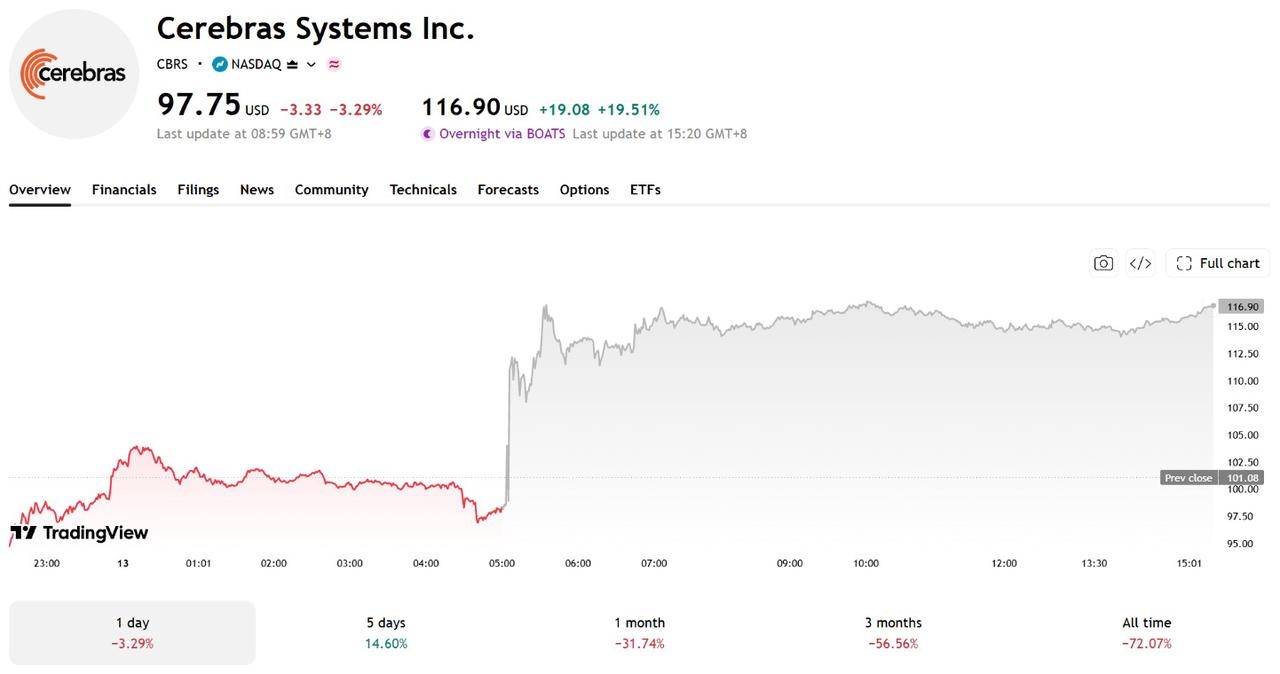
[Source: TradingView]
Cerebras Raises Full-Year Revenue Forecast as Cloud Computing Revenue Jumps 272%
Cerebras expects full-year 2026 Core revenue to reach $940 million to $960 million, higher than its prior forecast of $880 million to $890 million and topping analyst expectations of approximately $887.5 million.
In the third quarter, the company's GAAP revenue was $210.8 million, up 55% year-over-year, while Core revenue was $230.9 million, up 70% year-over-year and exceeding analyst expectations of $214.7 million.
By segment, Core cloud computing and other services revenue reached $144.9 million, up 272% year-over-year, while Core hardware revenue declined to $86 million from $96.8 million in the prior-year period, indicating that cloud services have become the primary growth driver.
On profitability, the third-quarter GAAP net loss widened to $161.2 million from $22.2 million in the prior-year period, mainly affected by growth in expenses such as R&D. However, the Core operating margin was negative 14%, and the company expects it to improve to between negative 1% and positive 1% in the fourth quarter.
Looking ahead to the fourth quarter, Cerebras expects Core revenue of $310 million to $330 million, above analyst expectations of $274.9 million, while Core gross margin is projected to rise to 47% to 49%, up from 41% in the third quarter.
Cerebras Accelerates Cloud Market Expansion as Microsoft Reportedly Becomes New Customer
Cerebras announced in its earnings report that it has partnered with one of the world's top three hyperscale cloud service providers, but did not disclose the customer's name or contract value. Both The Wall Street Journal and Reuters confirmed that the customer is Microsoft. The company expects to announce more details about the partnership in 2027.
Previously, Cerebras partnered with Oracle (ORCL) to integrate its AI inference technology into Oracle Cloud Infrastructure (OCI), with related services scheduled to launch in 2027.
On the technology front, Cerebras utilizes a Wafer Scale Engine (WSE) architecture, primarily targeting AI training and inference to differentiate itself from Nvidia GPUs. On the supply chain front, the company's CEO stated that it has secured from TSMC (TSM) sufficient wafer supply commitments, which will help support subsequent capacity expansion.
As of September 30, 2026, Cerebras's remaining performance obligations (RPO) reached $26.1 billion, primarily tied to agreements with OpenAI. In addition, the company has contracted 700 megawatts of data center capacity scheduled for delivery by the end of 2027, though this does not yet represent operational computing power.
However, translating partnerships into actual revenue still depends on data center deployment, customer procurement, and service usage, and the company must also bear corresponding infrastructure buildout and operating costs.
In the short term, whether fourth-quarter performance meets company guidance will affect the market's assessment of its growth prospects. Over the long term, whether cloud computing revenue can sustain growth, hardware sales can rebound, and reliance on major customers and infrastructure costs can be controlled will determine the pace of its profitability improvement.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.