


Super Micro Computer Q1 Earnings Preview: Revenue Outlook Nearly 27% Above Original Guidance Midpoint, Highest Wall Street Target at $57



AI Podcast


Super Micro Computer will report its fiscal Q1 2027 results on November 3 Eastern Time. The company previously raised its revenue guidance to $18.5 billion–$19.5 billion and gross margin to 12.0%–12.5%, driven by surging AI platform demand. However, gross margins are expected to decline sequentially from Q4 2026. Key metrics to monitor include actual profitability, cash flow, inventory levels, and customer collections. Wall Street analysts remain divided, with an average price target of $40.58. Investors should focus on whether revenue growth successfully translates into improved profits and sustainable forward guidance.

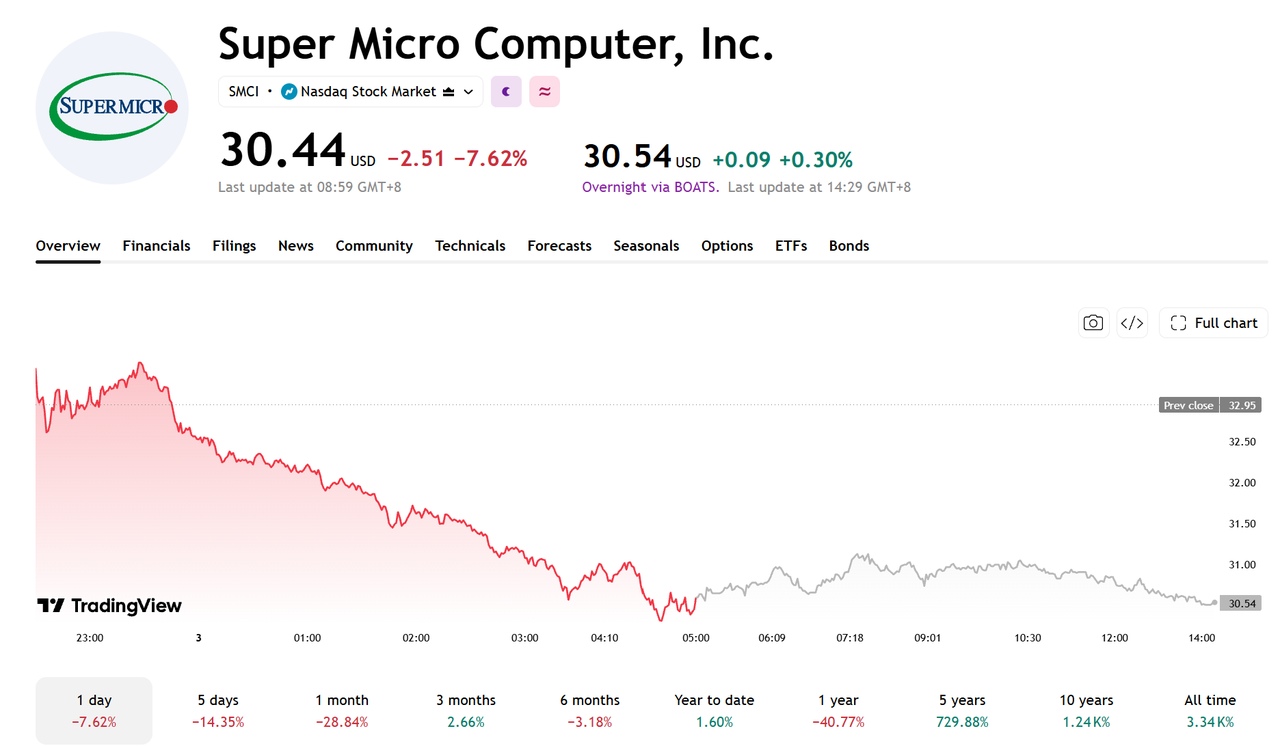
TradingKey - Super Micro Computer (SMCI) will report its first-quarter fiscal 2027 results after the market close on November 3 Eastern Time, and host a conference call at 17:00 that day. As of press time, Super Micro Computer was up 0.3% in overnight trading at $30.54.
[Source: TradingView]
The company has previously raised its revenue and gross margin guidance, and the market will focus on whether actual results can meet expectations, as well as its profit and cash flow performance.
On October 20, Super Micro Computer projected its first fiscal quarter revenue to be $18.5 billion to $19.5 billion, higher than the previous guidance of $14.5 billion to $15.5 billion. Based on the midpoint of the range, revenue guidance was raised by 26.7%, primarily driven by growth in demand for AI platforms.
The company also raised its gross margin estimate from 10.4%–10.8% to 12.0%–12.5%, primarily influenced by changes in customer and product mix.
Previous Quarter Review: Gross Margin Expected to Decline QoQ This Quarter
In the fourth quarter of fiscal 2026, Super Micro Computer recorded revenue of approximately $11.1 billion, with a GAAP gross margin of 17.5%. In comparison, the company expects its gross margin for the current fiscal quarter to be 12.0%–12.5%, down 5 to 5.5 percentage points from the previous quarter.
This indicates that despite raising its gross margin guidance for the current fiscal quarter, the company is still not expected to maintain the high margin levels of the previous quarter. Investors need to monitor the impact of shifts in customer and product mix on margins, as well as whether the gross margin can remain within the updated guidance range.
Key Metrics: Gross Margin, Cash Flow and Subsequent Deliveries
This earnings report requires close attention to actual revenue and gross margin performance, as well as whether gross margin expansion can drive growth in operating profit and earnings per share.
On the cash flow front, the key focus will be on inventory, accounts receivable, and operating cash flow. In the previous fiscal quarter, the company's inventory reached $12.9 billion, and its cash conversion cycle lengthened to 149 days, making inventory turnover and customer collections worth watching.
In addition, management's outlook for next-quarter demand, order backlog, and delivery progress will also influence market expectations. The company previously raised its revenue guidance due to growing demand for AI platforms; whether subsequent orders can be delivered as scheduled will serve as a key basis for evaluating the sustainability of revenue growth.
Wall Street’s Highest Price Target Sees $57
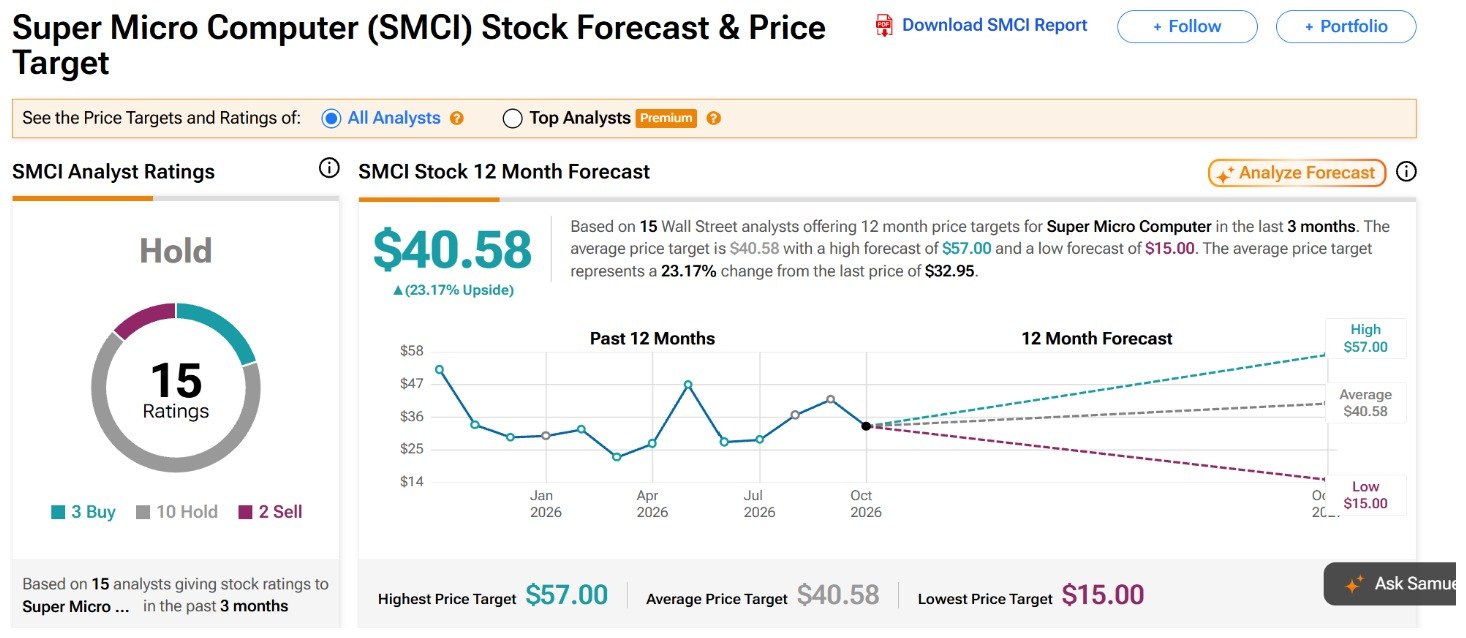
As of November 3, according to TipRanks data, the average analyst price target for SMCI is approximately $40.58, implying a 23.17% upside from current estimates, with a high target of $57.
[Source: TipRanks]
Among 15 analysts, 3 give a "Buy" rating, 10 give a "Hold" rating, and 2 give a "Sell" rating.
Specifically, Rosenblatt raised its price target from $51 to $57 on October 21 while maintaining a "Buy" rating, primarily bullish on AI server order growth and corporate governance improvements.
Needham maintained its $46 price target and "Buy" rating, while Bernstein maintained its $42 price target and "Hold" rating. Although BofA Securities raised its price target from $33 to $38, it maintained a "Sell" rating. Analysts' divergence mainly centers on whether AI server growth is sustainable and whether the company's profitability and governance can improve.
The key to SMCI's upcoming earnings report lies in whether revenue growth can translate into improved profits and cash flow. If the gross margin or forward guidance falls short of expectations, the stock price may come under pressure even if revenue grows significantly.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles












Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.