


Palantir Q3 Earnings Preview: Revenue Expected to Grow 84% Above High End of Company Guidance, Highest Wall Street Target Reaches $265



AI Podcast


Palantir is scheduled to report its third-quarter fiscal 2026 financial results after the U.S. market close on November 2, trading at a high trailing P/E ratio of approximately 157x. Market consensus anticipates revenue of $2.17 billion to $2.18 billion, slightly above company guidance, with adjusted EPS projected at $0.41. Key investor focuses include U.S. commercial growth, international expansion, contract conversion, and fourth-quarter guidance. While major institutions maintain a "Moderate Buy" rating with price targets up to $265 driven by AI demand, bearish analysts warn of valuation risks and intensifying competition that could pressure the stock.

TradingKey - Palantir (PLTR) will report its third-quarter fiscal 2026 financial results after the U.S. market close on November 2 and hold an earnings conference call at 17:00 ET on the same day.
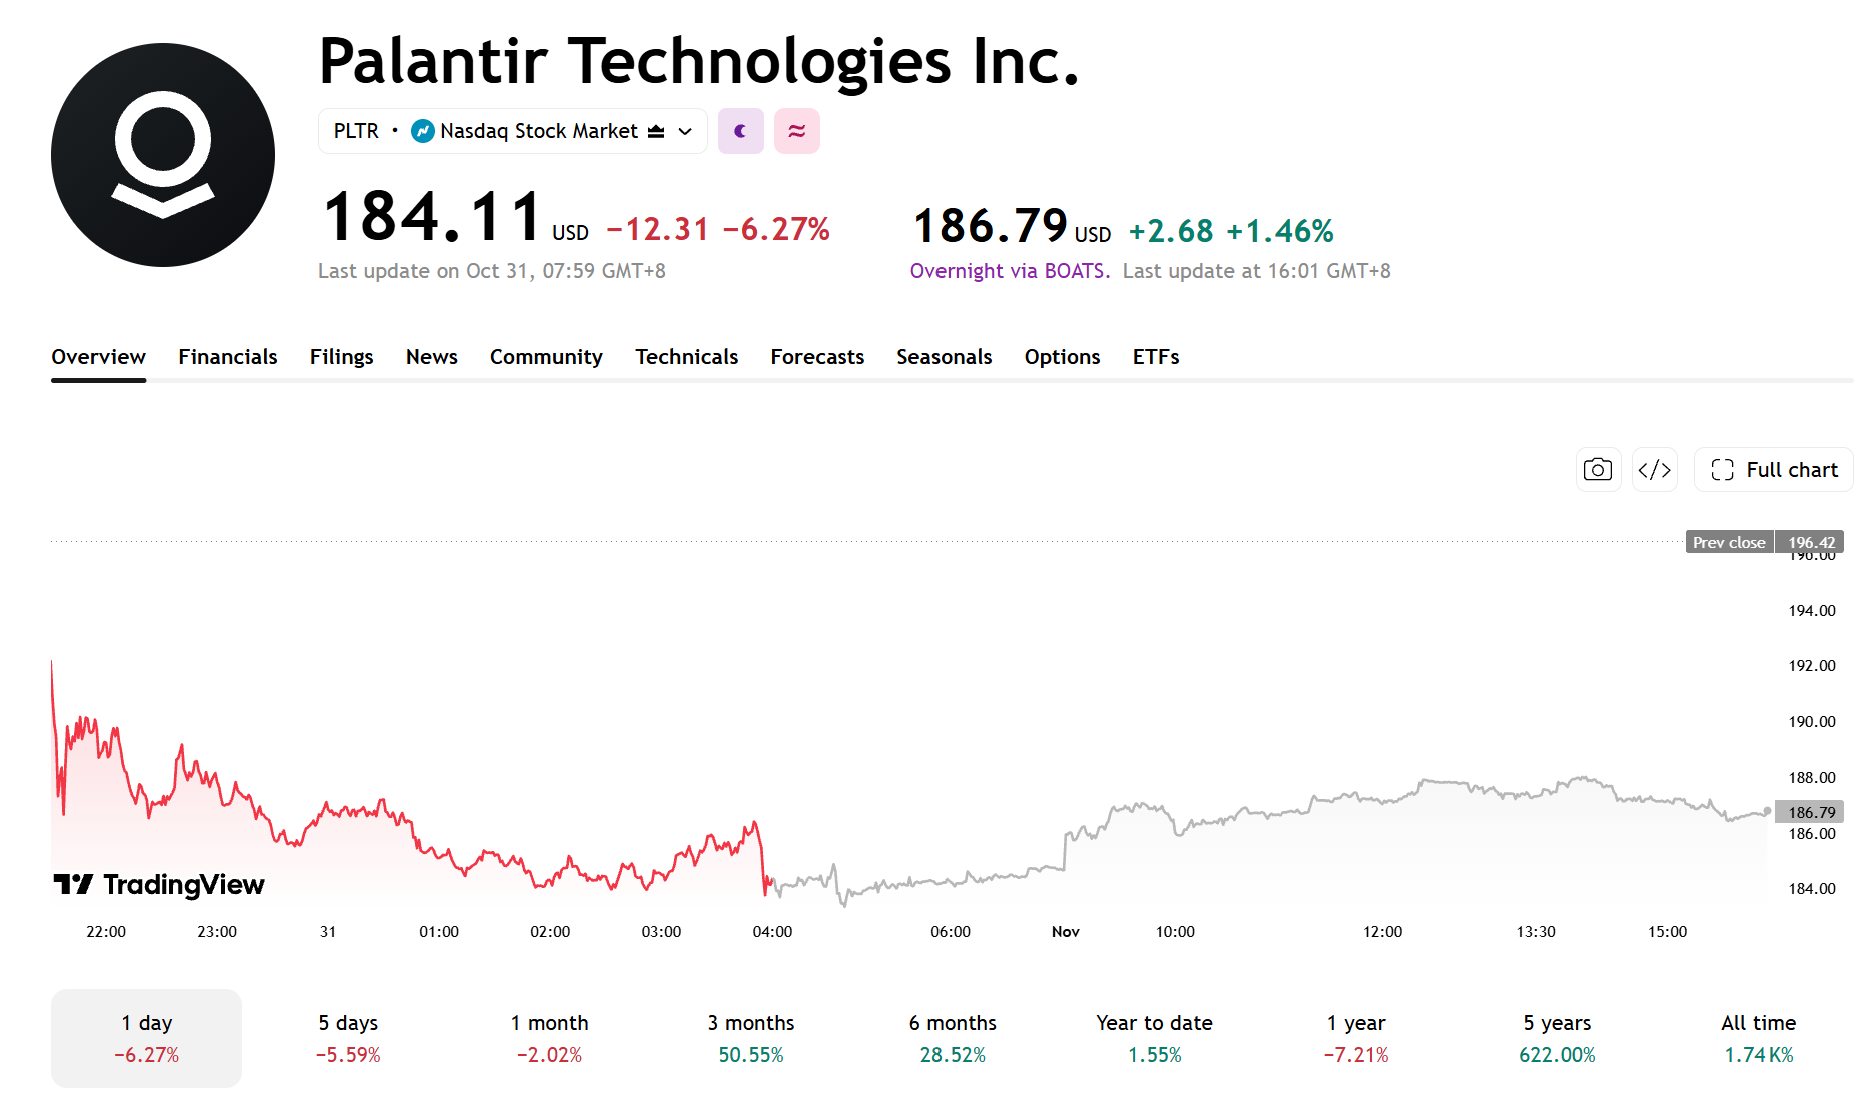
As of press time on November 2, Palantir's pre-market share price stood at $186.79, up 1.46%, with a market capitalization of approximately $447 billion and a trailing P/E ratio of about 157x, placing its valuation at a relatively high level.
[TradingView]
Market Expectations Slightly Above Company Guidance
The market expects Palantir's third-quarter revenue to be approximately $2.17 billion to $2.18 billion, up about 84% year-over-year; adjusted earnings per share are expected to be $0.41, up from $0.21 in the prior-year period.
The company previously provided revenue guidance of $2.160 billion to $2.164 billion and adjusted operating income guidance of $1.292 billion to $1.296 billion; market revenue expectations are slightly above the upper end of the company's guidance.
Therefore, the key focus following the earnings report is not only whether actual revenue meets expectations, but also fourth-quarter guidance, adjusted margins, and whether full-year targets are raised further.
The company had previously raised its full-year 2026 revenue guidance to $8.150 billion to $8.158 billion and projected U.S. commercial revenue to reach at least $3.424 billion, up at least 134% year-over-year. Whether management further raises these two metrics will be a key focus of this earnings report.
Q2 Earnings Review: US Commercial Revenue Grows 149%
In the second quarter, Palantir reported revenue of $1.935 billion, up 93% year-over-year. US revenue rose 115% to $1.573 billion, with US commercial revenue and government revenue growing 149% and 90% to $764 million and $809 million, respectively.
The company closed 220 deals worth at least $1 million during the quarter, with Total Contract Value (TCV) reaching $3.373 billion, up 49% year-over-year; US commercial TCV surged 153% to $2.132 billion. US commercial Remaining Deal Value (RDV) stood at $6.238 billion, up 124% year-over-year.
In terms of profitability, adjusted free cash flow was $1.220 billion, representing a margin of 63%, while the adjusted operating margin came in at 62%.
Key Metrics: Order Fulfillment, International Business and Profit Margins
In the third quarter, the market will focus on the growth of U.S. commercial business and contract execution. As the comparison base rises, revenue growth may slow down, and metrics such as customer count, contract size, and actual revenue will be key indicators for assessing business demand.
International commercial revenue growth is significantly lower than that of the U.S. market, and whether overseas customer expansion and business deployment can accelerate will also affect the company's overall growth.
Since the company does not separately disclose AIP revenue, its commercialization progress must still be evaluated indirectly through customer growth, contract size, and business deployment.
On profitability, the market will focus on whether the adjusted operating margin can reach the level of approximately 60% implied by the company's guidance.
Institutional View: Highest Price Target Seen at $265
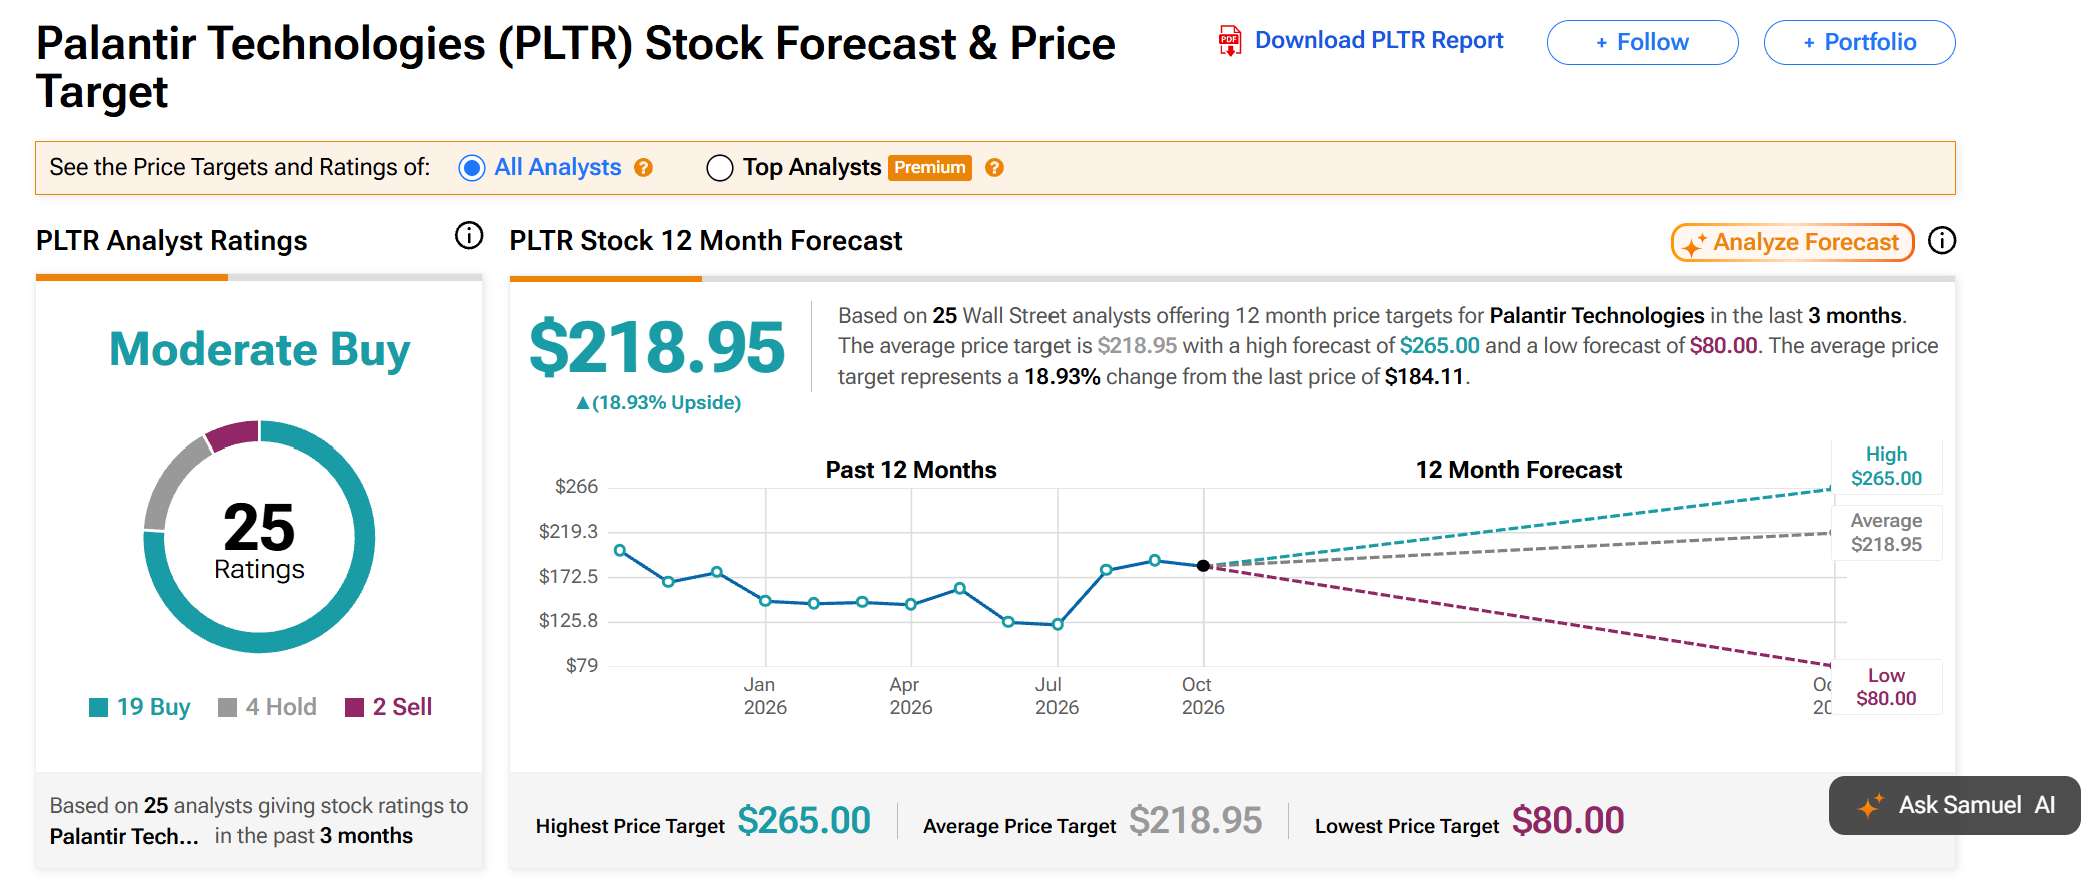
As of November 2, according to TipRanks data, Palantir has received a "Moderate Buy" rating, with an average analyst price target of $218.95, implying an 18.93% upside from its October 30 closing price.
[Source: TipRanks]
Goldman Sachs upgraded its rating from "Neutral" to "Buy" with a price target of $230, citing optimism about growing demand for sovereign AI and enterprise AI applications. Barclays assigned an "Overweight" rating with a price target of $265, primarily bullish on the defense tech sector's prospects and Palantir's competitive advantages. Rosenblatt raised its price target from $225 to $260, believing expanding enterprise AI adoption will drive customer growth.
RBC Capital, however, maintained an "Underperform" rating with a price target of $90, primarily citing concerns over Palantir's elevated valuation, insufficient sustainability in commercial business growth, and intensifying AI competition.
Looking ahead to the earnings report, if revenue, U.S. commercial growth, or future guidance fall short of expectations, the stock price may come under pressure. Given the company's high valuation, whether contract orders can consistently be converted into revenue and cash flow will be a key factor influencing stock performance.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.