


Amazon Slumps 7% Pre-Market: Surging AI CapEx, Negative Free Cash Flow Spark Concerns



AI Podcast


As of press time on October 30 ET, Amazon fell 7.1% in pre-market trading to $226.48 following its third-quarter 2026 earnings report. Revenue and EPS missed expectations, and fourth-quarter guidance lagged analyst estimates. While AWS revenue surged 39.3% year-over-year to $46 billion, massive AI infrastructure investments projected to reach $220 billion in 2026 pushed trailing 12-month free cash flow into a net outflow of $42.4 billion. This surge in capital expenditures significantly outpaced operating cash flow growth, sparking heightened market concerns regarding return on investment and future capital requirements.

TradingKey - As of press time on October 30 ET, Amazon (AMZN) fell 7.1% in pre-market trading to $226.48. The company's third-quarter 2026 earnings report showed that revenue and EPS were slightly below market expectations, while the midpoint of its fourth-quarter revenue guidance was also lower than analyst estimates.
Although AWS revenue maintained rapid growth, the continuous expansion of AI infrastructure investment turned free cash flow over the past 12 months into a net outflow, sparking market concerns over return on investment.
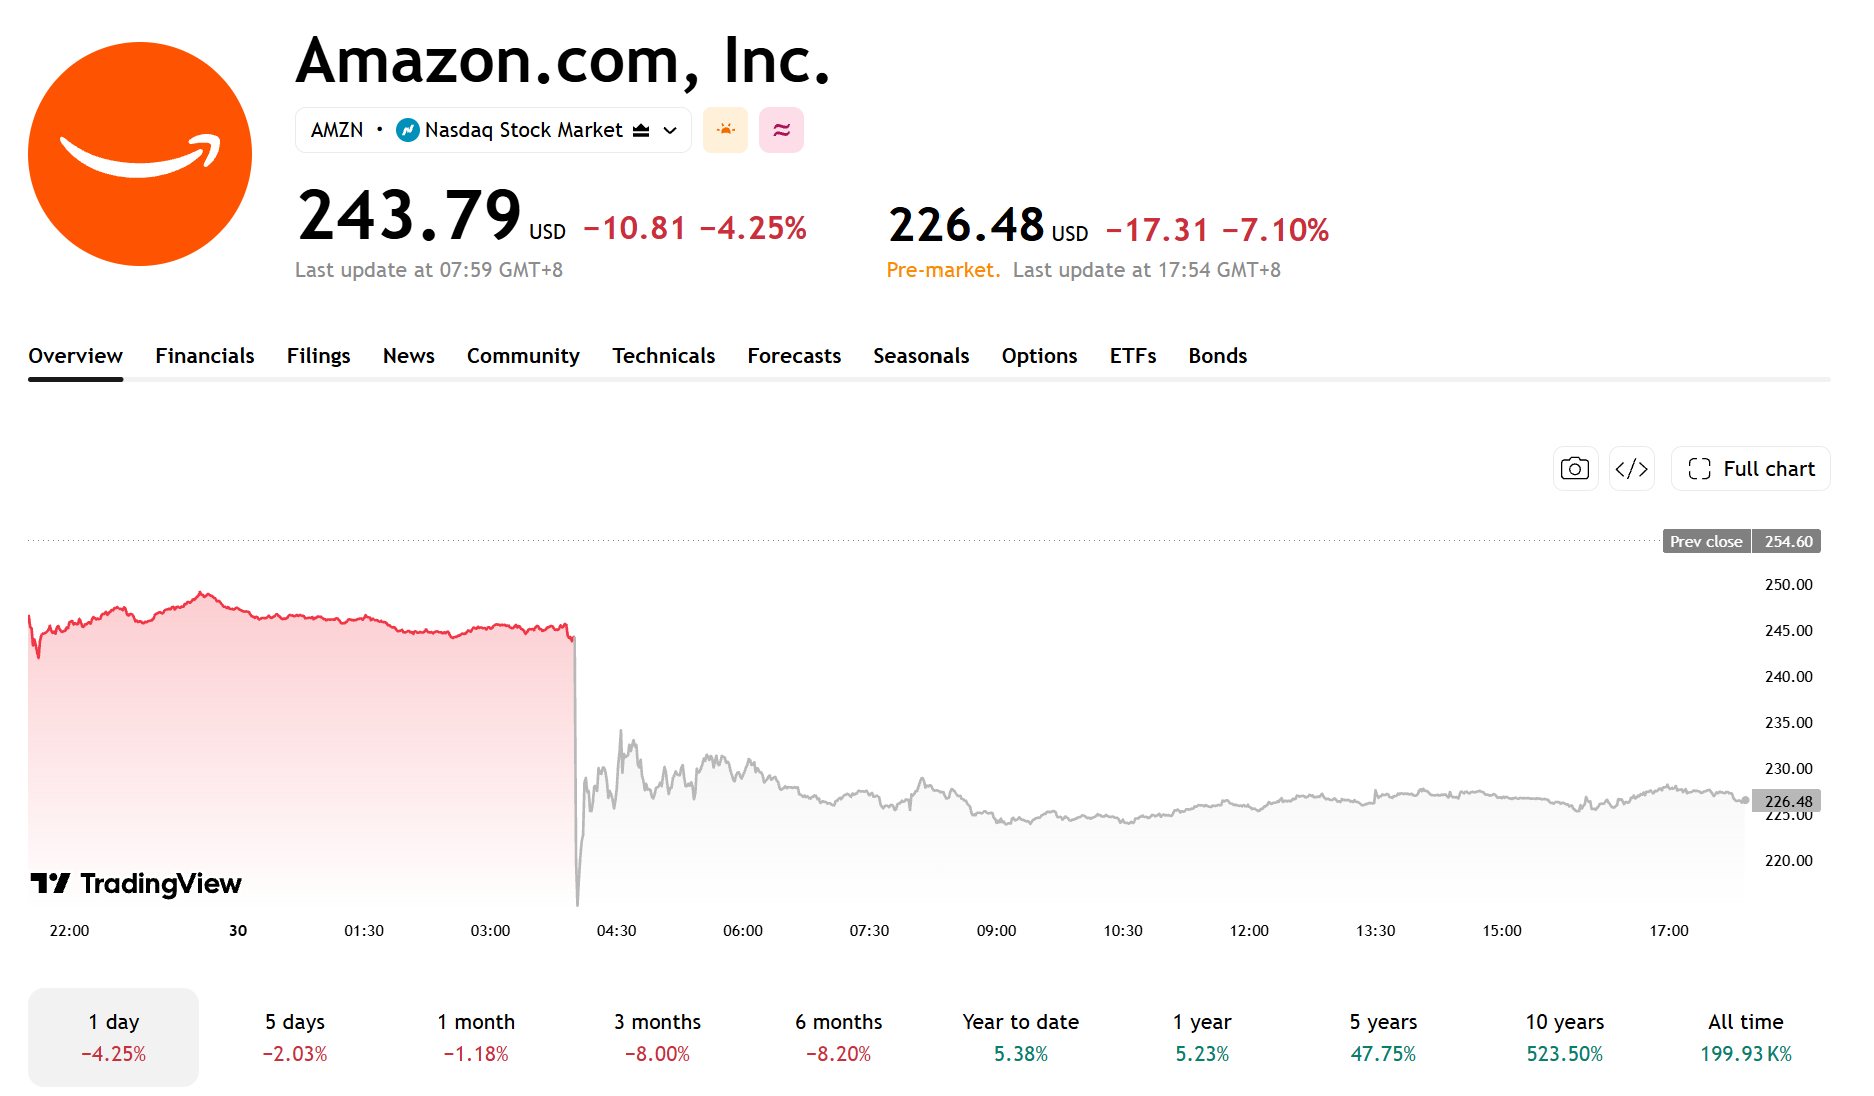
[Source: TradingView]
Q3 Revenue and EPS Slightly Below Expectations, Q4 Guidance Weak
Amazon's third-quarter net sales grew 12% year-over-year to $201.9 billion, slightly below market expectations of $202.2 billion; diluted earnings per share were $1.89, also coming in below analysts' expectations of $1.97.
In terms of profitability, the company's operating income increased by approximately 61% year-over-year to $28.1 billion, with the operating margin rising to a record high of 13.9%.
Growth in the advertising business slowed down. Third-quarter advertising revenue grew 12% year-over-year to $19.6 billion, or 12% excluding the impact of foreign exchange rates.
Amazon stated that factors such as the timing shift of Prime Day affected its advertising revenue performance. Prime Day 2026 was scheduled in the second quarter across most major markets, whereas in 2025 it fell entirely in the third quarter. Excluding this timing difference, third-quarter year-over-year revenue growth would have been approximately 4 percentage points higher.
Looking ahead to the fourth quarter, Amazon expects revenue of $240 billion to $247 billion, with a guidance midpoint of $243.5 billion, slightly below market expectations. Sales performance during the year-end holiday shopping season and whether the advertising business can resume growth will be key focal points for the market.
Full-Year CapEx Projected to Reach $220 Billion as Free Cash Flow Turns Negative
Increased spending on AI infrastructure is putting pressure on Amazon's free cash flow.
The company expects full-year cash capital expenditures to be approximately $220 billion in 2026, primarily dedicated to expanding data centers and other infrastructure. Amazon stated that AI investments are a major driver of the recent growth in net purchases of property and equipment.
For the trailing 12 months ended in the third quarter of 2026, the company's net purchases of property and equipment, net of sales proceeds and related incentives, increased by $94.8 billion year-over-year.
During the same period, free cash flow recorded a net outflow of $42.4 billion, compared with a net inflow of $14.8 billion in the prior-year period, representing a decrease of approximately $57.2 billion.
Notably, the company's operating cash flow for the period grew 29% year-over-year to $168.3 billion, but net purchases of property and equipment surged 82% year-over-year to $210.7 billion. Because the growth in net purchases significantly outpaced operating cash flow, free cash flow swung from a net inflow to a net outflow.
AWS Revenue Grows 39% as Amazon AI Investment Returns Gain Focus
AWS remained Amazon's key growth engine in the third quarter. In the third quarter, AWS net sales grew 39.3% year-over-year to $46 billion, marking its fastest growth rate in nearly five years; operating income increased 56% year-over-year to $17.8 billion.
CEO Andy Jassy expects AWS revenue growth to exceed 40% in both 2027 and 2028.
Meanwhile, Amazon plans to continue expanding its AI infrastructure investments. The company expects cash capital expenditures to reach approximately $220 billion in 2026, with 2027 levels significantly exceeding this figure. As the scale of investment expands, whether AWS can sustain rapid growth and drive profit gains will be a key focus for the market.
As of September 30, 2026, Amazon's trailing 12-month free cash flow had fallen to negative $42.4 billion. If capital expenditures continue to grow while free cash flow fails to improve, market concerns over AI investment returns and capital requirements could further intensify.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.