


【US Pre-Market】Nvidia Rebounds Over 2%; Microsoft Falls Over 2% Amid Massive Global Outage; October PPI Due



AI Podcast


On Eastern Time November 13, U.S. stock index futures rose modestly following broad declines driven by Nvidia CEO Jensen Huang’s resignation and Microsoft service outages. Commodities remained elevated amid rising Treasury yields and inflation concerns, heightening expectations for a December Federal Reserve rate hike ahead of the October PPI release. Meanwhile, Nvidia rebounded premarket as interim leadership assumed control, Microsoft addressed infrastructure outages, and Modine Manufacturing surged on reported acquisition talks with Samsung. Cerebras advanced significantly following strong third-quarter revenue growth and raised full-year guidance.

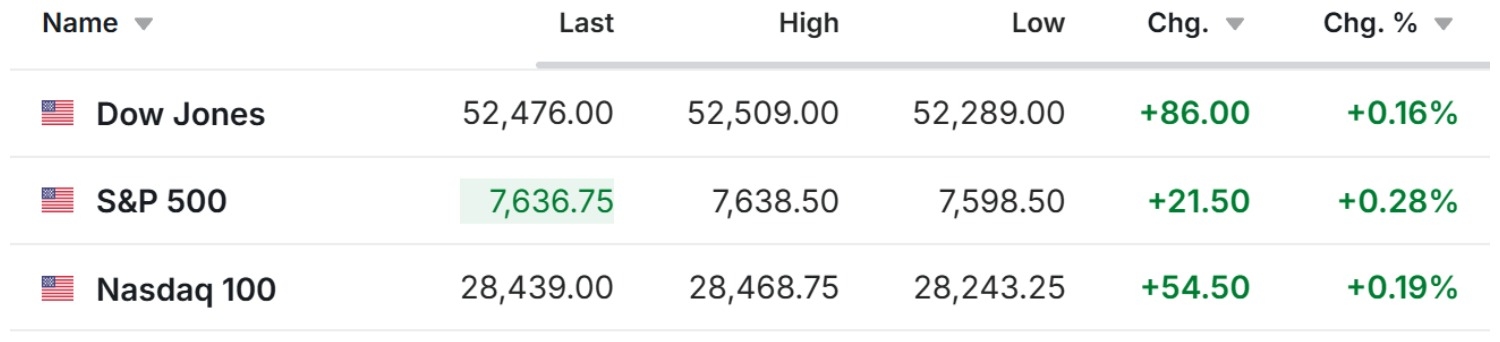
TradingKey - On Friday, November 13, Eastern Time, the three major U.S. stock index futures rose across the board. As of press time, Dow futures were up about 0.16%, S&P 500 futures gained about 0.28%, and Nasdaq 100 futures rose 0.19%.
[Source: Investing]
A day earlier, the three major U.S. stock indexes closed lower across the board, with the Dow falling 0.36%, the S&P 500 losing 0.35%, and the Nasdaq Composite Index dropping 0.39%. The resignation of Nvidia CEO Jensen Huang triggered market turmoil, while an outage in Microsoft's Microsoft 365 service also drew focus among tech stocks.
In commodities, international oil prices remained elevated, with Brent crude (UKOIL) rising to near $94.78 per barrel, and WTI crude (USOIL) at approximately $87.75 per barrel. The 10-year U.S. Treasury yield previously climbed above 5.1%, reaching its highest level since October.
Gold (XAUUSD) is currently trading at $3,894.5 per ounce; Bitcoin (BTCUSD) briefly slipped below $69,000, touching its lowest level since mid-August. Rising oil prices and climbing U.S. Treasury yields have heightened market concerns over inflation and a December rate hike by the Federal Reserve.
Market Movers
Nvidia (NVDA) rebounded over 2% premarket as the market focused on the leadership transition following Jensen Huang's resignation.
Nvidia rose about 2.7% premarket after its shares experienced sharp volatility the previous day. The company confirmed on November 12 that co-founder and CEO Jensen Huang resigned as president, CEO, and director, effective immediately. The move followed reports regarding his personal relationships and potential national security risks, which had drawn significant attention.
The company appointed CFO Colette Kress as interim CEO, initiated a search for a permanent successor, and named Harvey C. Jones as its first chairman of the board. Following Huang's departure, the market is watching whether the new management can maintain the company's current operating strategy and whether R&D and delivery schedules for products such as Blackwell and Vera Rubin will be affected.
Nvidia stated that existing operations, customer commitments, and product roadmaps will continue to move forward. The company's fiscal 2027 third-quarter earnings report, originally scheduled for release on November 17, remains on track as planned.
Microsoft (MSFT) fell over 2% premarket as recovery from global Microsoft 365 service outages remains ongoing.
Microsoft fell about 2.3% premarket. On November 12, Exchange Online experienced connectivity issues that subsequently affected certain features of Microsoft 365 services, including Outlook, Teams, SharePoint, and Copilot, with users across multiple countries and regions reporting that they were unable to access the services normally.
Microsoft stated that the outage involved issues with portions of its infrastructure and server connectivity, and that the company is rerouting network traffic and restoring affected services. As of November 13, some users remained impacted, and Microsoft had not yet announced that all services were fully restored.
AMD (AMD) and Broadcom (AVGO) pulled back premarket as semiconductor stocks diverged.
AMD and Broadcom had gained about 5.9% and 5.5%, respectively, on the previous day, benefiting from capital reallocation within the semiconductor sector following the decline in Nvidia's share price. However, in premarket trading on November 13, the two companies dropped about 1.8% and 2.4%, respectively.
Nvidia's leadership changes have heightened near-term volatility across the AI chip sector. However, switching chip suppliers involves product performance, software compatibility, supply capacity, and qualification procedures, so this cannot be taken as evidence that Nvidia's customers are shifting to competitors.
Going forward, it will be necessary to monitor order trends for AMD's Instinct accelerators and Broadcom's custom AI chips, as well as procurement plans among major cloud service providers.
Modine Manufacturing (MOD) surged over 25% premarket on reports of acquisition talks with Samsung.
According to Bloomberg, Samsung Electronics is in talks to acquire U.S. data center cooling equipment maker Modine Manufacturing, with a deal potentially being reached as early as within the coming weeks. Boosted by the news, Modine's shares surged.
Modine has focused in recent years on expanding its AI data center cooling business. If the acquisition is completed, Samsung is expected to broaden its business footprint in data center liquid cooling and thermal management, further penetrating the AI infrastructure supply chain. However, neither party has confirmed a final agreement so far, and the transaction remains subject to uncertainty.
Cerebras (CBRS) rose over 19% premarket at one point as third-quarter Core revenue grew 70% and full-year guidance was raised.
After Cerebras reported its third-quarter results, its shares rose over 19% in extended trading. As of press time, Cerebras was up over 16% premarket.
The company's third-quarter GAAP revenue reached $210.8 million, up 55% year over year, while Core revenue was $230.9 million, up 70% year over year. Among this, GAAP cloud computing and other services revenue was $141.9 million, representing a 265% year-over-year increase.
The company expects fourth-quarter Core revenue of $310 million to $330 million and raised its full-year 2026 Core revenue guidance to $940 million to $960 million. The company also disclosed that it has entered into commercial partnerships with two new hyperscale cloud providers, securing contracted data center capacity of 700 megawatts.
Market News
U.S. October PPI is due to be released as expectations of a December rate hike heat up.
The U.S. Bureau of Labor Statistics will release the October PPI at 8:30 a.m. Eastern Time on November 13.
The market expects headline PPI to rise 0.4% month-over-month and 6.6% year-over-year, and core PPI to rise 0.3% month-over-month and 5.0% year-over-year, both lower than September's increases.
Previously released October CPI rose 0.4% month-over-month, topping market expectations of 0.3%. Currently, interest rate futures indicate an approximately 87% probability of a 25-basis-point rate hike by the Federal Reserve in December.
If the PPI comes in higher than expected, it could further push up U.S. Treasury yields and increase valuation pressure on tech stocks; if it comes in lower than expected, it could ease market concerns over persistently high inflation.
Trump said the U.S. no longer needs to reach a deal with Iran, keeping oil prices elevated.
Trump stated that the U.S. no longer needs to reach a deal with Iran and asked Vice President Vance to shift his focus to domestic affairs, dampening market expectations for ending the conflict between the U.S. and Iran through diplomatic negotiations.
On November 13, Brent crude was around $95.4 per barrel and WTI crude was around $88.5 per barrel. Although Middle East energy supplies still face risks, weighed down by rising supply and market demand concerns, both oil benchmarks are expected to fall for a second consecutive week.
If tensions between the U.S. and Iran remain high, shipping through the Strait of Hormuz and oil supplies could still be affected, thereby increasing uncertainty for energy prices and inflation.
Key Events Preview
Eastern Time | Event |
November 13, 8:30 | U.S. October PPI and Core PPI |
November 13, 10:30 | U.S. EIA Natural Gas Storage |
November 13, 13:00 | U.S. Baker Hughes Oil Rig Count |
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.