


Qualcomm Stock Forecast: $5 Billion AI Target Meets $166.05 Resistance



AI Podcast


Qualcomm closed down 9.49% following fourth-quarter results showing an 8% drop in GAAP revenue to $10.32 billion and a 26% decline in handset sales, outweighing growth in automotive and IoT segments. While management targets $5 billion in fiscal 2027 data-centre revenue and expanded infrastructure opportunities, customer incentives, upfront investments, and high input costs pressure margins. Capital returns recently exceeded free cash flow, raising cash-generation importance. Technically, the stock remains bearish below $166.05 resistance, with immediate support at $145.63 and a downside target of $136.57, while a daily close above $176.04 would invalidate the negative setup.

TradingKey - Qualcomm (NASDAQ: QCOM) closed November 5 at $156.75, down 9.49%, after its November 4 results. The stock recovered from a $150.06 opening price but stayed below the broken $166.05 support level, according to historical trading data.
The investment debate is how quickly new businesses can replace lost handset earnings. Management’s $5 billion fiscal 2027 data-centre target offers a growth opportunity, while customer incentives, upfront investment and higher input costs complicate the return shareholders can expect.
Handset Weakness Still Outweighs Automotive Growth
Fiscal fourth-quarter GAAP revenue fell 8% to $10.32 billion. Adjusted revenue declined 7% to $10.44 billion, and adjusted EPS fell 28% to $2.17. Handset revenue dropped 26% to $5.14 billion.
Automotive revenue rose 89% to $1.99 billion, while Internet of Things sales increased 4% to $1.89 billion. Vehicle-related sales are becoming substantial, but the handset decline still outweighed those gains.
Amazon’s AI Opportunity Includes Shareholder Costs
Management reaffirmed its $5 billion fiscal 2027 data-centre target and expects more than $650 million in the December quarter as custom silicon shipments begin. Two hyperscaler programs underpin the initial ramp, making customer deployment schedules central to execution.
The Amazon agreement includes warrants permitting an affiliate to acquire up to 25 million Qualcomm shares at $161.26 apiece. Vesting depends on commercial arrangements, purchase orders and spending milestones. Qualcomm valued the grant at about $1.8 billion, according to its annual filing.
These incentives can help secure long-term demand, but introduce potential dilution. Their accounting value reduces revenue as related sales are recognized. I would assess the business on earnings and cash per share after customer incentives, rather than treating every dollar of targeted revenue as equally profitable.
Cost Recovery Arrives After the Initial Investment
Qualcomm expects the full benefit of product-pricing actions to appear in the second half of fiscal 2027. Higher costs across fabrication, packaging and other inputs create pressure before those changes fully reach customers.
December-quarter QCT guidance calls for an earnings-before-tax margin of 20% to 22%. QCT is the semiconductor segment, which begins including data centres in fiscal 2027. Management puts the initial margin impact of that addition at about three percentage points, reflecting investment ahead of the revenue ramp.
The change requires comparable segment definitions when judging performance. A lower reported QCT margin can partly reflect businesses moving into the segment, while the underlying development spending still affects consolidated profitability.
Licensing Helps, but Tax Effects Complicate Earnings
Qualcomm renewed long-term licensing agreements with Apple, Huawei and Transsion. Royalty relationships support the QTL licensing business even as Apple-related chip sales decline. Renewal announcements therefore offer evidence about intellectual-property income, with product sales requiring a separate assessment.
Full-year GAAP earnings also benefited from a $5.7 billion income-tax adjustment associated with releasing a valuation allowance in the second quarter. That accounting benefit makes fiscal-year headline EPS a poor standalone measure of recurring performance. The weaker fourth-quarter adjusted EPS provides a clearer warning about current operating pressure.
Starlink Expands the Infrastructure Opportunity
SpaceX selected Qualcomm’s Dragonwing cellular infrastructure platforms for Starlink Mobile’s planned US terrestrial 5G network. Deployment is expected to begin in 2027, covering tens of thousands of sites over a multiyear agreement.
The project opens another market for Qualcomm’s radio and baseband technology. However, the announcement gives no contract value, so site counts cannot establish expected revenue. Construction progress and actual equipment shipments will determine the pace of monetization.
December Results Must Show Profitable Conversion
Guidance calls for December-quarter revenue of $10.4 billion to $11.2 billion and adjusted EPS of $2.15 to $2.35. The next quarterly report will test the early data-centre ramp and the trajectory of handset demand.
Funding discipline also matters. Fiscal 2026 operating cash flow of $11.145 billion less $2.494 billion in capital expenditure leaves $8.651 billion. Repurchases and dividends totaled $11.671 billion, about $3.02 billion more than that cash measure.
That difference raises the importance of cash generation as investment expands. Continued handset weakness or slower collections would make that balance harder to achieve.
Qualcomm Technical Analysis: $166.05 Is the First Reclaim Test
Qualcomm’s latest completed close at $156.75 followed a gap beneath the $166.05 to $176.04 support zone and its rising channel. The daily candle was green because price recovered from its opening level. Relative to the previous close, however, the stock still lost 9.49%, so the candle color overstates the strength of the recovery when viewed alone.
I remain bearish while rallies fail below $166.05. A rejection at that former support would favor renewed pressure toward $145.63. A daily close below $145.63 would expose the next marked support at $136.57.
RSI at 37.53 indicates weak momentum without reaching oversold territory. MACD remains below zero and its signal line, reinforcing the damaged trend. The supplied $160.00 overnight quote shows a separate-session rebound still beneath the broken zone.
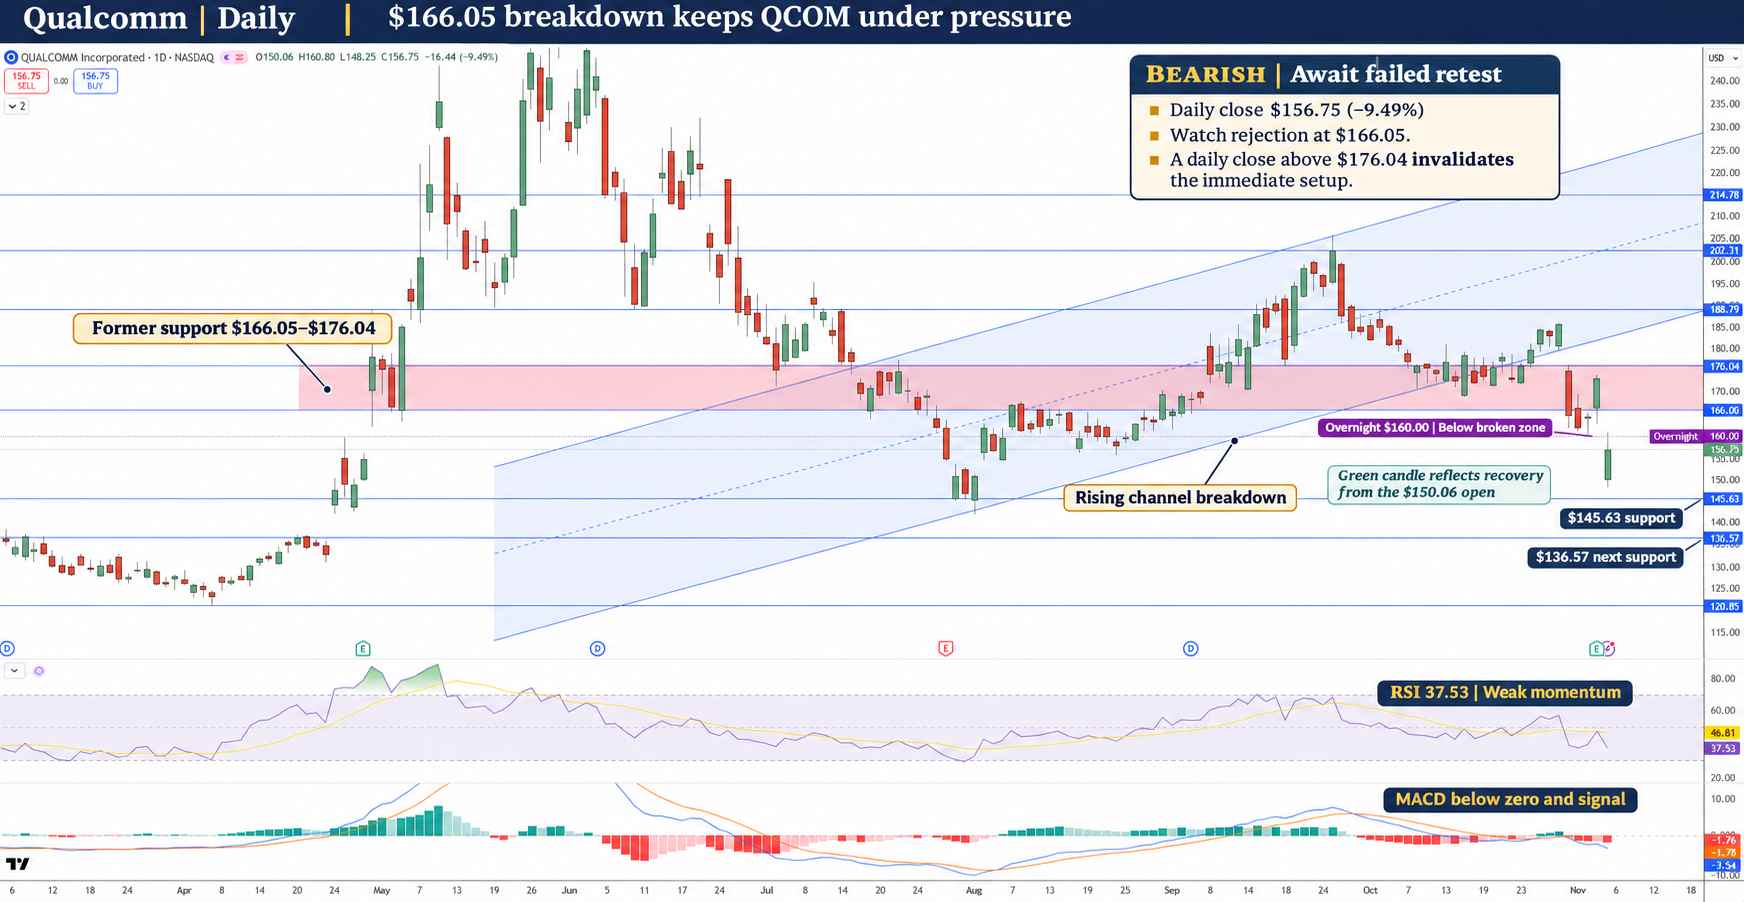
QCOM Price Chart - Source: Tradingview
Reclaiming $166.05 would improve the immediate outlook, but a daily close above $176.04 is needed to invalidate the bearish setup. That would recover the full marked resistance zone and strengthen the recovery case.
Key Levels
- Latest completed close: $156.75 on November 5
- Immediate resistance: $166.05
- Upside test and bearish invalidation: $176.04
- Immediate marked support: $145.63
- Downside target: $136.57
- Daily RSI: 37.53, weak but not oversold
FAQ
Can Qualcomm’s AI business offset falling handset sales?
It could contribute meaningfully, but the $5 billion fiscal 2027 target remains a forecast. Deployment timing and profitability will determine the benefit.
What would improve QCOM’s technical outlook?
A reclaim of $166.05 would be the first improvement. A daily close above $176.04 would invalidate the immediate bearish call.
Bottom Line
Automotive growth and AI shipments support diversification, but handset weakness and delayed cost recovery keep the outlook cautious. The chart remains bearish below $166.05, with $145.63 in focus. A daily close above $176.04 would change that view.
Recommended Articles











Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.