


Micron Stock Forecast: AI Memory Boom Meets a High-Stakes Q4 Earnings Test



AI Podcast


Micron enters its fiscal Q4 earnings report with strong fundamentals, backed by record Q3 performance, expanding gross margins, and roughly $100 billion in remaining performance obligations from strategic customer agreements. High-volume shipments of HBM4 and surging AI-driven data center demand continue to tighten the DRAM market, supporting pricing power. While a Netlist patent complaint introduces minor legal uncertainty, investors remain focused on forward guidance, capital expenditure plans, and margin sustainability. Technically, the stock maintains a bullish-neutral posture, holding an uptrend above the $1,030.76 support level, with a decisive close past $1,107.66 required to confirm further upside.

TradingKey - Micron (MU) has its Q4 earnings this month. Strong operations and a bullish financial setup make this stock poised to outperform. MU closed on September 29 at $1,065.08. On September 29th, it gapped up before quarterly announcement. Investors of MU are worried about AI’s impact on memory demand. Memory is one of MU’s major product lines. Will memory demand and consumption sustain MU’s strong financial performance? Only time will tell.
Earnings Are Still Ahead
MU will report Q4 earnings on September 30 after the markets close. An earnings call will be held at 2:30 MT/ 4:30 ET. This article will be updated to include earnings. As of now, this will be a preview article. MU guided Q4 revenue between $49-51 billion. MU expects a gross margin of 86%. Management expects a non-GAAP EPS of $31 with a range of $30-32. Visible Alpha consensus is about $50.95 billion, near the top end of revenue guidance. Based on analysts estimates and MU’s guidance, forward looking statements are more important than back tested statements. Investors expect strong growth for MU in the near term.
Q3 Established an Exceptional Earnings Base
Micron had an outstanding fiscal Q3. Revenue increased to $41.46 billion from $23.86 billion in the previous quarter and $9.30 billion in the same quarter last year, respectively. GAAP net income was $28.24 billion, or $24.67, per diluted share. On a non-GAAP basis, net income was $28.86 billion, or $25.11, per diluted share. GAAP gross margin was 84.6% and non-GAAP gross margin was 84.9%. Operating cash flow was $25.39 billion. While extremely impressive, the year-over-year and quarter-over-quarter growth is not the only important metric. Of equal importance is the simultaneous expansion of gross margin and cash flow. This supports pricing power, and durability of Micron’s earnings. The industry is eager to see if the memory cycle will become more structurally stronger, rather than purely a less-favorable but still strong quarter.
Strategic Customer Agreements Improve Visibility
Micron had completed 16 of its “strategic customer agreements” by its Q3 earnings call, including agreements executed after the end of fiscal Q3. These agreements represent more substantive booking commentary. In the case of Micron, these agreements are typically take-or-pay contracts, meaning the customer is obligated to pay for the product whether it is taken delivery of or not, for a defined contract period. In these agreements, price is set at a floor and/or ceiling, and volume commitments are for multiple years.
As of the end of fiscal quarter three, Micron disclosed more than $5 billion of remaining performance obligations, while RPO for the SCAs signed so far, including agreements executed after quarter-end, was approximately $100 billion. Management indicated expected revenue for those contracts would be in excess of the $100 billion RPO. The approximately $100 billion RPO does not represent near-term revenue, but the agreements provide more advanced visibility of customer commitments, beyond prior memory cycle.
HBM4 Is Already Shipping
HBM4 is in production and Micron is no longer just sampling it. Micron is shipping HBM4 in high volume for its lead customer’s platform. Micron has also shipped qualification samples to multiple end customers. There is also a variant, HBM4E, in development. HBM is expected to consume a large share of DRAM wafer capacity. Understanding HBM’s production and customers will be useful to understand Micron’s earnings and products in the future. HBM, along with other Micron products, may increase their production and be complementary to other products to improve Micron’s blended margins.
AI Demand Is Tightening the Broader DRAM Market
Higher demand for AI and data center products is likely to increase the demand for DRAM. HBM makes up around 20% of the DRAM production mix today and is expected to increase to around 30% by 2027, according to Samsung. Higher demand for HBM will also increase competition for the other DRAM production. A tight DRAM market will also work in Micron’s favor. Increased demand for HBM may allow Micron to raise prices, and potentially increase production. Tighter supply in the market may also work in Micron’s favor to improve prices and production, provided that Micron’s capacities are strategically placed to meet higher demand.
Data Center Demand Is Broadening
Micron's Quarter 3 Report showed revenues of more than $25 billion from data centers, with more than $5 billion of that from data center SSDs.
HBM is only one part of Micron’s data-center AI opportunity; data-center SSD revenue alone exceeded $5 billion in Q3. Given Micron produces HBM, as well as data center and enterprise SSDs and Server DRAM and Registered DIMMs, the variety of offerings in Micron’s product portfolio is positive, as it balances the company’s risks based on product cycle variations. Additionally, the variety shows that AI is requiring denser interconnects and memory throughout the data center, thereby driving an increase in AI workloads.
Capital Spending Is the Next Big Question
Micron is positioned well for the increasing AI investments, and it seems likely that Micron will increase its capital expenditures for HBM, DRAM, and Packaging fabrications. How quickly Micron invests will depend on the expected return and customer contracts. It is positive that Micron has long-term agreements with strategic customers, as it provides better visibility for Micron on potential future contracts. I would view Micron more negatively if increases to capital expenditures occurred more quickly than expected long-term customer contracts.
Netlist Adds a Separate Legal Risk
Netlist filed a complaint to the U.S. International Trade Commission to block imports of Micron HBM memory products. The complaint involves two patents covering HBM technology and also targets Google, NVIDIA and Broadcom products that incorporate the disputed Micron memory technology. Micron declined to comment on the complaint. This complaint seeks a ruling and/or relief from the ITC; however, an exclusion order has not been issued. In the context of the demand and supply factors of the investment thesis, this complaint should be considered apart. While legal actions create uncertainty in an investment thesis, this complaint should not be viewed that way at this time.
Valuation Looks Low Only if Earnings Stay High
Micron’s multiple valuation compared to other competitors in the AI semiconductor space is favorable. However, there are points to consider. First, Micron is expected to grow and improve its gross profits and margins to the levels projected by analysts. Second, if the overall semiconductor market begins to improve, the forward multiples of Micron’s stock could contract. Also, if memory pricing and expectations improve, Micron’s valuation multiples could improve. However, if memory pricing expectations decline, Micron’s multiples could quickly expand. Thus, in my view, the earnings call should focus on potential improvement in memory pricing, and where margins could improve from current levels.
Micron Technical Analysis: MU Consolidates Below $1,107 as Bulls Defend $1,030
Micron’s last verified completed close is at $1,065.08. The 4 hour chart shows the price around $1,065. The larger trend is still up after the recovery from the September lows. MU trades above its moving averges and has formed a series of higher lows. The Relative Strength Index (RSI) is at 60. RSI is above the 50 center line but below its moving average, suggesting bullish-neutral momentum with some consolidation.
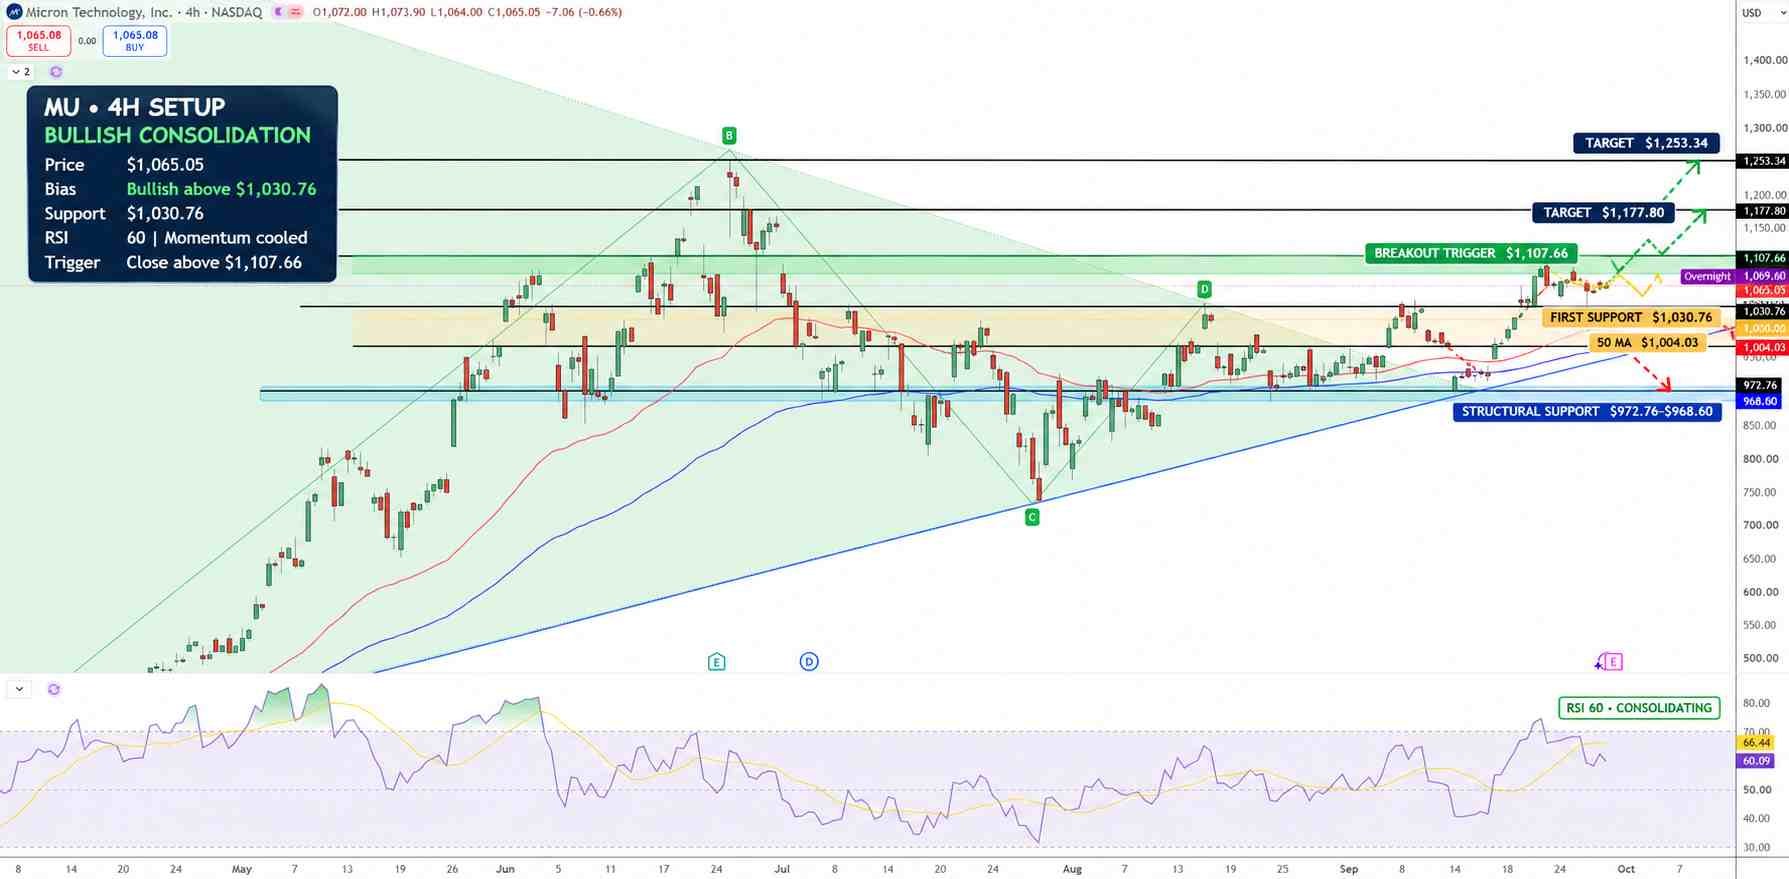
Micron Stock Price Chart - Source: Tradingview
A possible bearish reversal occurs if the price closes below the $1,030.76 support level. The 50 SMA, around $1,004.03, and $972.76 and $968.60 levels, would also provide support. The resistance levels are at $1,107.66 and $1,177.80. A closing price above $1,107.66 would indicate an up-trend, with the next upside target at $1,253.34. I think the price of MU will continue to trade higher as long as it does not closes below $1,030.76. The release of Micron’s earnings report will likely determine the short term trend of MU.
Key Levels
• Closes at: $1,065.08
• Completed at: $1,065.08
• Last verified: September 29, 2026
• Expected Support: $1,030.76, $1,004.03, $972.76, $968.60
• Expected Resistance: $1,107.66, $1,177.80, $1,253.34
• RSI: ~60 Bullish Neutral
Why is Micron stock in focus now?
Earnings for Micron's fiscal Q4 is expected after the close on 9/30. HBM4 is expected to play a large role in product demand going forward and how Micron strategically positions themselves with customer contracts going forward. How quickly Micron needs to invest going forward is also expected to be of interest.
What level confirms a stronger MU breakout?
Bullish breakout above $1,107.66 is expected to lead to $1,177.80. Support is expected to be $1,030.76, $1,004.03, and $972.76.
Bottom Line
Q3 showed record revenue with high operating margins and cash flows. Micron is now benefiting from high levels of visibility in the memory cycle due to HBM4 shipments and customer agreements. The main risk for Micron is now mostly baked into the stock price.
Investors will be focused on forward guidance. With gross margins expected to be approximately 86% in Q4 and revenue expected to be near the top of the range, Micron will need strong guidance to continue the positive earnings revision cycle.
From a technical perspective, the stock has an uptrend as long as it remains above $1,030.76. A break above $1,107.66 would be bullish and lead to further gains to $1,177.80. A move below $1,030.76 would be bearish.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.