


FactSet Stock Forecast: Can AI and Subscription Growth Halt FDS’s September Slide?



AI Podcast


FactSet Research Systems prepares to report fiscal Q4 results, with investor focus centering on fiscal 2027 guidance and margin pressures from rising compensation and technology costs. While strong subscription growth, high retention rates, and robust cash flows underpin its recurring-revenue model, operating margins have declined. Strategic acquisitions like BCC Group and Google Cloud AI integrations offer long-term catalysts. Technically, the stock exhibits bearish momentum, trading below key moving averages with immediate support at $255.03. A break below this level targets $240.23, whereas a recovery above $275.65 resistance is required to signal a bullish reversal.
TradingKey - FactSet Research Systems (NYSE: FDS) is set to report fiscal Q4 results on September 30, with the earnings presentation available at 8:30 a.m. ET before the market opens. FDS closed at $259.97 on September 29, a decrease of 2.88% and an intraday low of $252.05. The key question is if FDS can regain the confidence of the market after the sell off in September.
Q4 Earnings Put Fiscal 2027 Expectations in Focus
FDS’s report for the quarter ending August 31, 2026 is expected to report results for the fiscal year ending August 31, 2026, as well as give guidance for fiscal 2027. As of the time of this writing, the earnings presentation is scheduled to be available at 8:30 a.m. ET, with the call to follow at 9:00 a.m. ET.
Because of the aforementioned release schedule, we are limited in what we can say.
Because FDS has a history of beating estimates, many analysts are looking for management to give forward-looking statements. Most importantly, investors will consider if FDS provided a sufficiently lengthy runway for growth.
Subscription Growth Remains the Core Strength
FactSet experienced a 6.4% revenue increase to $622.9 million for its third quarter of fiscal 2026. Organic revenue grew by 7.0%. The company reported its organic annual subscription value (ASV) increased by 7.1% to $2.486 billion. With ASV continuously increasing, and 95%+ ASV retention, FactSet has unprecedented revenue visibility. Rising retention levels and increasing ASV support the recurring-revenue business model. This is further illustrated by enterprise renewals extending in length by an average of 30%. Strong recurring demand has not gone unnoticed. For FactSet to convert this recurring demand to greater operating profit, positive changes to operating margins should be expected.
Margins Are the Main Weakness
FactSet's Q3 2026 operating margins decreased to 26.7% from 33.2% during the same period in 2025. Adjusted operating margins decreased to 34.0% from 36.8% in 2025. Management attributed the declines to increased compensation and technology costs. EPS declined in accordance with these trends. GAAP diluted EPS fell to $3.50 from $3.87 in 2025. Adjusted EPS increased 6.1% to $4.53. Operating profit would have been better allocated to improve operating margins than to be absorbed by share repurchases in order to improve EPS.
Cash Flow Still Provides Support
Positive cash flow, positive free cash flow. FactSet holds a lot of advantages as an investment, and their cash flows illustrate a clear path to growth. FactSet reported operating cash flow for the third quarter to be $284.5 million, a 12.1% increase year over year. Their free cash flow for the quarter was $254 million, a 11.1% increase year over year. While investing in growth and cash flow positive, there are areas for improvement. For example, BCC Group International may help address operational leverage. As artificial intelligence and software solutions become increasingly embedded, FactSet may see improvement in their annual subscription value.
BCC Expands Real-Time Market Data Capabilities
FactSet announced the acquisition of BCC Group International on September 22. As FactSet transitions to provide more real-time data solutions, the acquisition should help integrate BCC's real-time data distribution and permission control solutions. The deal is not expected to have a material impact on FactSet’s financial results. Given the competitive nature of the real-time data distribution market, this acquisition helps further FactSet's real-time data solutions and may help secure larger enterprise contracts.
Google Cloud Raises the AI Opportunity
FactSet’s collaboration with Google Cloud integrates FactSet’s Workstation with the AI capabilities of Gemini. This collaboration, as well as others, will help FactSet serve portfolio management and M&A clients. FactSet further mentioned that more than 90% of its top 50 clients utilize 4 or more FactSet AI products. While this collaboration creates an opportunity for FactSet to serve its clients better and potentially increase its revenue, it is unlikely to impact revenue in the short term. This will be the case unless clients increase their spending, or FactSet’s AI products help the company operate more effectively and profitably. AI products may be financially beneficial only if they lead to increased Annual Subscription Value (ASV).
Fiscal 2026 Guidance Sets the Baseline
FactSet’s guidance for fiscal year 2026 is revenues of $2.45 to $2.47 billion. Adjusted operating margin is expected to be between 34% and 35.5%. Adjusted diluted EPS is expected to be between $17.25 and $17.75. The company expects its Organic ASV will grow between $130 million and $160 million. At the end of September, the company’s stock was trading at approximately 14.9 times the midpoint of the company’s adjusted EPS guidance for fiscal year 2026. Investors believe the valuation is reasonable for a company with a high client retention rate subscription business.
Investor Day Adds Another Catalyst
FactSet will host its Investor Day on November 10. We expect the company to provide its strategic and financial outlook, as well as provide additional color on its products. With economic uncertainty likely to remain relevant next year, conservatism in FactSet's guidance is warranted. However, conservative guidance could allow FactSet to enhance its AI offerings, create a data services offering similar to its peer, and/or further monetize its AI and data offerings — all of which could aid in margin expansion. Stable and increasing forward looking revenue metrics would justify the valuation multiple and provide a floor on the stock.
FactSet Technical Analysis: FDS Tests $255 Support as Downtrend Pressures Bulls
FactSet closed its most recent session at $259.97. Price continues to decline and recently tested support intraday. Price sits below both the 50 and 200 day moving averages, trades below its rising trendline, and recently printed a lower high. The rising trendline and support at $255.03, are illustrated and in play. A break below $255.03 could see price target $240.23.
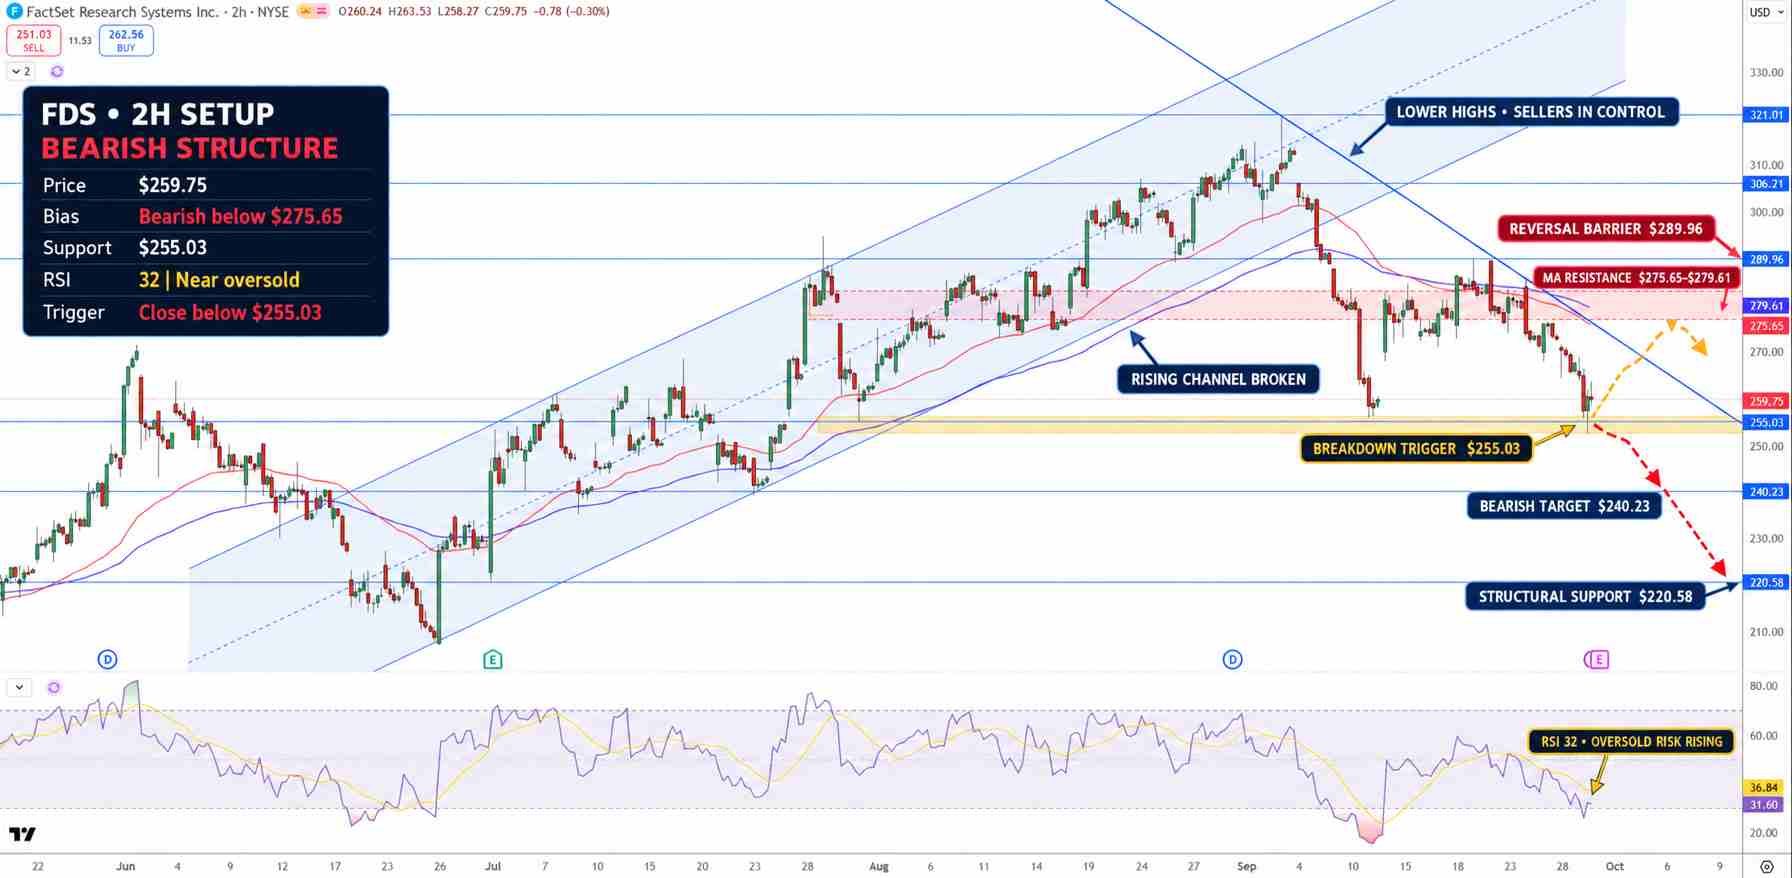
FactSet Stock Price Chart - Source: Tradingview
Currently, RSI is at 32, below its signal line near 37. This reading indicates that downward momentum is dominating and the stock is near oversold conditions. The next major downside support level is found at $255.03. A break below this area on the 2 hour chart would confirm additional downside and open the $240.23 level. If the stock breaks below the $240.23 level, even more downside is likely towards the $220.58 level.
Taking a more bullish outlook, the first major upside barrier is located at $275.65 and $279.61. If these levels are broken, the $289.96 level comes into play. Based on these levels, a bullish case can be made. For the time the FDS is below $275.65 and $279.61, I will be looking for further downside opportunities.
Key Levels
• Latest Close: $259.97
• Major Support Levels: $255.03 / $240.23 / $220.58
• Major Resistance Levels: $275.65 / $279.61 / $289.96
• RSI: 32
• Breakdown Levels: Support at $255.03, Bearish Target $240.23
Why is FactSet stock in focus now?
FactSet is set to release its fourth quarter and full-year 2026 results on September 30. Investors will be interested to see how the company is extending its customer contracts and integrating AI and other solutions to offset pressure on margins.
What level confirms a stronger FDS recovery?
In the near-term, a move above the resistance level at $275.65 to $279.61 would be constructive. A close below the support level at $255.03 would confirm the bearish outlook and open the potential for a move lower to $240.23.
Bottom Line
FactSet is set to release its earnings with a positive outlook on its core business, but under pressure on margins. There is positive news from its customer retention and cash flow, as well as its partnership with Google. Negative news is potentially operating margins. If margins tighten, FactSet will have to demonstrate how it is increasing technology and headcount to improve earnings. From a technical analysis perspective, FDS is bearing bearish sentiment. Support is expected at $255.03, while $275.65 to $279.61 is resistance. A close below $255.03 would indicate a further bearish sentiment and set a target at $240.23. Alternatively, a move to $270 to $280 is possible if the recent sell off is overdone.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.