


McDonald’s Stock Forecast: AI Pricing and $8.5 Billion Plan Test MCD’s Recovery



AI Podcast


McDonald’s demonstrates solid Q2 earnings with revenues reaching $7.1 billion and a 4% dividend increase to $7.72 annually, yielding roughly 3.3%. However, declining U.S. guest counts, inflationary pressures, and machine-learning pricing strategies pose brand-value risks. The long-term $8.5 billion NEXT recovery plan aims to boost franchisee efficiency through 2036. Technically, MCD trades in a downward channel below key moving averages with an oversold RSI of 27. Major support stands at $232.11, while resistance is pegged at $240.74. Sustained traffic recovery and improved customer perception of value remain crucial for medium-term stock appreciation.
TradingKey - McDonald’s (MCD) closed Tuesday at $233.98, up 0.16% on the day but still well below the level it was at prior to its September 23 investor event. McDonald’s expects its business to improve over time due to positive changes to its business operations and the support it gives its franchisees. One of the changes it has made recently is adjusting prices based on changes in market conditions. A bigger concern should be how the changes and support impact McDonald’s brand.
AI Pricing Raises a Customer-Value Question
McDonald’s recently began using ML to recommend prices. Reuters reported that prices are recommended based on what McDonald’s estimates customers are willing to pay. According to McDonald’s, its franchisees set prices, and the ML is used to merely recommend prices. The company stresses that this is not true centralized pricing. AI-assisted pricing raises concerns, especially if prices are set to give the perception that items are on sale. This sends the message to customers that McDonald’s is no longer a value destination. Additionally, if prices are set too high, McDonald’s runs the risk of not reaching its volume goals.
Valuation concerns are not as pressing as customer value concerns. McDonald’s must ensure it improves customer perception of value to remain a destination for value meals.
Q2 Earnings Grew, but U.S. Traffic Remained Weak
Q2 revenues came in at $7.1 billion, an increase of 4% over the prior year. Operating income increased to $3.34 billion. Net income increased to $2.36 billion. Diluted EPS was $3.32, an increase of 6% over the prior year. Adjusted diluted EPS was $3.38. Global comparable sales increased 1.3%. The U.S. increased 0.8%. Comparable guest counts decreased in the U.S. Increases in average check sizes and favorable product mixes resulted in the U.S. sales increases. McDonald's depends on value offers to increase customer visits and average check sizes. I expect value offers will continue. Offers need to be sufficient to motivate customer visits and to increase the average check size. McDonald's has not been able to use promotional offers to create a traffic increase and improve recurring customer visits.
The $8.5 Billion NEXT Plan Extends the Recovery Timeline
Franchisee level investments are supported by funds provided by McDonald’s. Through 2036, the total investment is expected to be about $8.5 billion. About $5 billion of that support is expected through 2030. McDonald’s expects a Corporate Operating Margin in the low to mid 50s, and approximately 250 bps of gross restaurant-level efficiency gains by 2030. Longer term objectives may be realistic; however, the objectives may require significant operational changes. McDonald’s has the opportunity for improvement in customer service and restaurant speeds; however, these objectives may place McDonald’s at greater operational risks. McDonald’s needs to demonstrate to its investors that the objectives will create increased restaurant sales to improve profits.
Flat Traffic Expectations Raise the Bar
Management expects industry traffic to remain flat in McDonald’s (MCD) wholly owned markets due to high inflation. Flat traffic expects negatively impact McDonald’s, which targets cost efficient value markets. McDonald’s can gain some offsets with better menu item combination, and expanding restaurant capacity and efficiency. However, McDonald’s would gain more equity story support if traffic stabilizes. Management did not guide to a traffic recovery from deflation; its investor-day outlook assumed persistent inflation and roughly flat industry traffic.
Dividend Growth Supports the Income Case
McDonald’s gains support as a dividend stock. The restaurant chain increased its quarterly dividend 4% to $1.93, and its 50th consecutive year of dividend increases. McDonald’s new annual dividend is $7.72, giving the stock a forward dividend yield of about 3.3% at the September 29, 2026 close.
They’ve increased their dividend payouts. That is a good sign for shareholders. The payouts give shareholders a return while the company works on their recovery. Payouts are determined by management and are not influenced by variables such as sales, like share price recovery is. Payouts can attract buyers and increase share price. However, the payout percentage does not increase if sales and traffic do not improve.
Valuation Is Less Demanding Than Earlier in the Year
Recently, McDonald’s shares have been trading at around 19 times their trailing earnings and 17.7 times their forward earnings. Earlier this year, the same shares traded at higher multiples. As a result, the stock has room to expand because of slower earnings growth. Currently, better traffic is needed in order to improve earnings. Lower multiples do little to improve traffic and earnings. Despite slowing operations, most analysts expect improvements in the future. Improvements in traffic are needed to improve the valuation of the stock and the consensus price target. Valuation is supportive of the stock if the company’s operations stop deteriorating.
The Next Earnings Report Needs Traffic Confirmation
The team is working to validate the next estimated earnings release date of November 4. At this time, this date is speculative. The most recent guest counts in the U.S. are a positive indicator; however, restaurant profitability would also need to improve. A negative sign would be another quarter with positive comparable sales, primarily due to mix or other pricing actions that offset decreased transactions. The lengthier recovery period granted by NEXT positively positions McDonald’s. The next report should illustrate the plan in motion.
McDonald’s Technical Analysis: MCD Tests $232.11 as Selling Pressure Reaches Oversold Levels
McDonald's closed recently at $233.98, down significantly from its recent level at $246 to $250. Currently, the price of MCD is in a channel with a downward slope and is also under both the 50 and 200 day simple moving averages.
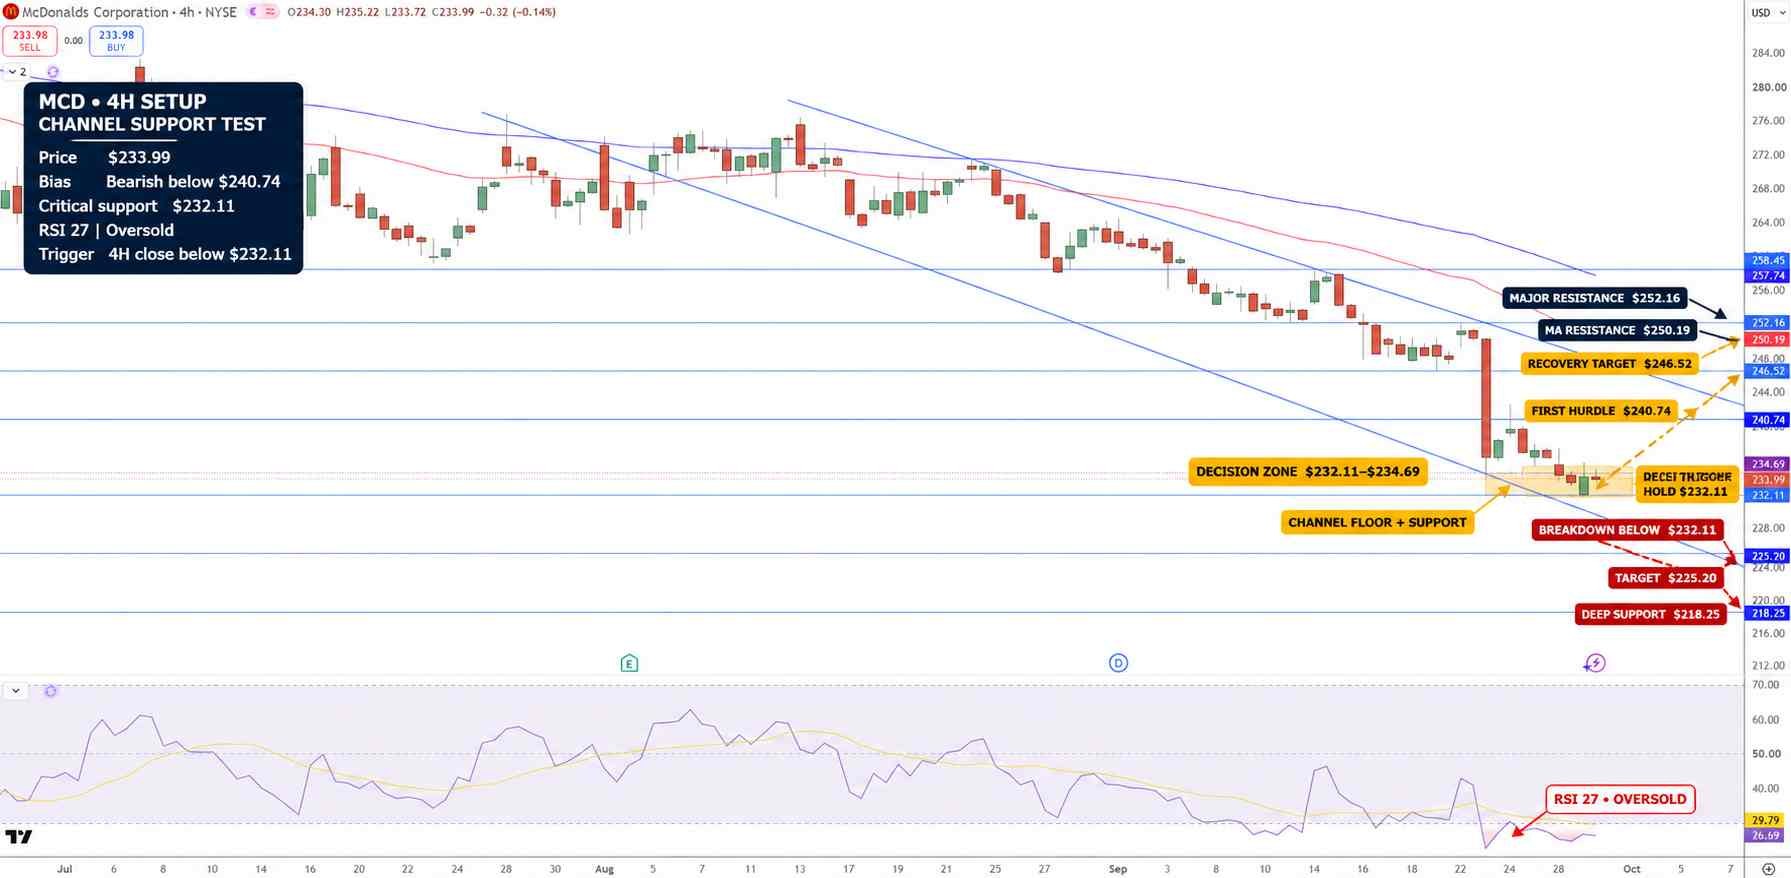
McDonald Price Chart - Source: Tradingview
Furthermore, MCD has recently broken down to the $232.11 region, which has previously offered support. Currently, the RSI is at a reading of 27, and if we combine this with the chart, it shows that the price is currently in oversold condition and that a bounce is potentially in the near future.
As indicated previously, price is potentially poised to test the $240.74 level, and if this level is taken out, price may also challenge the $246.52 level, with the 200 day moving average at $250.19 and the $252.16 level also potentially offering resistance.
As previously indicated, a break below the $232.11 level confirms the bearish bias, with the next level of support potentially coming in at the $225.20 level, and the $218.25 level offering potential support if the bearish trend continues. Overall, failure to reclaim $240.74 keeps the bearish trend intact; a sustained break below $232.11 would confirm another leg lower.
Key Levels
• Latest Completed Close: $233.98
• Major Support Levels: $232.11, $225.20, $218.25
• Major Resistance Levels: $240.74, $246.52, $250.19 - $252.16
• RSI: 27 (Oversold)
• Potential Breakdown Level: $232.11 (confirmed), $225.20
Why is McDonald’s stock in focus now?
McDonald’s is in the spotlight due to the balance of a patient-led traffic trend and the new $8.5 billion support stream, Reinforcement of the NEXT plan and associated franchisee tools and the boost to the dividend. The next traffic trend to watch is whether or not U.S. guest counts can improve while still protecting restaurant profitability.
What level confirms a stronger MCD recovery?
A sustained close above $240.74 would improve the short-term structure and support the $246.52 level. A break below $232.11 would favor $225.20.
Bottom Line
McDonald’s has a compelling long-term growth strategy. In the short-term, there are many reasons to be bearish. Increasing earnings and the dividend, as well as the NEXT strategy, offer some supports. Decreasing customer foot traffic takes a long time to reverse. The stock remains bearish under $240.74. A move down to $232.11 would be considered a buying opportunity, and a break under that would suggest $225.20 would be the next target.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.