


【US Pre-Market】Memory Stocks Including Micron, WDC and SanDisk Fall as Fed Rate-Hike Expectations Rise


AI Podcast


On Thursday, September 24, U.S. stock index futures fell in pre-market trading, driven by strong economic data, rising Treasury yields, and climbing oil prices that fueled Federal Reserve rate hike expectations. The 10-year Treasury yield hovered near 5.1%, pressuring high-valuation tech, AI, and growth stocks. Commodities saw crude oil extend gains amid U.S.-Iran supply risks, while gold and Bitcoin declined alongside a stronger U.S. Dollar Index. Meanwhile, markets awaited a bilateral meeting between Trump and Xi Jinping and an extension of the U.S.-China trade truce to January 10, 2027.

TradingKey - On Thursday (September 24) Eastern Time, futures on the three major U.S. stock indices all fell in pre-market trading. Strong U.S. economic data, international oil prices returning above $100 per barrel, and continuously rising U.S. Treasury yields prompted the market to further bet on a Fed rate hike this year; meanwhile, investors awaited talks between Trump and Xi Jinping at the White House, leaving tech stocks and high-valuation growth stocks under broad pressure.
As of press time, Dow futures fell 0.34%, S&P 500 futures dropped 0.57%, and Nasdaq 100 futures slipped 1.03%. The yield on the 10-year U.S. Treasury note hovered near 5.1%, while the 30-year U.S. Treasury yield rose to its highest level since 2004.
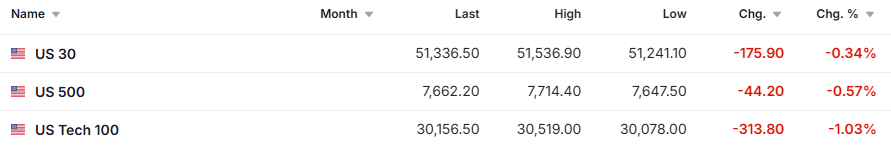
Source: Investing
In commodities, international oil prices extended gains, with WTI (USOIL) crude rising to around $93.2 and Brent crude surging to near $99.5. Significant differences remain between the U.S. and Iran over ending the conflict, lifting port blockades, and reopening the Strait of Hormuz, with supply risk premiums continuing to support oil prices.
Gold (XAUUSD) fell about 0.6%, trading around $4,260. The U.S. Dollar Index climbed to near 101, while rising Treasury yields and mounting Fed rate hike expectations continued to weigh on the appeal of non-yielding assets.
In cryptocurrencies, Bitcoin (BTC) fell to around $84,000, down about 3% over the past 24 hours. High interest rate expectations, rising oil prices, and weakness in tech stocks combined to weigh on the performance of high-volatility risk assets.
Market Movers
Meta (META) fell over 2% in pre-market trading. The company unveiled Meta Charm at the Meta Connect event, a small portable device featuring the Muse AI assistant, an approximately 2-inch touchscreen, and 5G connectivity, which is scheduled to go on sale before the end of the year. Although the new product further expands Meta's AI hardware footprint, the company's stock had accumulated a gain of nearly 12% earlier this week, leading to pre-market profit-taking combined with rising U.S. Treasury yields. Reuters
AI chip stocks broadly fell in pre-market trading. Nvidia (NVDA) dropped about 1%, AMD (AMD) fell about 2%, and Intel (INTC) and Marvell Technology (MRVL) both slipped nearly 3%. As the 10-year U.S. Treasury yield broke above 5%, market bets on a continued rate hike in October rose significantly, putting valuation pressure on high-valuation AI and semiconductor stocks.
Memory storage stocks moved lower across the board in pre-market trading. Micron Technology (MU) fell about 2.3%, SanDisk (SNDK) dropped about 2.7%, while Western Digital (WDC) and Seagate Technology (STX) both slipped over 2%. After significant earlier gains in the sector, capital engaged in short-term profit-taking amid hawkish rate expectations and a broader pullback in tech stocks.
MGM Resorts International (MGM) plunged nearly 9% in pre-market trading. The buyer group under Barry Diller withdrew its privatization acquisition proposal submitted in June, and the MGM board subsequently stated that the company will continue to operate independently. Fading expectations of an acquisition premium were the main reason for the pre-market drop in the stock price.
Market News
The U.S. and China have agreed to extend their trade truce. U.S. Treasury Secretary Scott Bessent stated that both sides agreed to extend the trade truce, originally set to expire on November 10, by two months to January 10, 2027. Trump and Xi Jinping will hold a closed-door meeting at the White House today, covering topics including tariffs, chip export restrictions, artificial intelligence, Taiwan, and the situation in Iran.
New York Fed President John Williams stated that another rate hike may still be needed this year. He said that to further reduce inflation risks, market expectations of another Fed rate hike before year-end are a "reasonable way of thinking," but the final decision will still depend on upcoming economic data.
Significant differences remain in negotiations between the U.S. and Iran. Iran is evaluating the U.S. response to its peace proposal and demanding an end to the naval blockade on Iranian ports; an Iranian security official stated that the Strait of Hormuz will not reopen until relevant conditions are met.
The White House denied that it is drafting a 90-day diesel export ban. Previous reports that the U.S. might restrict diesel exports triggered energy market volatility. White House officials denied such plans, and U.S. Energy Secretary Chris Wright also stated that an export ban cannot effectively address high energy prices.
Important Data/Events Preview
At 8:30 AM ET on September 24, the U.S. releases initial jobless claims data.
At 8:50 AM ET on September 24, Cleveland Fed President Beth Hammack delivers a speech.
At 10:00 AM ET on September 24, the U.S. releases August new home sales data.
At 10:10 AM ET on September 24, Philadelphia Fed President Anna Paulson delivers a speech.
At 11:30 AM ET on September 24, Donald Trump and Xi Jinping hold a bilateral meeting.
After U.S. market close, Costco (COST) reports fourth-quarter fiscal results, with the market expecting EPS of around $6.53 and revenue of around $94.9 billion.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.