


Finally put numbers to guidance — why isn't AMAT moving?


Applied Materials (AMAT) released Q4 FY2026 results after the U.S. market close on Nov 13 (Beijing time), for the quarter ended Oct 2026. Key takeaways below.
Headline numbers were solid, and$Applied Materials(AMAT.US) provided explicit growth guidance for 2026–2027 post-earnings. Management’s clarity was the main surprise.
Long-term guide raised: 2026 calendar-year equipment growth upgraded to '>40%' (from '>30%'). WFE expected to grow >30% in 2027, with AMAT to outgrow the market (>30%).
With 2026 largely in the bag, the 2027 outlook matters more. AMAT’s '>30%' WFE growth call is not aggressive, as Street expectations are broadly 30–40%. Still, putting a number on it signals confidence, and shares ticked up slightly after-hours.
1) Core metrics: Q4 revenue $10.41bn (+53% YoY), modestly above consensus ($10.27bn). Growth was driven by AI compute infrastructure.
Revenue rose 14% QoQ, led by DRAM. After delivery mismatches last quarter (+6% QoQ), DRAM equipment revenue jumped >40% QoQ this quarter, showing clear acceleration.
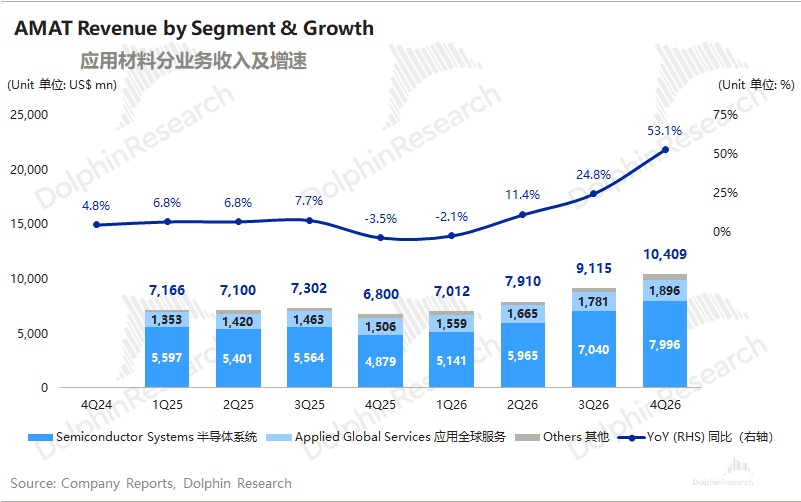
GAAP GPM was 50.4%, essentially flat QoQ and slightly below consensus (50.6%). Management attributed the sustained YoY margin expansion to mix optimization and pricing.
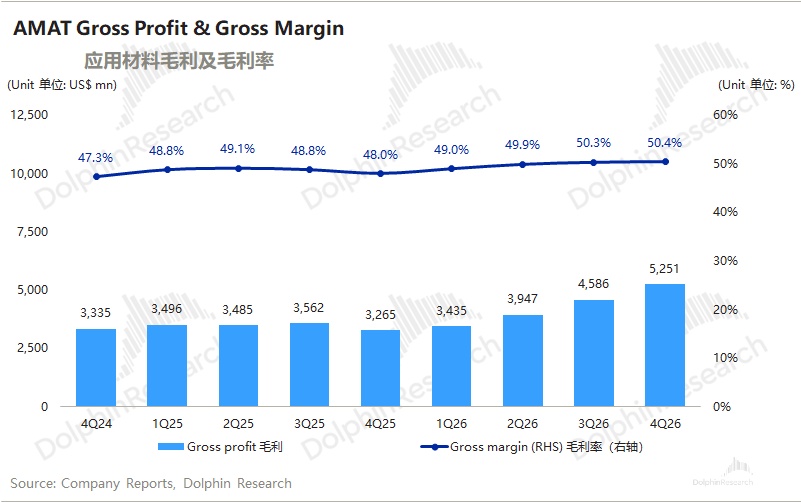
2) Biz detail: AMAT’s revenue mainly comprises semi equipment and services, with semi equipment contributing over 70%. Equipment remains the core driver.
a) Semi equipment revenue was $8.0bn, +14% QoQ, in line with consensus ($7.94bn). Momentum continued across key nodes.
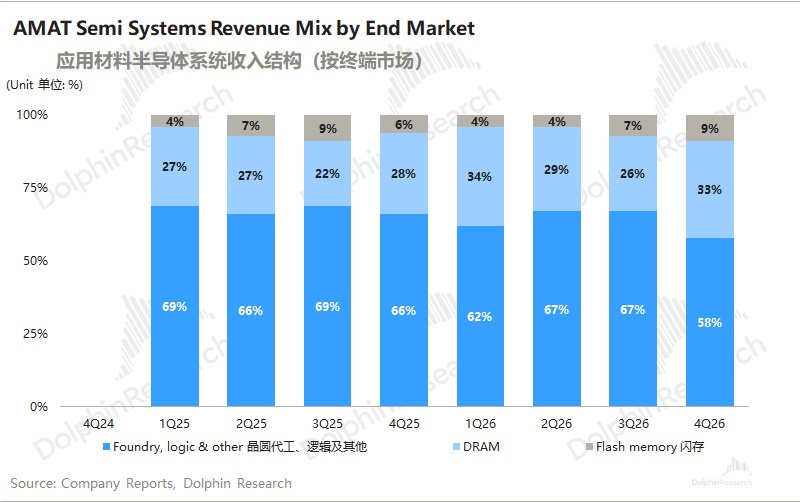
Within semi equipment (based on disclosed mix estimates): ① DRAM revenue was ~$2.64bn, +44% QoQ, well above consensus ($2.34bn). Delivery mismatches tied to cleanroom readiness last quarter have eased, and management said DRAM strength tracked prior expectations.
② Logic revenue was ~$4.64bn, -2% QoQ, below consensus ($5.15bn). Management stressed that advanced logic, like DRAM, remains capacity-constrained, with customers pushing hard on expansion; next quarter’s revenue mix should look similar to this quarter.
③ NAND revenue was ~$0.72bn, +46% QoQ and up ~1.5x YoY. Storage (DRAM + NAND) mix in equipment rose to 42%, while deposition (PVD/CVD/ALD/epi), etch, CMP and process control all hit record highs.
b) Services (AGS) revenue was $1.90bn, +6% QoQ, beating consensus ($1.85bn). Both services and spares (maintenance/upgrades) set new highs.
By region, semi equipment sales in Korea and Taiwan reached record highs. Revenue in Korea and Taiwan was $1.81bn and $2.92bn, respectively, with combined mix rising to 45%.
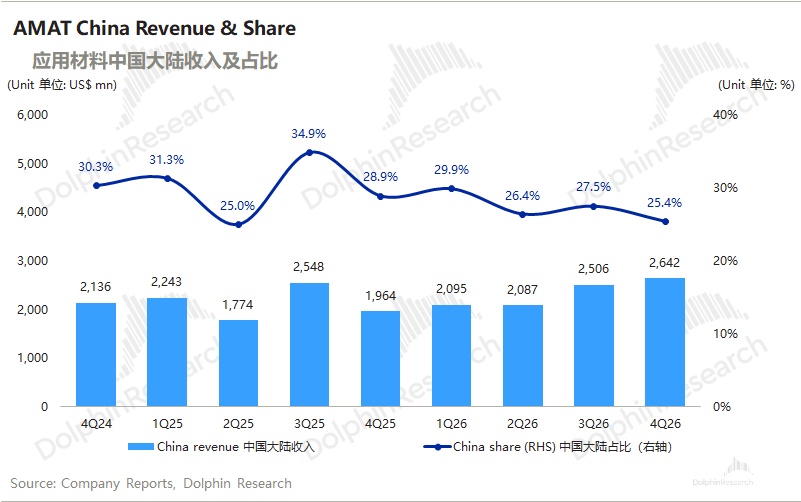
China revenue was $2.64bn, +5% QoQ, with mix down to 25.4%. Management expects China revenue to grow in FY2027 but trail AI-driven segments, with mix falling below 25%.
3) OpEx: Operating expenses rose to $1.59bn. With revenue growing faster than expenses, OpEx ratio fell to 15.3%.
Headcount reached 41.5k, up ~7% QoQ. After announcing a 4% workforce reduction in late Oct 2025, the company has aggressively hired semi engineers, manufacturing and service staff for two consecutive quarters as customers accelerate capacity adds. Management aims to leverage AI and automation to scale while keeping support functions roughly flat.
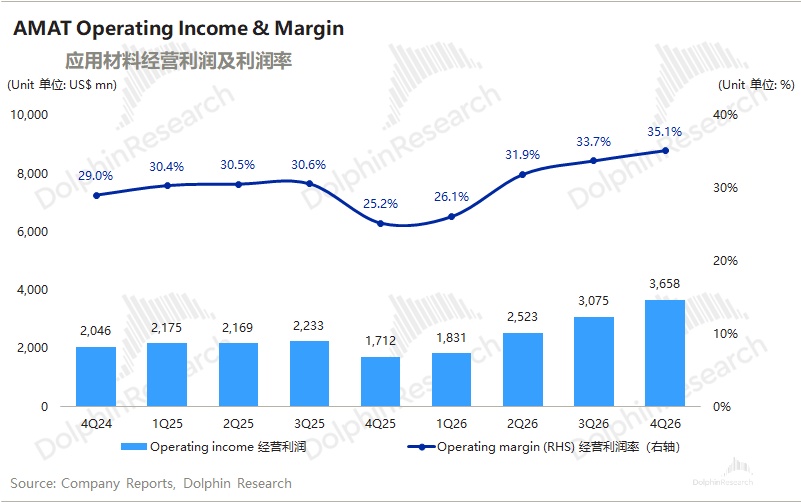
Operating profit was $3.66bn with OPM at 35.3%, up 130bps QoQ. Growth was driven by rapid revenue expansion and lower OpEx ratio.
4) Next-quarter guide: AMAT guides Q1 FY2027 revenue of $10.6–11.6bn (midpoint +6.6% QoQ), slightly above consensus ($10.87bn). Non-GAAP EPS is guided at $4.15–4.55, also slightly above the Street midpoint ($4.26).
By segment, semi equipment around $8.7bn (vs. $8.50bn consensus), services around $2.0bn, and other around $0.4bn; non-GAAP GPM around 50.8% (vs. 50.6% consensus). Note the quarter includes 14 weeks.
On a 13-week comparable basis, midpoint revenue is ~$10.3bn, ~-1% QoQ. Semi equipment would be ~$8.1bn, ~+1% QoQ. Management attributed the slower growth to supply bottlenecks in certain components.
Dolphin Research view: Near-term moderation doesn’t derail a big year; management sounds more confident. Q4 prints were solid, and next-quarter revenue and EPS guides met or slightly beat the Street.
Growth remains AI-capex driven, with this quarter led by a DRAM delivery catch-up. Management finally put numbers on mid-to-long-term growth: 40% equipment growth in 2026 and >30% WFE growth in 2027, with AMAT to outgrow, while ramping capacity to materially lift shipments.
The largest customers continue to provide rolling forecasts and place orders early. No customers have requested shipment delays, and downstream pull remains strong.
Near-term, growth is indeed slowing: excluding the extra week, equipment revenue is roughly flat QoQ, constrained by cleanroom readiness and supply chain. If the largest logic segment declines QoQ, storage will need to grow faster to offset.
Beyond this quarter’s prints, the market is focused on several moving parts:
a) Fab capex: AI demand keeps pushing capex higher, and 2027 should remain a big year for semi equipment. Dolphin Research’s tracker suggests global core fabs’ capex at ~$209.2bn in 2026 (+~46% YoY), rising further to ~$289.5bn in 2027 (+~38% YoY).
Management’s '>30%' WFE growth view for 2027 leaves room, as the Street is already at 30–40%. In 2026, AMAT started with '>20%' equipment growth, raised to '>30%' in May, and is ending '>40%+'.
Ultimately, industry growth depends on the broader semi supply chain. From cleanroom buildouts to parts and materials, cleanrooms remain the key bottleneck.
b) Memory demand and order visibility: DRAM was affected by cleanroom timing last quarter; this quarter DRAM revenue was ~$2.64bn, +44% QoQ, with mismatches easing. Prior debates in Sept–Oct over HBM spec downgrades weighed on equipment stocks.
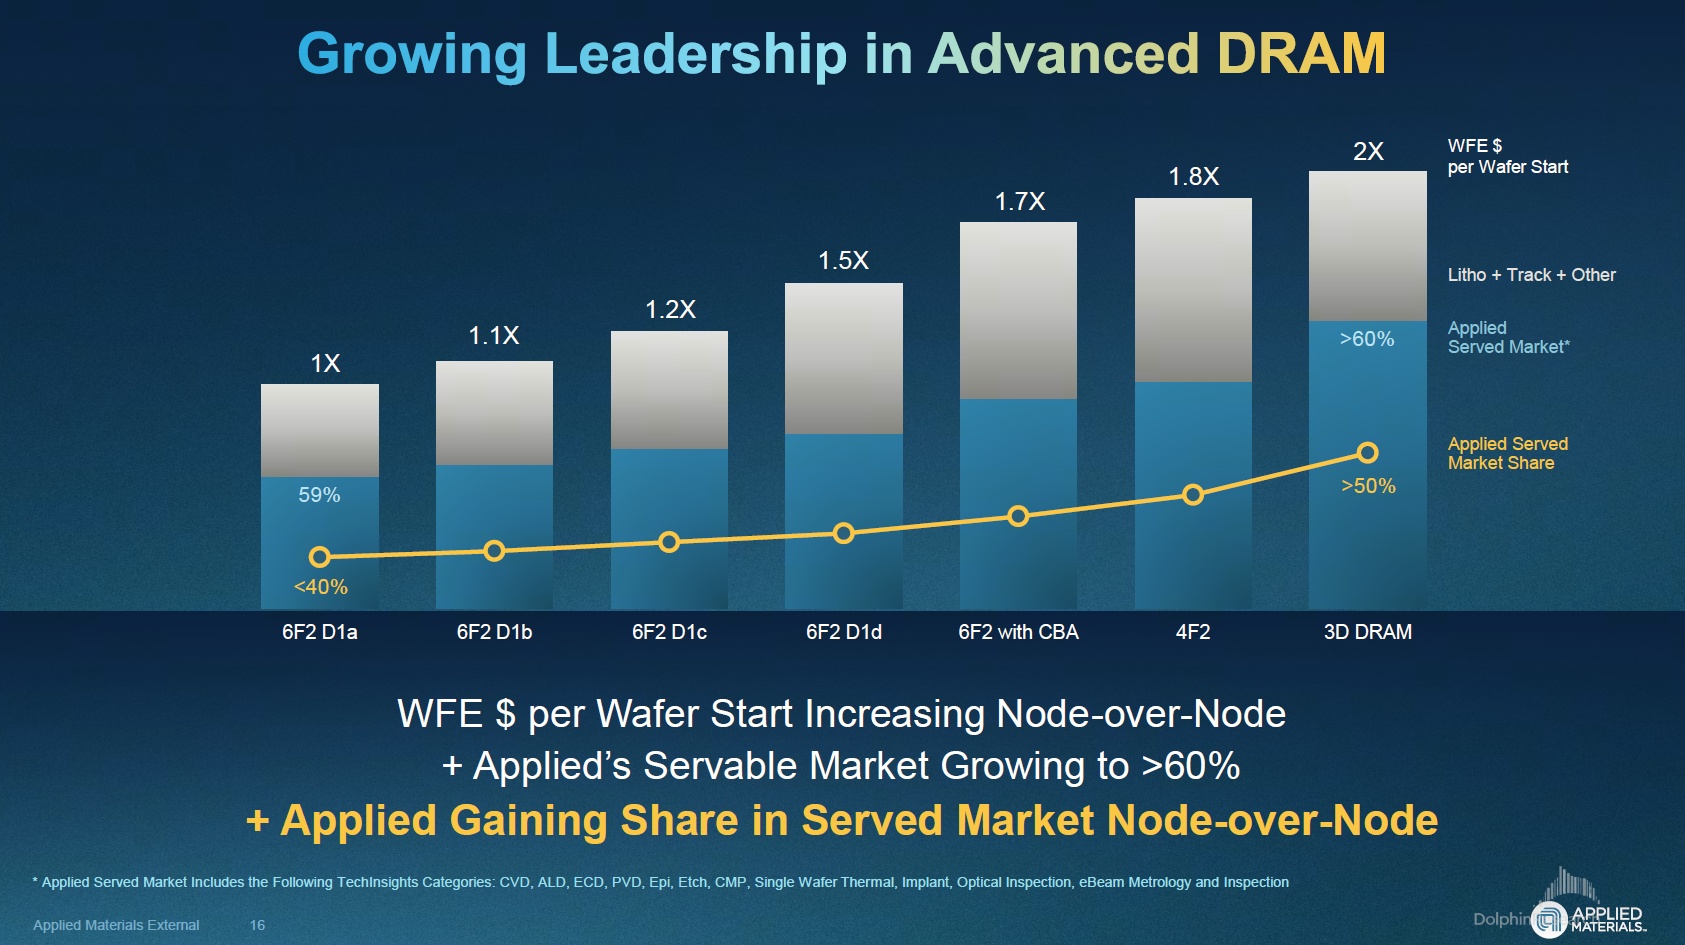
On the call, management remained constructive on memory. AMAT continues to gain share at the next-gen 6F² node, and entering 4F² and 3D DRAM should expand the equipment TAM per unit capacity and raise AMAT’s share.
c) Long-term targets and margins: AMAT’s 2030 targets include raising WFE share (from ~18.3% in 2025) by >200bps, lifting services revenue per tool by >20%, and improving margins by 500bps (GPM) and 1000bps (OPM), implying non-GAAP GPM ~54% and OPM ~40%, with services >$12bn.
The CFO noted that hiring and training costs from capacity ramp are being offset by higher shipments and pricing on new products. The cadence of GPM improvement can be inferred from this quarter and next, at ~20bps per quarter.
At that pace, ~80bps per year is slightly below the ~100bps per year needed to reach 54% by 2030. Further improvement hinges on scaling high-value new products and raising services margins.
AMAT’s current mkt cap of ~$302.3bn implies ~20x PE on FY2027 post-tax core OP (assuming 2-year revenue CAGR ~32%, GPM 51%, tax rate 12%). Historically, AMAT’s PE has mostly ranged 18–30x, placing today near the lower half of the range.
AMAT, ASML, and Lam Research are all upstream semi equipment plays and move with the semi cycle/fab capex. AMAT’s current multiple (~20x PE) is slightly below ASML (~24x) and Lam Research (~23x).
For semi equipment investing, focus on the certainty of fab expansions and high growth over the next 2–3 years. As long as AI capex/the semi cycle stays strong, incremental capex upgrades should continue to drive equipment names’ earnings and multiples higher.
Post-earnings, the stock only ticked up modestly after-hours, suggesting a muted reaction. Dolphin Research sees three reasons: ① the numbers are more 'confirmation' than 'raise', with the Street already >30% for 2027 calendar-year equipment growth; ② on a 13-week basis, revenue is roughly flat QoQ, and component/cleanroom bottlenecks temper near-term growth; ③ GPM improving by ~20bps per quarter is still a slow cadence.
Overall, the semi upcycle remains intact, supported by rising AI capex. Results and guidance met expectations, DRAM rebounded, and management finally offered quantified targets: '>40%' equipment growth in 2026 and '>30%' WFE growth in 2027, while preparing to double capacity by 2028. This is materially more confident than last quarter’s reluctance to quantify.
Semi equipment stocks sold off together earlier on industry beta. After the pullback, most equipment names now trade below mid-range multiples.
AMAT’s prints show demand remains robust and the trend intact. The basket’s high growth in 2027 still looks relatively certain.
Dolphin Research archive on AMAT:
Aug 14, 2026 call recap 'Applied Materials (Trans): 2030 target to lift WFE share by 2%, GPM to 54%'
Aug 14, 2026 earnings take 'Windfall Ahead, Did AMAT Flinch?'
May 15, 2026 call recap 'AMAT (Trans): Semi equipment to grow >30% YoY for the year; margins on a steady uptrend'
May 15, 2026 earnings take 'Capex Surge Underway — Can AMAT Capture the Windfall?'
Feb 13, 2026 call recap 'AMAT (Trans): Semi equipment >20% YoY growth; strength through 2027'
Feb 13, 2026 earnings take 'AMAT: Capex Supercycle Arrives — Spring for Equipment Stocks!'
Dec 10, 2025 deep dive 'Memory on Fire — Can AI Capex Finally Lift AMAT?'
Nov 10, 2025 call recap 'AMAT (Trans): Flat 1H Next Year; Growth Concentrated in 2H'
Nov 10, 2025 earnings take 'Memory Running Hot — Can AMAT Keep Benefiting?'
Sep 18, 2025 deep dive 'AMAT: Everything AI Is Up — When Does the AI Capex 'All-in-One' Arrive?'
Risk disclosure and disclaimer: Dolphin Research Disclaimer and General Disclosure
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.