


Arm Holdings PLC Stock (ARM) Moved Down by 11.60% on Oct 30: Facts Behind the Movement


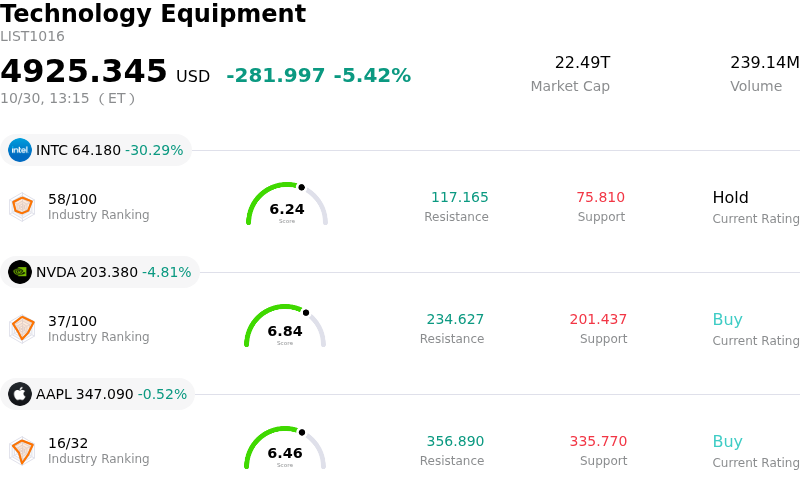
Arm Holdings PLC (ARM) moved down by 11.60%. The Technology Equipment sector is down by 5.42%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Intel Corp (INTC) down 30.32%; NVIDIA Corp (NVDA) down 4.81%; Apple Inc (AAPL) down 0.52%.
What is driving Arm Holdings PLC (ARM)’s stock price down today?
Arm Holdings experienced significant downward pressure as a broader sell-off across high-beta technology and semiconductor equities weighed on growth-oriented names. Persistent macroeconomic concerns, including shifting interest rate expectations and elevated Treasury yields, have led investors to recalibrate discount rates applied to high-multiple tech leaders. Given that a substantial portion of the company's market valuation is anchored in future earnings projections tied to next-generation artificial intelligence and computing architectures, the stock remains particularly sensitive to macro headwinds and broader risk-off sentiment across the technology sector.
Adding to the sell-off is ongoing legal uncertainty surrounding the high-profile licensing dispute with Qualcomm. A federal jury in Delaware recently delivered a verdict finding that Arm breached specific licensing provisions regarding developer tools. Market participants remain focused on pending judicial rulings regarding contractual enforcement, particularly whether Qualcomm could challenge or temporarily halt royalty payments. Because licensing and royalty revenues from major tier-one hardware partners constitute a critical component of Arm's profitability, any potential disruption to contractual revenue streams or prolonged legal wrangling presents a clear structural overhang for institutional investors.
Furthermore, the retreat reflects profit-taking and strategic portfolio adjustments by institutional funds ahead of the company's scheduled fiscal quarterly earnings report. Trading at a rich forward valuation multiple relative to semiconductor industry peers, the stock leaves little margin for error regarding financial guidance or operational metrics. Concerns regarding the cadence of hyperscaler AI spending and mixed global smartphone demand have prompted traders to reduce high-multiple exposure. Until greater clarity is provided on litigation outcomes and cloud compute royalty growth, elevated intraday volatility is expected to characterize trading activity.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of -4.008, indicating a sell signal. The RSI at 34.040 suggests neutral condition and the Williams %R at 99.396 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
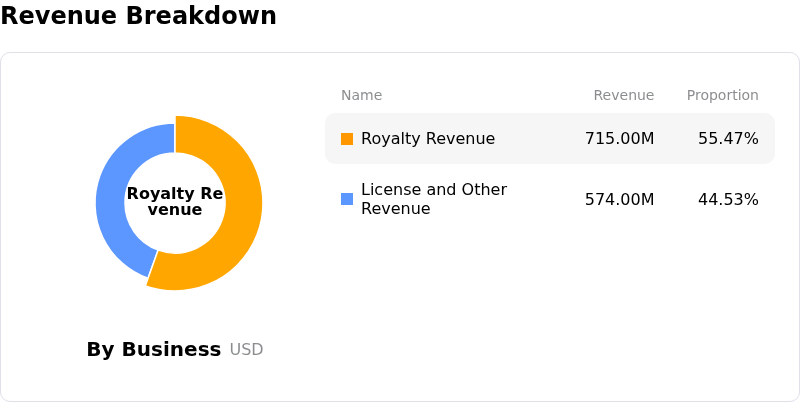
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $286.95, a high of $480.00, and a low of $125.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Legal and Licensing Dispute Vulnerability: Adverse legal developments in ongoing litigation with Qualcomm over architectural licenses and chip-testing tools threaten billions of dollars in prospective royalty revenues, undermining market confidence in Arm's core intellectual property licensing framework.
- Extreme Valuation Premium: Trading at an elevated forward earnings multiple near 100x and trailing P/E over 200x—significantly above direct semiconductor peers—leaves the stock highly exposed to sharp intraday sell-offs on any minor operational hiccup or macro pullback.
- Semiconductor Fab Capacity Constraints: Supply chain bottlenecks and third-party semiconductor fabrication capacity limits threaten to cap near-term revenue growth, delaying the volume ramp-up for next-generation AGI CPUs and data center hardware.
- Margin Compression and R&D Expense Escalation: Institutional analyst concerns regarding rising operational expenditures and cost pressures—driven by Arm's expansion into custom silicon and complex AI compute designs—risk compressing operating margins despite steady top-line growth.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.