


Dell Technologies Inc Stock (DELL) Moved Down by 11.07% on Oct 30: What Investors Need To Know


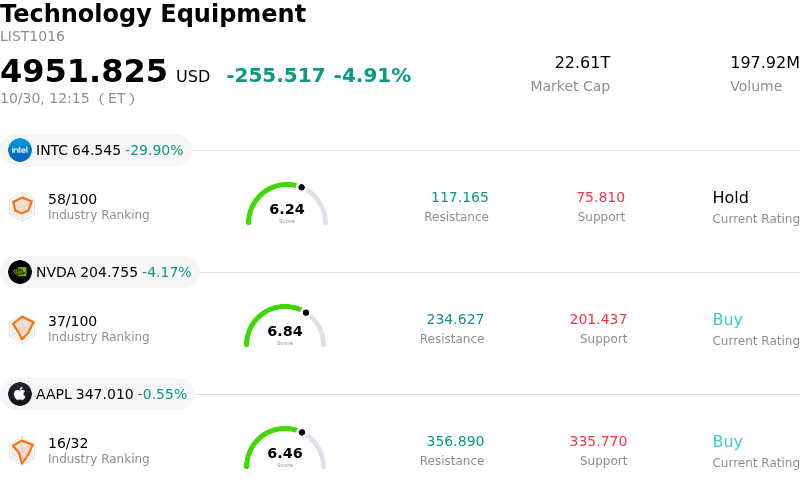
Dell Technologies Inc (DELL) moved down by 11.07%. The Technology Equipment sector is down by 4.91%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Intel Corp (INTC) down 29.90%; NVIDIA Corp (NVDA) down 4.09%; Apple Inc (AAPL) down 0.59%.
What is driving Dell Technologies Inc (DELL)’s stock price down today?
Dell Technologies experienced sharp selling pressure as a convergence of adverse industry read-throughs and tech sector headwinds weighed on hardware sentiment. The primary catalyst driving the downturn was cautionary commentary from key chipmaker Intel, which warned of an accelerating contraction in personal computer demand. Intel cited rising memory chip costs and supply bottlenecks as major factors causing original equipment manufacturers to aggressively reduce inventory levels and postpone hardware purchases. Given that Dell retains significant exposure to commercial and consumer PC markets through its Client Solutions Group, investors quickly repriced the company's near-term device shipment trajectory.
The negative read-through was further exacerbated by broader technology market volatility and disappointing earnings metrics from major cloud and semiconductor peers. Market participants have grown increasingly sensitive to enterprise capital expenditure efficiency and hardware deployment schedules. Independent industry data confirming sharp year-over-year declines in global PC shipments reinforced fears that component cost inflation will constrain unit volume growth and compress near-term operating margins across client hardware divisions.
These sector-wide challenges intersect with lingering investor skepticism regarding component price pass-through versus underlying enterprise demand. Earlier Wall Street analyst updates highlighted that a portion of recent server revenue expansion was driven by passing along higher memory component costs rather than pure unit volume acceleration. While Dell's artificial intelligence server backlog and enterprise data center pipeline remain substantial, concerns surrounding free cash flow conversion and client segment cyclicality have prompted institutional investors to trim exposure ahead of the company's upcoming quarterly financial report.
In summary, the sharp intraday retreat reflects risk reduction driven by bleak PC industry guidance from key supply chain partners and broader tech sector margin friction. Until memory component pricing stabilizes and clarity emerges regarding client device replacement cycles and free cash generation, computer hardware manufacturers are likely to navigate heightened valuation scrutiny.
Technical Analysis of Dell Technologies Inc (DELL)
Technically, Dell Technologies Inc (DELL) shows a MACD (12,26,9) value of -11.352, indicating a sell signal. The RSI at 35.542 suggests neutral condition and the Williams %R at 94.534 suggests oversold condition. Please monitor closely.
Media Coverage of Dell Technologies Inc (DELL)
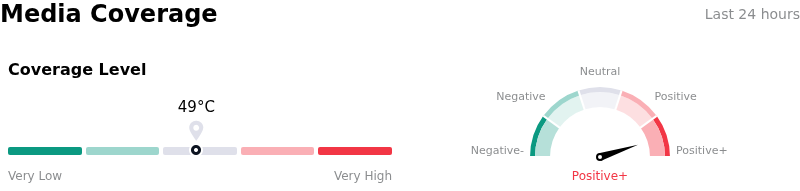
In terms of media coverage, Dell Technologies Inc (DELL) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Dell Technologies Inc (DELL)
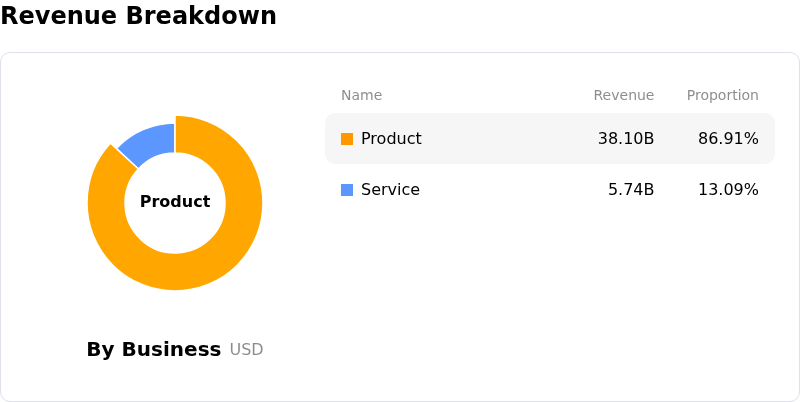
Dell Technologies Inc (DELL) is in the Technology Equipment industry. Its latest annual revenue is $113.54B, ranking 2 in the industry. The net profit is $5.94B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $587.28, a high of $700.00, and a low of $499.80.
More details about Dell Technologies Inc (DELL)
Company Specific Risks:
- PC Hardware Demand Contraction: Intraday stock pressure was triggered by supplier Intel's public warning of an accelerated PC market downturn, forecasting global PC shipments to drop 12% this year and another 10% next year, directly threatening Dell's core Client Solutions Group revenues.
- Component Cost Inflation and Margin Compression: Wall Street analysts highlight that surging memory chip prices and supply chain frictions are squeezing hardware gross margins, causing enterprise server revenue growth to reflect higher component pass-through costs rather than pure volume expansion while suppressing free cash flow generation.
- Insider Equity Liquidations and Management Turnover: Market sentiment is weighed down by persistent insider share sales near historic valuation highs alongside an SEC Form 8-K filing confirming executive management turnover, including the planned retirement of the company's Executive Vice President and General Counsel.
- Neocloud Counterparty Credit Exposure: Rapid growth in AI server orders relies heavily on debt-financed neocloud providers and internal customer financing via Dell Financial Services, increasing counterparty credit risk and potentially delaying the conversion of Dell's record server backlog into realized cash flow.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.