


Qualcomm Q4 Earnings Preview: Can Automotive and Data Centers Fill the Smartphone Gap? Wall Street's Highest Target at $270



AI Podcast


Qualcomm will report its fourth-quarter and full-year fiscal 2026 results after the U.S. market close on November 4, Eastern Time. The market expects revenue of $10.1 billion to $10.15 billion and adjusted EPS of $2.16 to $2.17. While the automotive and IoT sectors exhibit strong growth, overall performance faces pressure from weak smartphone demand, rising production costs, and declining Apple orders. Conversely, the patent licensing business continues to provide stable high-margin support. Wall Street maintains a consensus hold rating with an average 12-month price target of $196.82.

TradingKey - Qualcomm (QCOM) will report its fourth-quarter and full-year fiscal 2026 results after the U.S. stock market close on November 4, Eastern Time, and hold a conference call at 4:45 p.m. on the same day.
The market expects Qualcomm's fourth-quarter revenue to be approximately $10.1 billion to $10.15 billion and adjusted earnings per share to be around $2.16 to $2.17. The company previously issued revenue guidance of $9.7 billion to $10.5 billion and adjusted EPS guidance of $2.05 to $2.25, placing market expectations roughly near the midpoint of the guidance range.
Compared with the same period last year, revenue for the quarter is expected to decline by about 10%, while adjusted EPS could fall by nearly 28%. Although the automotive, IoT, and data center businesses continue to expand, weak demand for smartphone chips, reduced orders from Apple, and rising production costs continue to weigh on overall performance.
Weak Smartphone Demand and Loss of Apple Orders Increase Revenue Pressure
In the previous quarter, Qualcomm reported revenue of $9.95 billion and adjusted earnings per share of $2.21. Revenue from its chip business stood at approximately $8.5 billion, of which handset chip revenue reached $5.1 billion, still accounting for about 60% of the chip segment's revenue.
This means that even if the automotive business maintains near-60% growth, a significant drop in handset revenue would make it difficult for the new business to fully offset the shortfall in the short term. The automotive business is currently less than one-third the size of the handset business, limiting the impact of its high growth on overall group revenue due to the base effect.
Rising memory chip prices have introduced further uncertainty. Tight DRAM and NAND supplies have driven up smartphone production costs and may prompt handset makers to trim shipment plans. Qualcomm is attempting to pass on wafer, packaging, testing, and memory costs by raising product prices; however, price adjustments typically take effect gradually alongside contract renewals and new product launches, meaning their full impact may not be realized for several quarters.
The Apple business presents a more explicit drag. Qualcomm expects Apple-related product revenue to drop by about 50% sequentially from the third to fourth quarter of fiscal 2026, while its previous forecast for holding around a 20% share of next-generation iPhone modems will also need to be revised downward. As Apple continues to advance its in-house modem development, Qualcomm's future revenue from this client may decline further.
Bernstein estimates Qualcomm's Apple-related chip revenue in fiscal 2026 at roughly $7.5 billion to $8 billion, which could drop by about $6 billion in fiscal 2027. Consequently, the firm lowered its fiscal 2027 revenue forecast for Qualcomm from $44.9 billion to $42.2 billion and its adjusted EPS projection from $9.57 to $8.77, both below prior market consensus.
Automotive Business Sees Rapid Growth as Data Center Enters Monetization Phase
Facing uncertainty in its smartphone business, Qualcomm is accelerating its expansion into sectors such as automotive, IoT, and data centers. In the third quarter of fiscal 2026, automotive revenue reached approximately $1.6 billion, up 61% year-over-year to hit an all-time high, while IoT revenue reached around $1.8 billion, a 9% year-over-year increase. Together, the two segments totaled about $3.4 billion, accounting for 40% of overall chip business revenue.
Annualized based on this quarterly scale, Qualcomm's non-smartphone chip revenue stands at approximately $13.6 billion. The company previously raised its fiscal 2029 non-smartphone revenue target to $40 billion, nearly triple its current scale. Reaching this target in about three years implies a compound annual growth rate of approximately 43%, meaning automotive, IoT, and data centers must all sustain rapid expansion simultaneously.
Among these, the automotive business currently has a relatively clear revenue foundation. The company expects that by the end of fiscal 2026, annualized automotive revenue could reach approximately $7 billion, above its previous target of $6 billion. However, automotive chips typically require a lengthy cycle from design win to mass production; design wins do not equate to current revenue, and the market still needs to monitor the pace of conversion.
Data centers represent a larger but higher-risk growth avenue, where Qualcomm is advancing custom silicon, AI inference accelerators, and server CPUs. Recently, it also entered into a multi-generational product partnership with Amazon to develop AI infrastructure and high-speed interconnect products for AWS data centers.
Management previously anticipated that revenue from the first batch of custom chips would begin showing up in the December quarter. If the upcoming earnings call provides disclosures on customer deployments, order values, and revenue recognition timelines, it will offer a more direct foundation for evaluating fiscal 2027 growth.
Profit Margins Under Pressure, Wall Street’s Highest Price Target Is $270
The pre-tax profit margin of Qualcomm's chip business is expected to drop from 26% in the previous quarter to 23%-25%. In addition to declining handset revenue, higher initial costs for data center projects may also weigh on overall margins. The company projects that data center investments could reduce the chip business's gross margin by approximately 1.5 to 2 percentage points.
In contrast, the patent licensing business continues to deliver stable profits. In the previous quarter, revenue from Qualcomm's licensing business was approximately $1.3 billion, with a pre-tax profit margin as high as 69%; fourth-quarter revenue guidance is $1.2 billion to $1.4 billion, with margins expected to remain at 68% to 72%. Although this business is smaller in revenue scale, it provides a cushion for group earnings when chip margins come under pressure.
According to TipRanks, 11 Wall Street analysts have covered Qualcomm over the past three months, with an average 12-month price target of $196.82, a high forecast of $270, and a low of $155. The rating breakdown consists of 3 Buys, 6 Holds, and 2 Sells, yielding an overall consensus of "Hold".
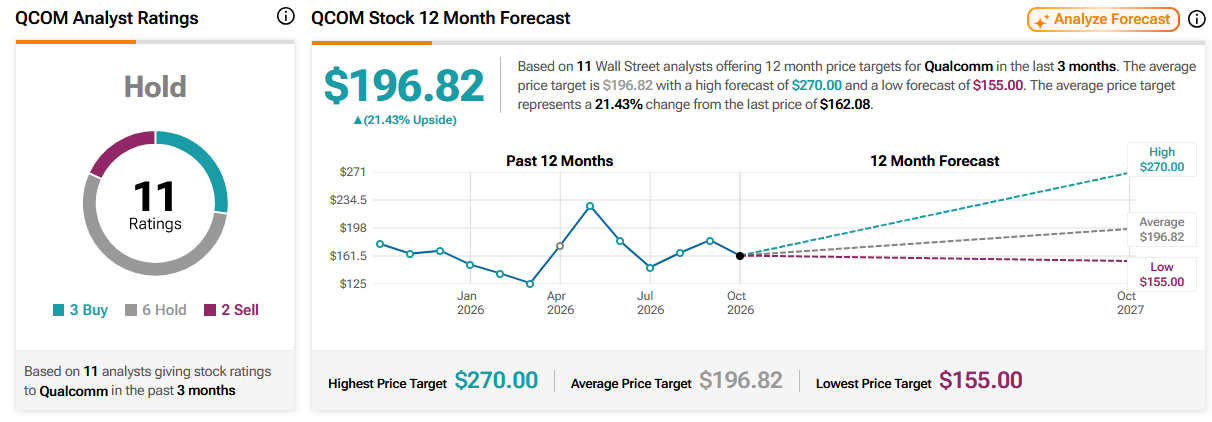
Source: TipRanks
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.