


Samsung Q3 Operating Profit Surges Nearly 8-Fold to Record High: What Is the Outlook for Micron, Nvidia, and Memory Stocks?



Samsung and Micron reported record-breaking earnings driven by surging AI demand and memory chip price hikes, though stock market reactions remain muted as expectations were largely priced in. Conventional DRAM and NAND supply tightness, alongside robust HBM shipments, continue to bolster industry profitability, though rising costs impact mobile and consumer electronics segments. Meanwhile, memory and storage stocks diverge amid concerns over potential HDD capacity expansion for AI data centers. For Nvidia, HBM4 supply availability and procurement costs remain critical factors for the production and delivery schedule of Vera Rubin platforms.
TradingKey - On October 8, Samsung Electronics released its preliminary earnings guidance for the third quarter of 2026: consolidated revenue reached approximately 195 trillion won, up 126.6% year-over-year; operating profit was around 107.4 trillion won, surging 782.5% year-over-year and up about 20% quarter-over-quarter. Both revenue and operating profit hit record quarterly highs, with operating profit beating the LSEG SmartEstimate forecast of 106.1 trillion won by about 1.2%.
As of press time, Samsung Electronics shares fell 0.93% to 266,000 won. The stock's failure to rally indicates that the record performance had largely been priced in by the market.
Samsung and Micron (MU)'s latest financial results show that growing AI demand and rising memory chip prices continue to support industry profitability. Going forward, attention should be paid to how long price increases will persist and whether the release of new capacity will ease supply tightness.
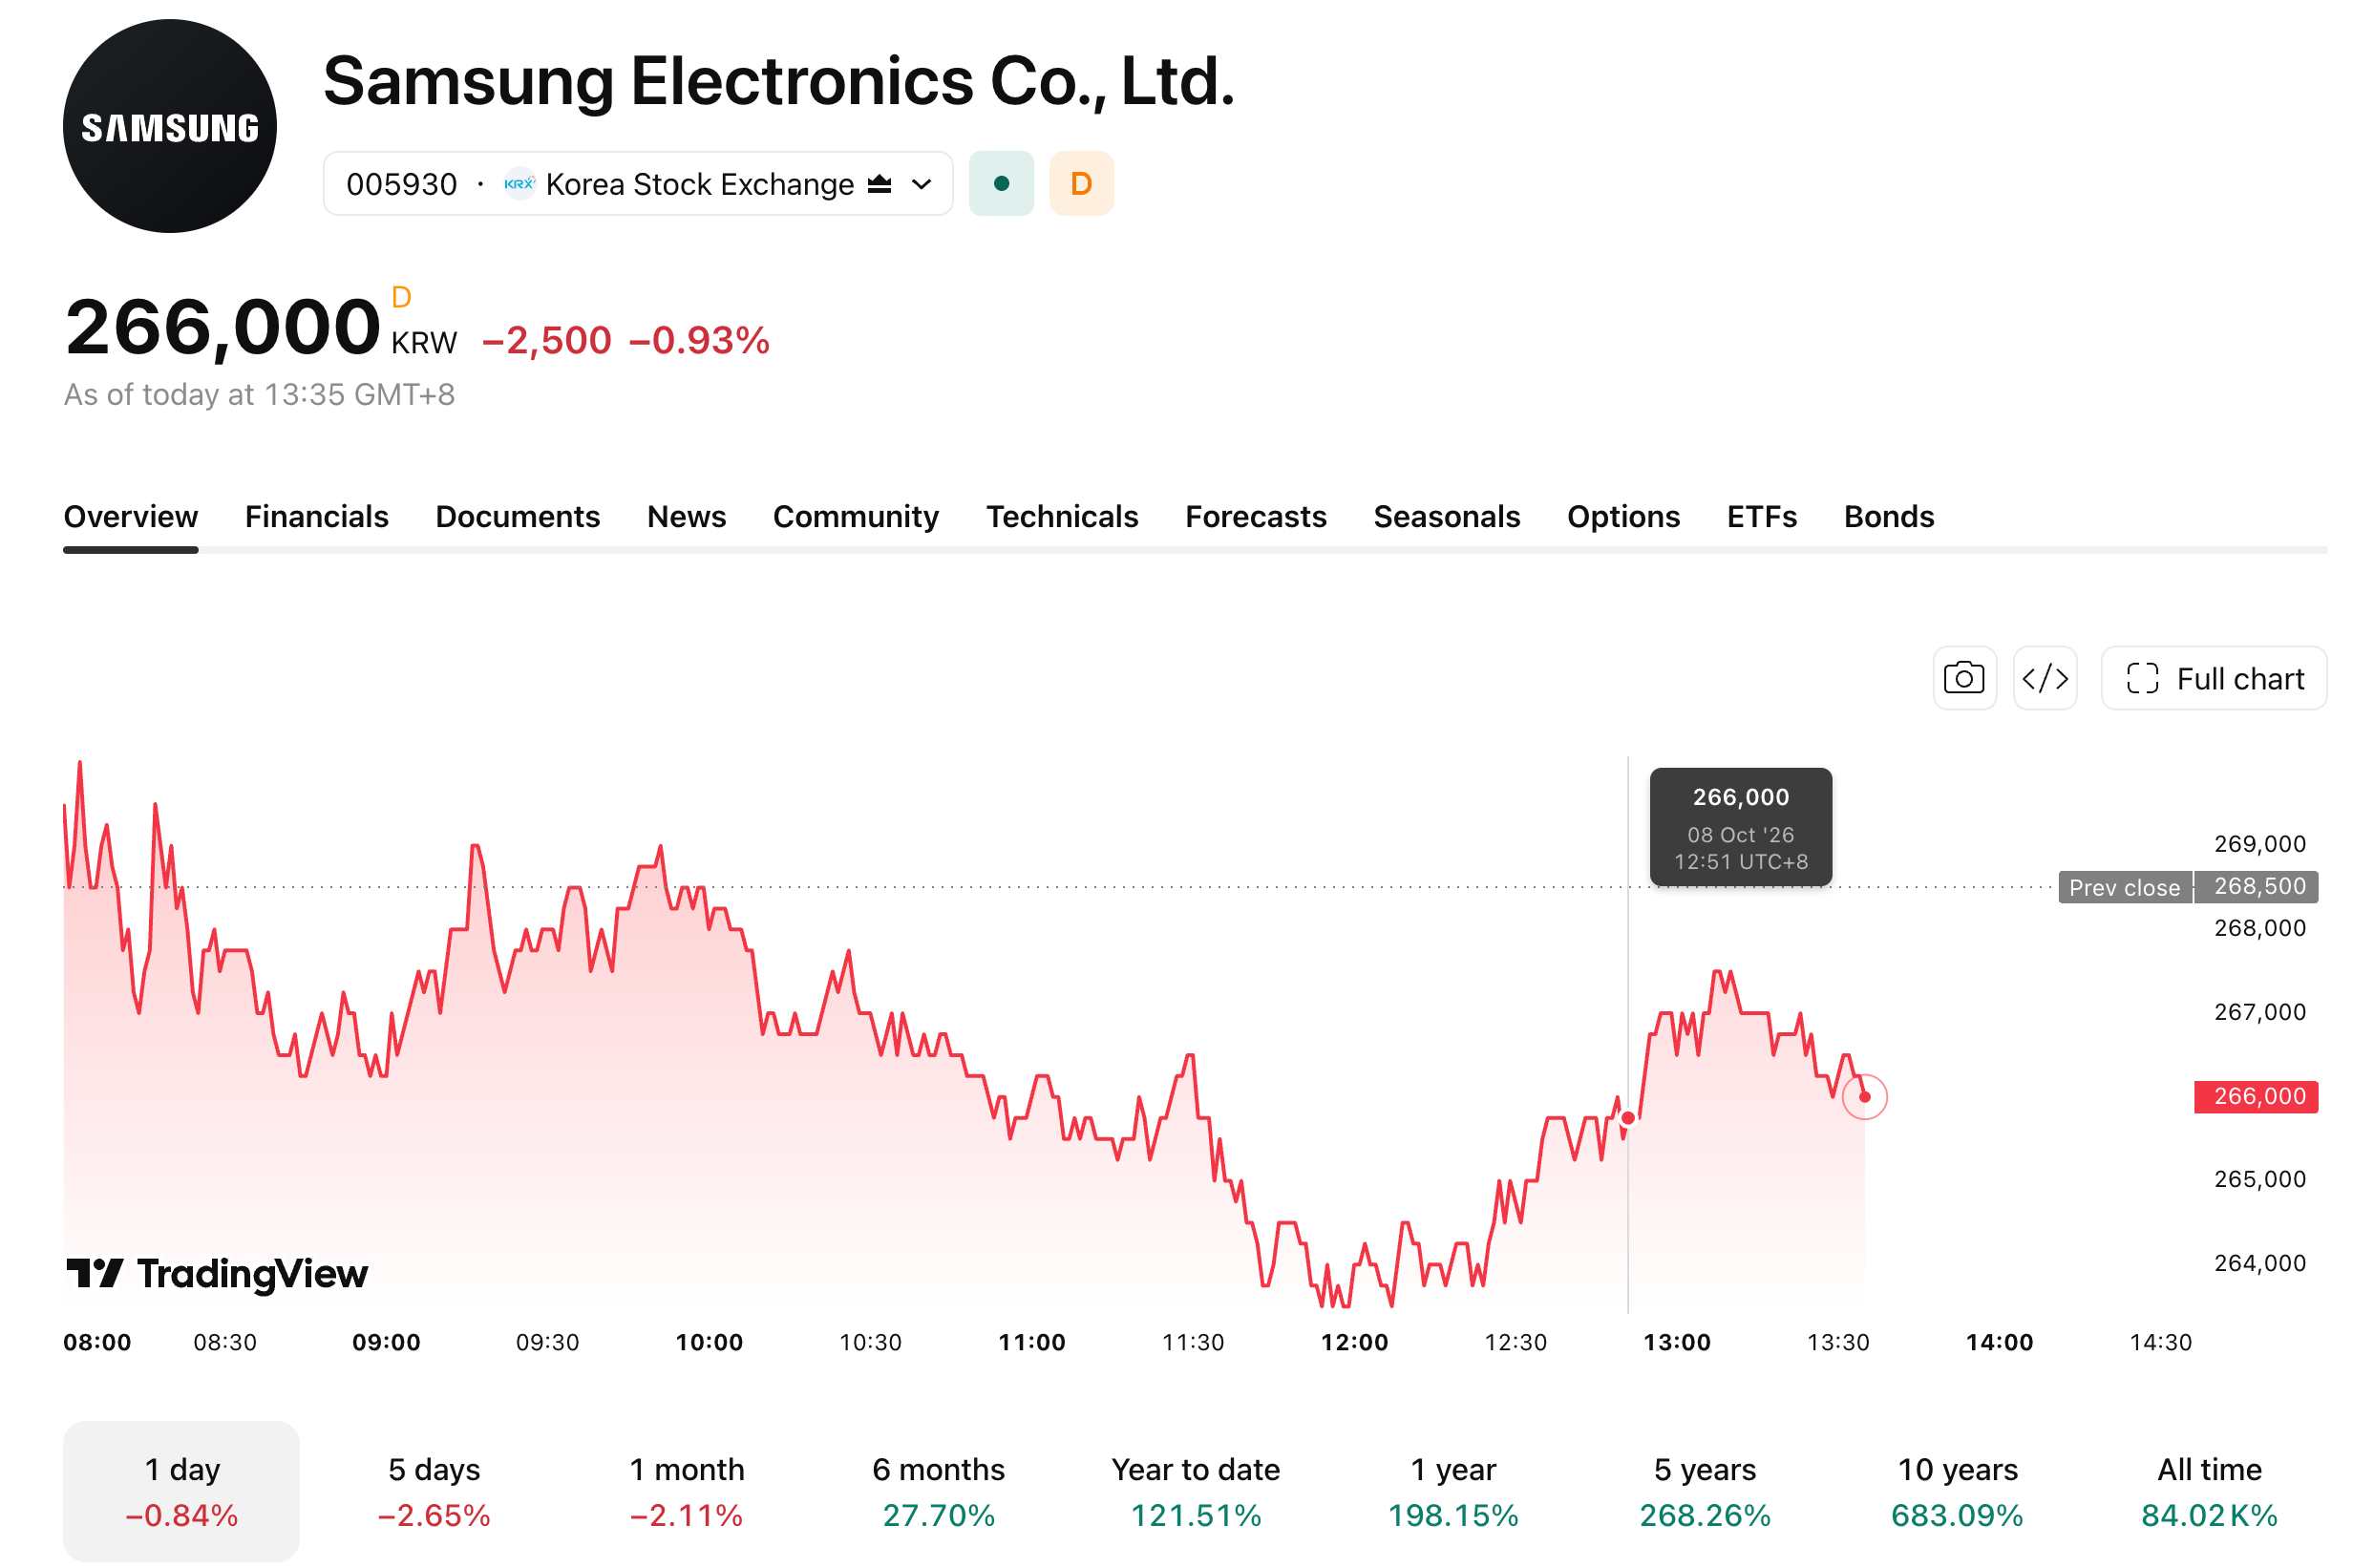
[Source: TradingView]
Samsung Profit Hits Record High: How Long Can Memory Price Hikes Last?
According to Reuters, tight supplies of conventional DRAM and NAND, coupled with rising demand for HBM, are expected to make the memory business the primary source of Samsung's third-quarter profit growth. Douglas Kim, an analyst at Douglas Research Advisory, estimates that Samsung's HBM bit shipments grew by nearly 50% quarter-on-quarter in the third quarter.
Memory price increases are expected to extend into the fourth quarter, but the growth in conventional DRAM prices has moderated. TrendForce projects that fourth-quarter conventional DRAM contract prices will rise 10% to 15% quarter-on-quarter, lower than the roughly 60% surge in the second quarter reported by Reuters; NAND Flash contract prices are expected to rise 15% to 20% sequentially. Future profit growth will still depend on shipments, product mix, and cost dynamics.
Rising memory chip prices have also added cost pressures to Samsung's mobile phone and consumer electronics businesses. Analysts expect the foundry business to remain unprofitable due to low capacity utilization and fixed cost burdens. Samsung plans to release its detailed financial results on October 29, providing further insight into the profit contribution of the memory business, HBM progress, and the performance of other segments.
Micron Earnings Surge: Why Are Memory Stocks Diverging?
On September 30 Eastern Time, Micron reported its fourth-quarter fiscal 2026 financial results, with revenue reaching $54.23 billion, up approximately 379% year-over-year. Non-GAAP diluted earnings per share were $33.42, and the non-GAAP gross margin reached 87%, compared to 45.7% in the same period last year.
The company expects first-quarter fiscal 2027 revenue to range between $60.0 billion and $63.0 billion, with non-GAAP diluted earnings per share between $37.15 and $39.15. The midpoint of the revenue guidance represents sequential growth of approximately 13.4%, while the non-GAAP gross margin is expected to be around 86.25%, down 0.75 percentage points sequentially. Management anticipates that memory supply and demand conditions in 2027 and 2028 will be tighter than in 2026.
However, supply and demand dynamics vary across different memory products. Micron operates primarily in DRAM, HBM, and NAND businesses, while SanDisk (SNDK) mainly operates in NAND flash memory and related products; Western Digital (WDC) and Seagate (STX) focus primarily on hard disk drive businesses, making their earnings prospects more sensitive to changes in HDD supply, demand, and pricing.
According to MarketWatch, citing Nikkei Asia, Toshiba plans to expand hard drive capacity for AI data centers, sparking market concerns that additional supply could weaken hard drive makers' pricing power. On October 2, Western Digital and Seagate both closed down by approximately 10.2%. The actual impact of the capacity expansion on both companies' earnings will still depend on the scale of the new capacity, production timelines, and customer demand growth.
Since then, performance among the related stocks has continued to diverge. On October 7 Eastern Time, Micron and SanDisk closed up 4.06% and 1.92%, respectively, while Western Digital closed down 1.37% and Seagate gained a modest 0.24%. Going forward, attention should be paid to the sustainability of price increases for memory chips, as well as the impact of hard drive capacity expansions on selling prices and profit margins.
How HBM4 Supply and Costs Will Affect Nvidia?
Nvidia (NVDA) Rubin GPUs use HBM4. Micron stated that volume shipments of 36GB, 12-layer HBM4 for the Vera Rubin platform began in the first calendar quarter of 2026. HBM4 supply is a crucial condition for the production and delivery of Rubin systems.
For Nvidia, an increased supply of HBM4 helps meet production demand; however, if procurement prices rise, costs could increase, with the specific impact depending on supply contracts and system sales pricing. Going forward, attention should be paid to whether HBM4 deliveries can match Rubin's production schedule, and whether procurement demand from cloud providers and AI enterprises can continue to grow.
Samsung's preliminary results reflect the support of memory demand and price hikes for earnings. Going forward, memory manufacturers need to monitor selling prices and new supply, while Nvidia needs to focus on key component supply, procurement costs, and system orders.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.