


Qualcomm Stock Forecast: Snapdragon AI Push Puts QCOM Rally in Focus



AI Podcast


Qualcomm is advancing its AI integration across smartphones, PCs, and data centers through recent product launches and strategic partnerships with Amazon and Google. Despite a 4% year-over-year revenue decline to $9.95 billion for the fiscal third quarter ended June 28, 2026, driven by a 20% drop in handset sales, diversification efforts showed strength, notably a 61% increase in automotive revenues. Management projects Q4 revenue between $9.7 billion and $10.5 billion amid rising component costs. Technically, QCOM maintains a bullish short-term setup above the $194.77 support level, eyeing a breakout past $200 toward the $207.44 target.

TradingKey - Qualcomm (NASDAQ: QCOM) takes the spotlight with AI integrations across multiple product segments. The recent product releases and partnerships show AI capabilities across smartphones, PCs, and data centers. With product announcements this week, Qualcomm continues to advance its AI integrations across multiple industries. While product releases are positive catalysts for the company, revenue concerns persist with the handset division.
Snapdragon Summit Strengthens the On-Device AI Story
This week’s Snapdragon Summit provided Qualcomm the opportunity to share its latest and greatest mobile computing platforms. The new offerings, Snapdragon 8 Elite Gen 6 and Snapdragon 8 Elite Extreme Gen 6, further extend Qualcomm’s flagship mobile platform offerings. As with prior mobile platforms from Qualcomm, the new offerings provide improved AI, gaming and camera experiences. Furthermore, Qualcomm highlighted certain Android device manufacturers, including HONOR, Motorola, OnePlus, OPPO, and vivo, that will be using the new mobile platforms.
While the Company can provide forward looking statements regarding potential device launches, Qualcomm historically has been unable to provide forward looking statements regarding how such devices will impact Qualcomm’s competitive position in the market. Ultimately, device launches in the market will provide Qualcomm with an improved competitive positioning.
Googlebook Extends Snapdragon Into AI PCs
A second potential catalyst is Qualcomm’s Snapdragon expansion into the new Googlebook laptop category. The first members of the category, from Dell and HP, have been designed and are available for preorder.
The new platform offers a range of Google applications and intelligence services, referred to as Google Gemini, along with Android applications and Snapdragon NPU-powered AI capabilities.
This provides Qualcomm an opportunity to penetrate the AI PC category beyond Windows PCs.
While this development captures a larger PC category for Qualcomm’s Snapdragon, first party shipments and revenues are yet to be defined, therefore, it is difficult to estimate the near term impact of this partnership on Qualcomm’s revenue.
Amazon Broadens the AI Case Beyond Edge Devices
The Qualcomm/Amazon partnership from September is the most significant partnership for Qualcomm in terms of business expansion.
Through this partnership, Qualcomm gains an opportunity to work with Amazon on customized silicon for AWS AI infrastructure and advanced optical connectivity inside data-center networks.
This integration will span AI inference, customized silicon and high-speed optical interconnects, including solutions up to 1.6T.
With this partnership, Qualcomm’s AI and edge computing services will be integrated into cloud computing. Because the partnership does not ensure an immediate contribution to Qualcomm’s revenues, it will be prudent to evaluate this partnership within a longer timeframe.
Diversification Targets Are Ambitious
Diversification has become important to Qualcomm as the smartphone industry matures and demand for handsets flattens. Qualcomm aims to have $40 billion of revenue from sources other than handsets by 2029. Of this amount, Qualcomm expects data centers to produce more than $15 billion of revenue, the automotive industry $10 billion, and the Internet of Things (IoT) more than $14 billion. Each of these figures represents Qualcomm’s opportunity and is not related to contracts.
There are encouraging signs regarding Qualcomm’s diversification efforts with the company’s recent deals with Amazon and Google, as well as the growth in the automotive market. However, skepticism about the company’s ability to monetize these opportunities has been warranted.
Latest Results Show Why Diversification Matters
Qualcomm’s last reported results were for the fiscal third quarter ended June 28, 2026. Revenues for the quarter were $9.95 billion, down 4% from the prior year. Earnings were $1.87 compared to $2.43 the year prior. Adjusted earnings were $2.21 compared to $2.77.
Revenue from the QCT (Qualcomm Technologies) business unit was $8.50 billion, down 5% from the prior year.
Handset revenues were down 20% to $5.09 billion.
Revenues from other business units were encourging. Automotive revenues were $1.59 billion, up 61% from the prior year and IoT revenues were $1.83 billion, up 9% from the prior year.
As the above results illustrate, Qualcomm needs additional business opportunities, including data centers and other industries, to grow in order to balance the handset revenue decline. Without additional business opportunities and growth, Qualcomm will be reliant on AI to improve the company’s financial results and valuation.
Q4 Guidance Keeps the Near-Term Bar Moderate
Qualcomm has estimated its fourth quarter revenues to be in the range of $9.7 billion to $10.5 billion, with adjusted EPS of $2.05 to $2.25.
The company has noted the increasing costs of wafers, packaging and memory as well as other components in the production process.
While the company expects that adjustment of product prices would help gross margins over time, the company expects near-term cost pressure on product margins.
The best evidence for the longer-term would be maintaining handset volume, while capturing new volume from other areas, such as the premium smart devices, while charging market prices.
Automotive Remains the Best Proven Diversification Engine
As of now, Automotive is the most developed and bankable of Qualcomm’s other Product Areas.
For the Company’s fiscal Q3, Automotive revenue increased 61% to $1.59 billion.
Compared to the huge untapped opportunity in the Data Center Business, Automotive is a more defined and developed Business segment for the Company.
It shows Qualcomm is building a lucrative business outside mobile; in my opinion, the next target should be PC and AI products.
What Would Strengthen the Bull Case
My base case preserves a constructive outlook on Qualcomm's long-term strategy while treading water on the short-term outlook.
I would look more favorably on Qualcomm if handset revenue expanded, particularly with the recent launch of new premium Snapdragon devices, and if the company continued to report strong growth with its automotive products. Positive surprises with the company’s data center business, potentially with more disclosure around its partnership with Amazon, would also be constructive.
I would look more negatively on the stock if handset revenue continued to decline, or if Qualcomm’s new products failed to improve company margins due to rising costs.
The company’s product offerings are improving. The company needs to continue innovating its product line in order to improve its profit margins. Qualcomm’s next financial results are vital in assessing the company’s health.
Qualcomm Technical Analysis: QCOM Tests $200 Breakout as Bulls Eye $207.44
QCOM closed the last complete bar at $198.27, above the chart support at $196.38. The 4 hour chart is bullish, with recent higher highs and higher lows. QCOM has recently trade above the previous resistance at $194.77. Price is currently testing the resistance of the rising channel at $199 to $200. The product story has been improved. The same can be said for the upcoming financial story. RSI is 65, with the signal line at 64. RSI is bullish but not overbought, leaving room for further upside if resistance breaks.
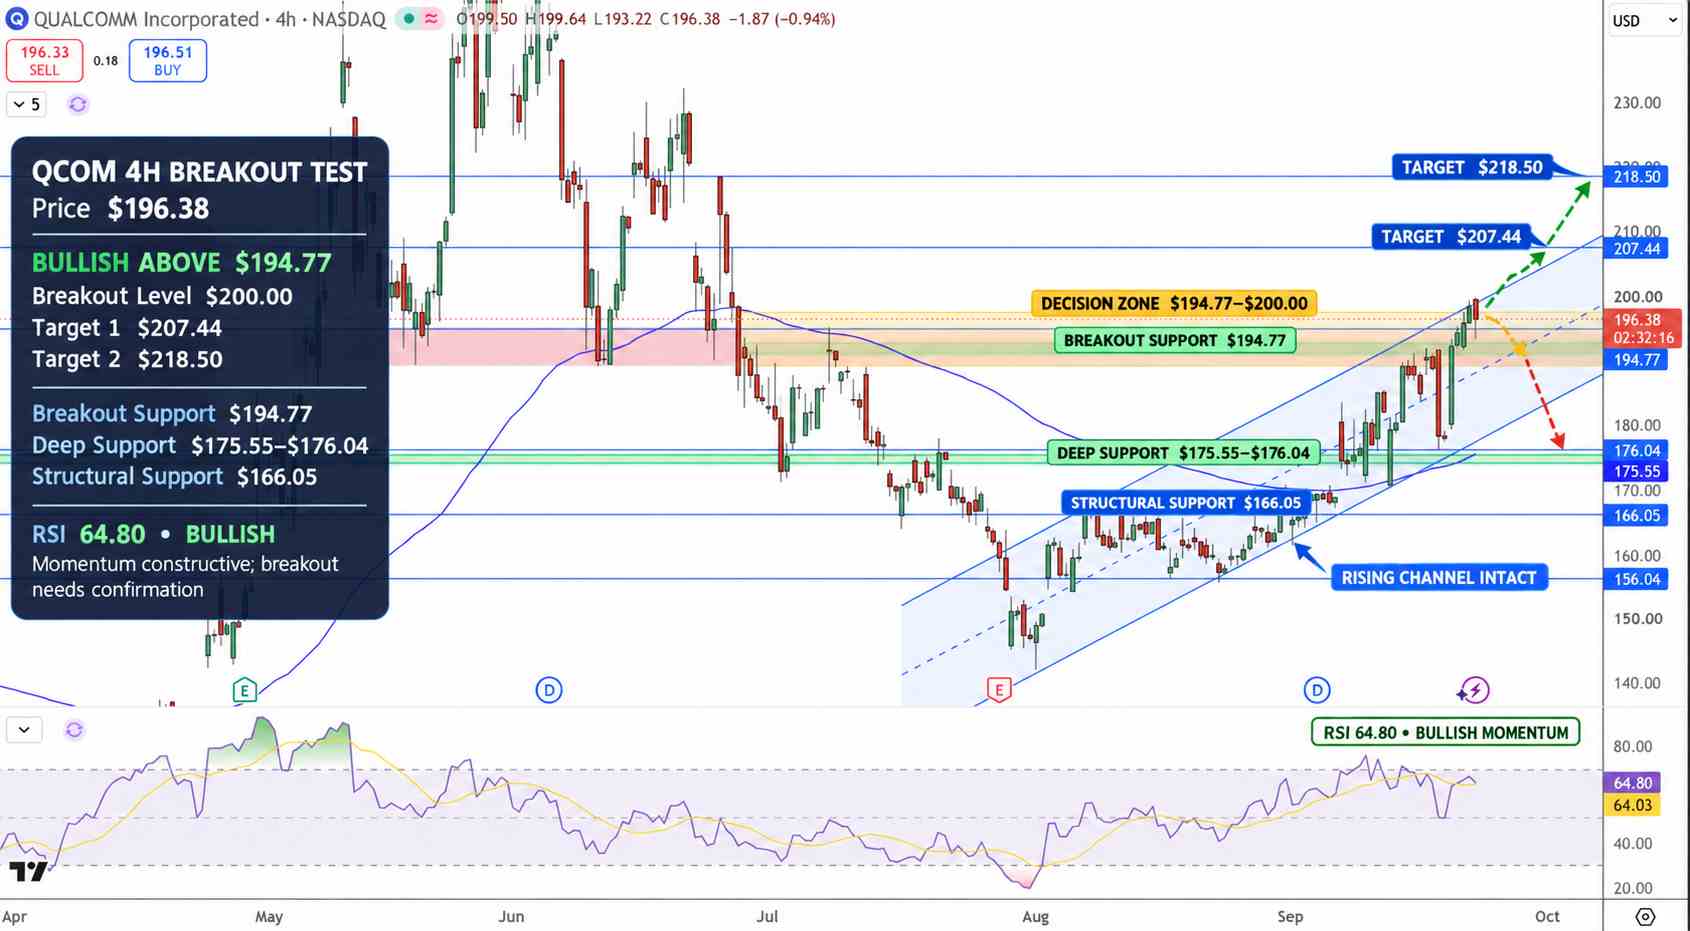
Qualcomm Stock Price Chart - Source: Tradingview
A close above 200 on the 4 hour would confirm the breakout and have next target 207.44. 218.50 is reached beyond that support, then 194.77.
A break would be a break that would open at 176.04, and then 175.55. Support at 166.05 is reached beyond that. I think the current outlook remains correct if QCOM trades above 194.77. Until a breakout is confirmed, $200 remains resistance, with 207.44 the next target. $194.77 remains the key near-term support level, with 176.04/175.55 and 166.05 the major support levels. RSI is at 65, bullish but not overbought.
Why is Qualcomm stock in focus now?
This week’s Snapdragon Summit communicated Qualcomm’s agentic-AI strategy for high-end smartphones. Additionally, the expansion of Snapdragon X Elite into the new Googlebook PC category, and Amazon’s AI data-center silicon and optical-connectivity collaboration, positively position Qualcomm for the future.
What level confirms a stronger QCOM breakout?
A clearer signal is a close above $200 on the 4-hour time frame. This would give a target of $207.44 and then $218.50. A move below $194.77 would be bearish.
Bottom Line
Although Qualcomm's business is clearly headed in the right direction, their most recent financial results showed a continued decline in the company's core business.
From a technical perspective, as long as Qualcomm trades above $194.77, the overall trend is bullish. A clear breakout above $200 would give Qualcomm a stronger short-term bullish setup and increase the likelihood of a move to $207.44. A break below $194.77 would give Qualcomm a bearish outlook and increase the probability of a move to the low $170's.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.