


SMIC: Full capacity is just the appetizer; price hikes are the main event?


SMIC (0981.HK/688981.SH) released its Q3 FY2026 results (through Sep 2026) after HK market close on Nov 12 Beijing time. Key takeaways are below:
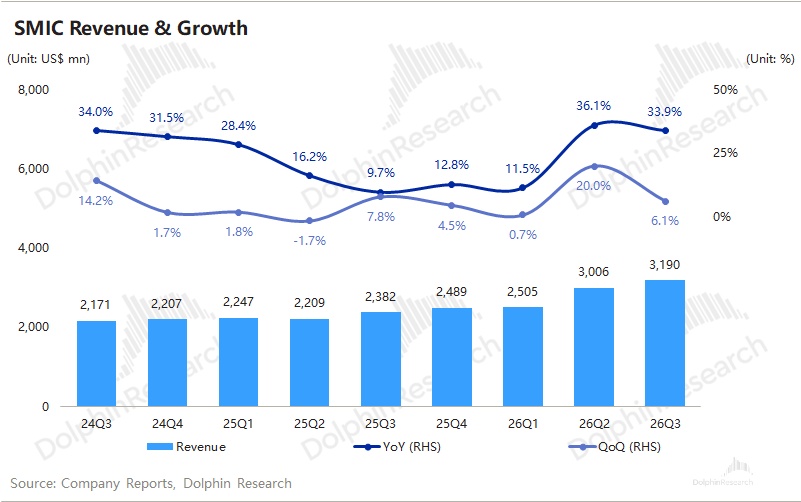
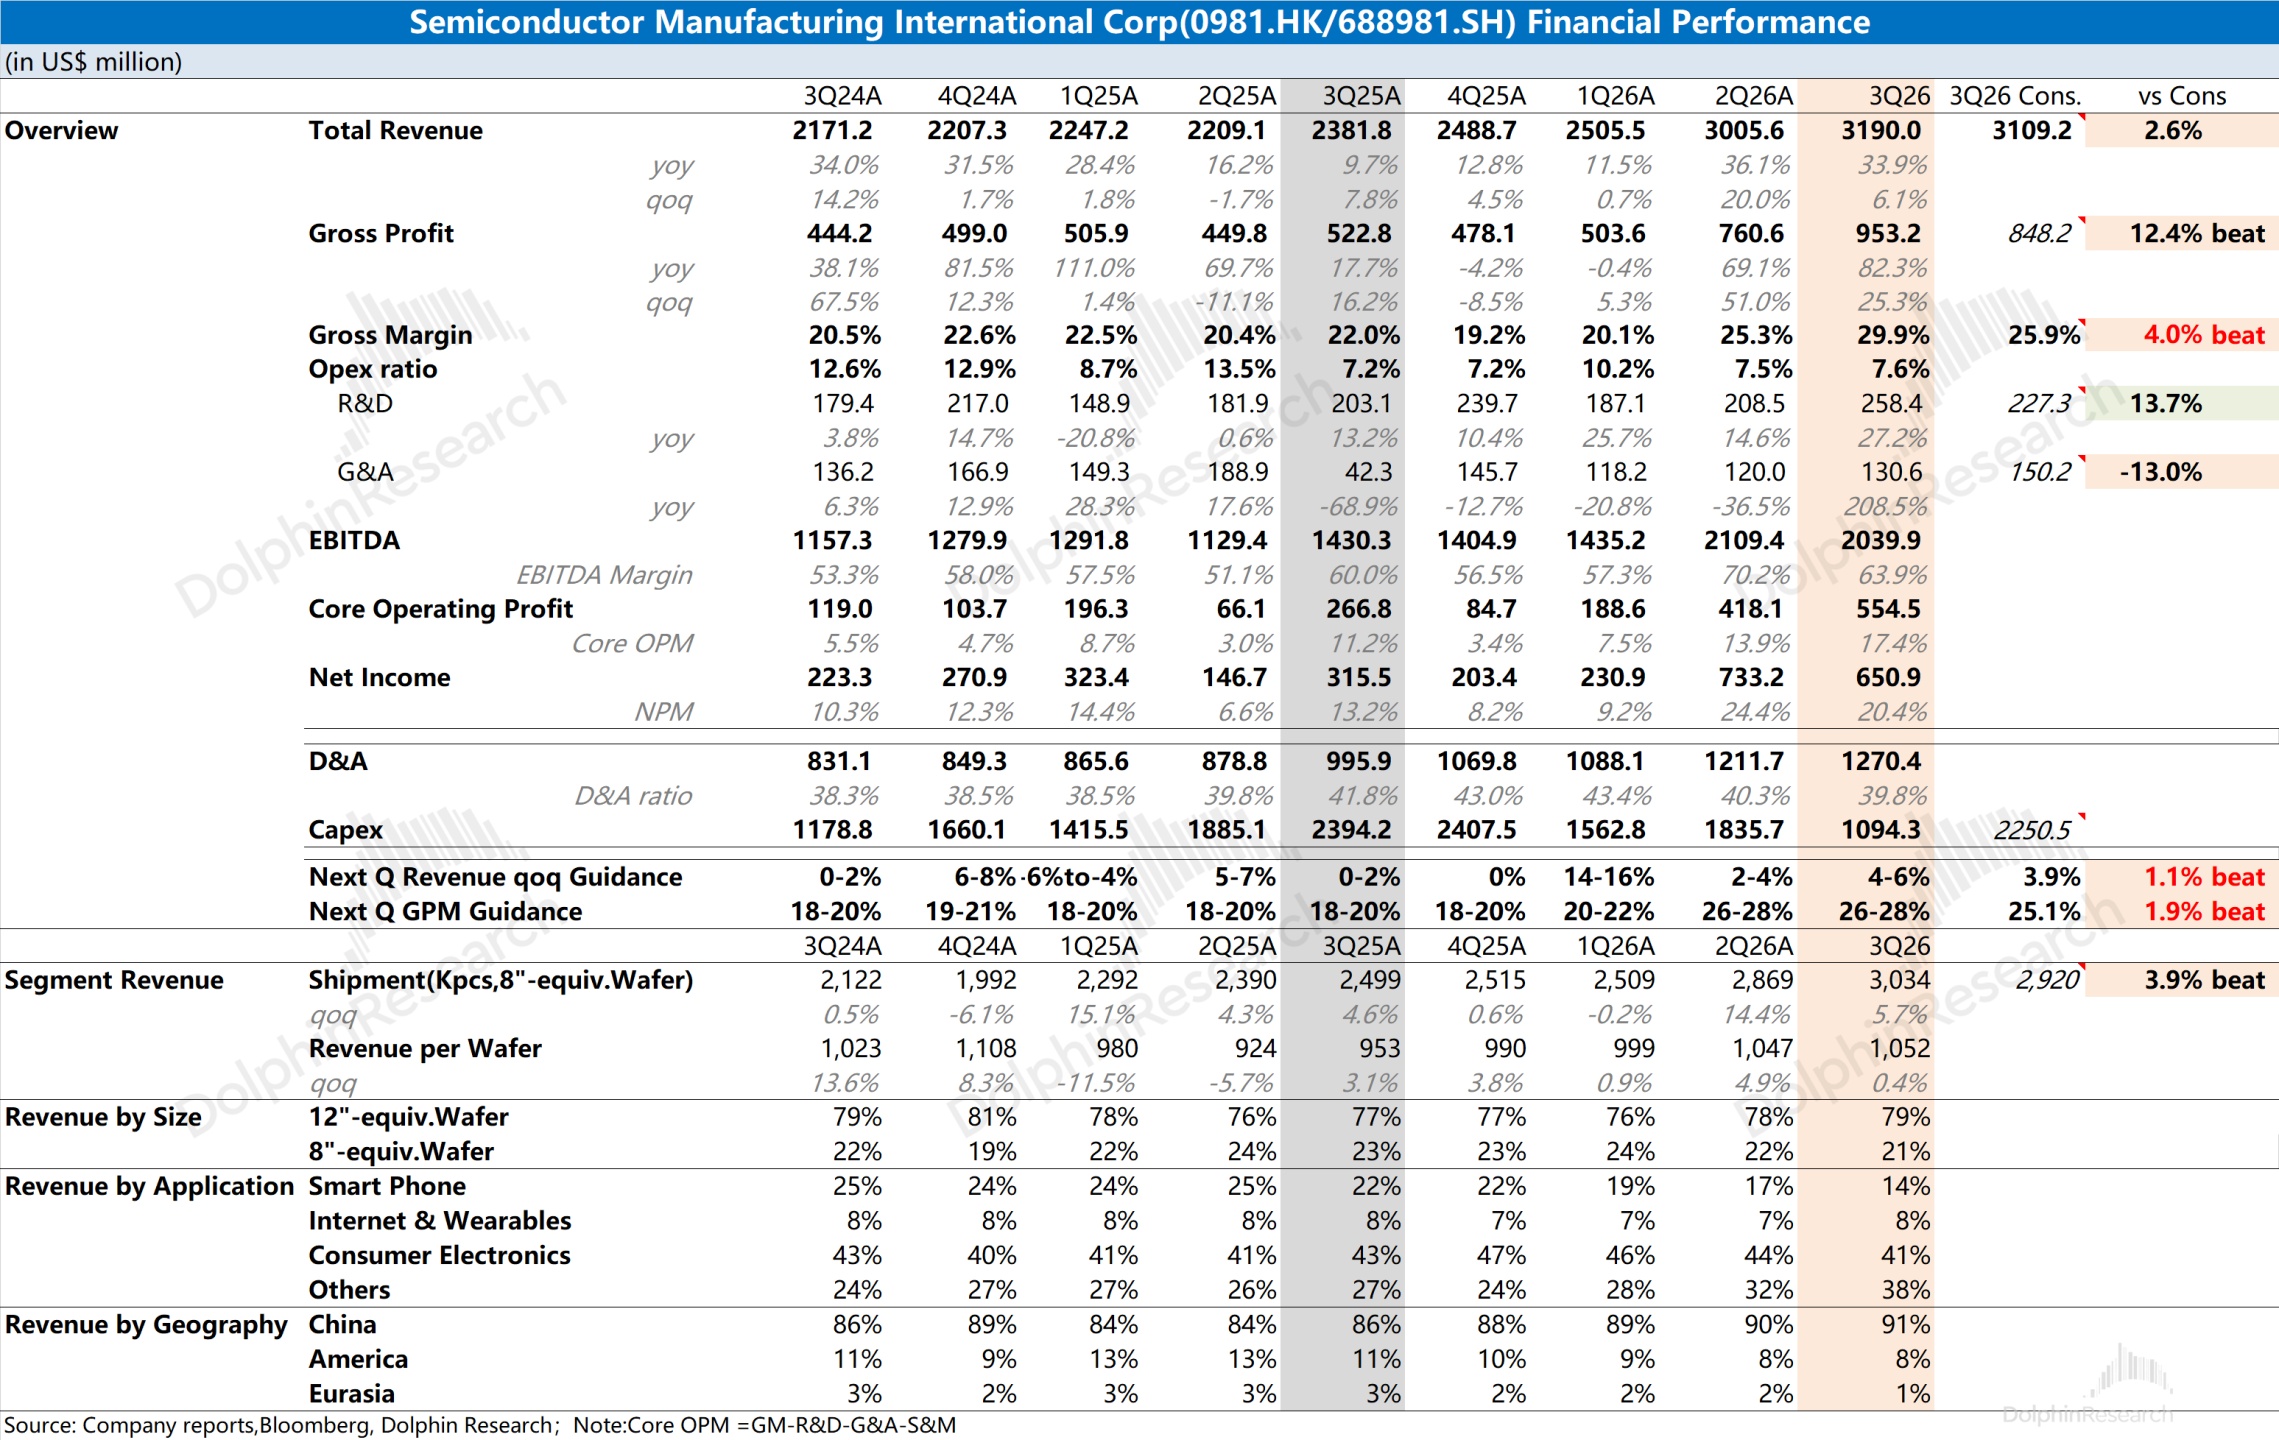
1) Top line: Q3 revenue came in at $3.19bn, beating consensus ($3.11bn), up 6.1% QoQ and above the high end of guidance (+2–4% QoQ; $3.07–3.13bn).
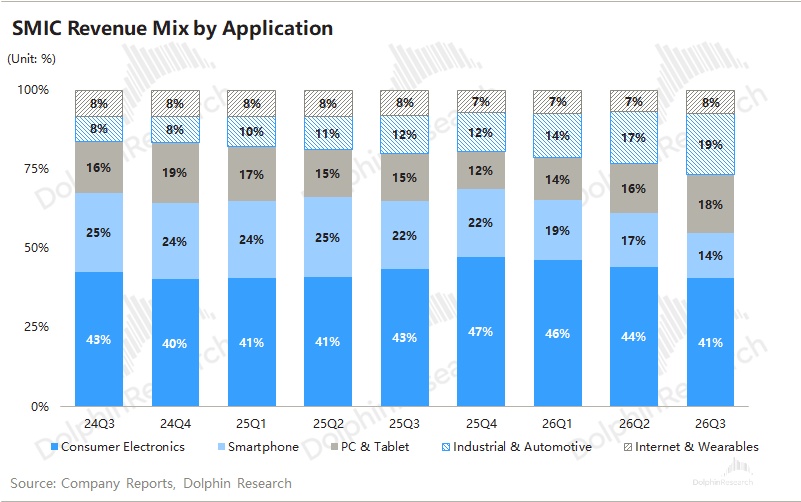
$SMIC(00981.HK) attributed growth mainly to higher wafer shipments. PC & tablet and industrial & auto were the key growth drivers, each up ~26% QoQ, while smartphone and consumer electronics declined QoQ.
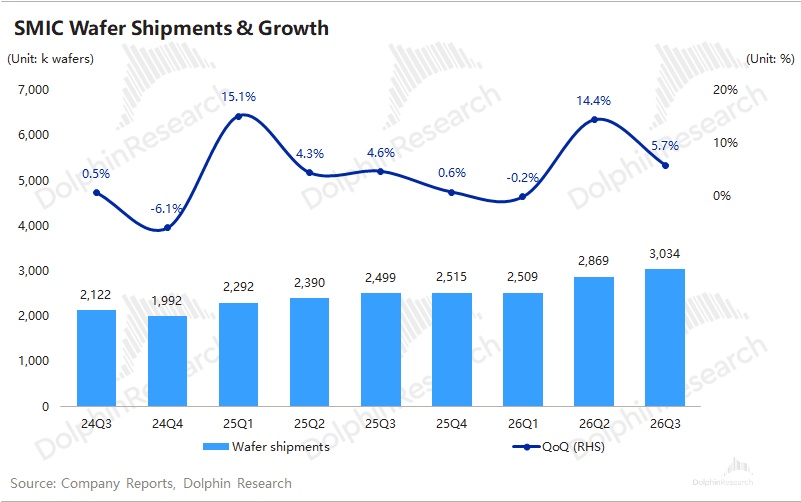
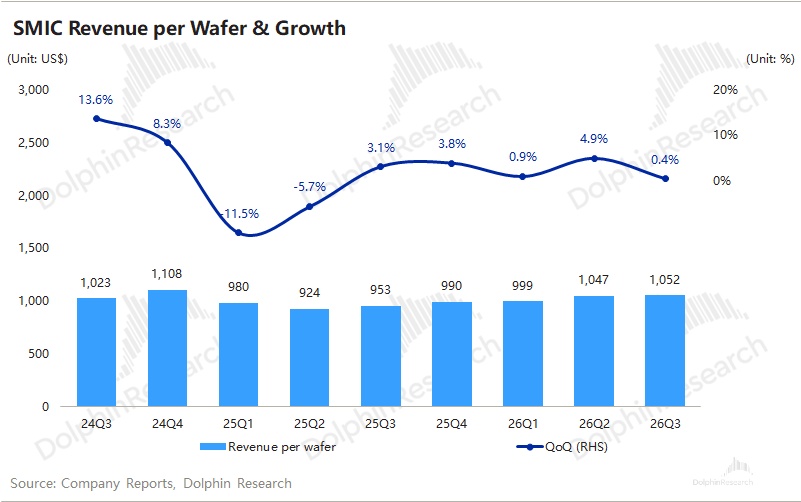
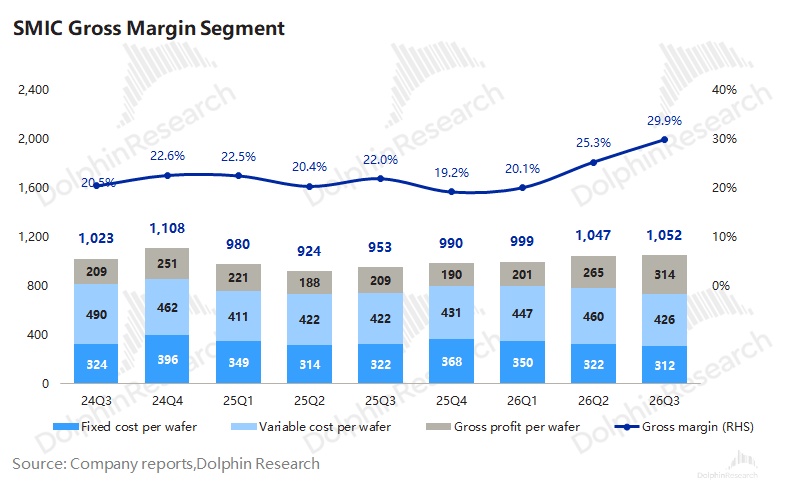
By volume/price split, 8-inch-equiv. wafer shipments reached 3.034mn units, up 5.7% QoQ. The blended ASP was about $1,052 per wafer, essentially flat QoQ (+0.4%).
Q3 revenue growth was volume-led: fab utilization rose from 93.7% to 97.3%, with monthly capacity also higher, pushing shipments to a record high. Pricing stabilized after a sharp rise in Q2, with revenue per wafer up ~0.4% QoQ.
2) GPM:$SMIC(688981.SH) posted a Q3 GPM of 29.9%, up 460bps QoQ and above guidance (26–28%). This is the highest since Q4 2022, driven by higher utilization and a better mix.
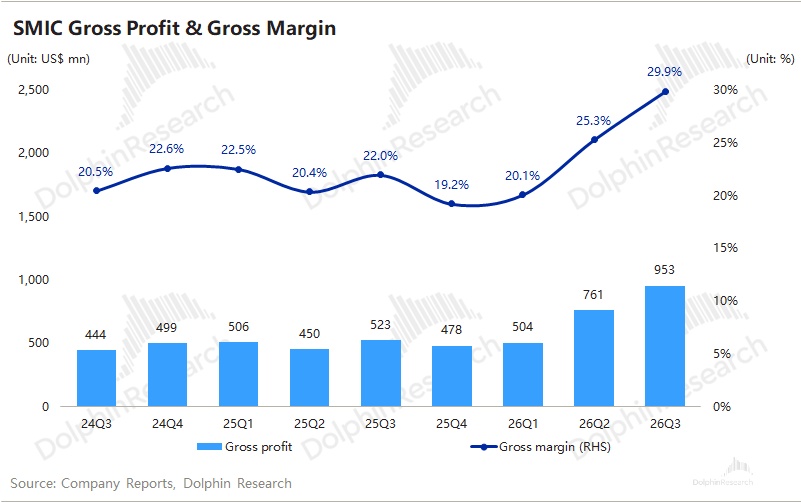
On a per-wafer basis, ASP rose by only ~$4 QoQ, while unit cost fell by about $45 QoQ (including ~$10.5 lower depreciation per wafer and ~$34.5 lower other mfg. cost), lifting per-wafer GP from $265 in Q2 to $314.
Decomposition suggests ~430bps of the 460bps GPM expansion came from lower unit cost, with price contributing under 30bps. Pricing was a minor tailwind versus cost leverage.
3) Biz. progress:
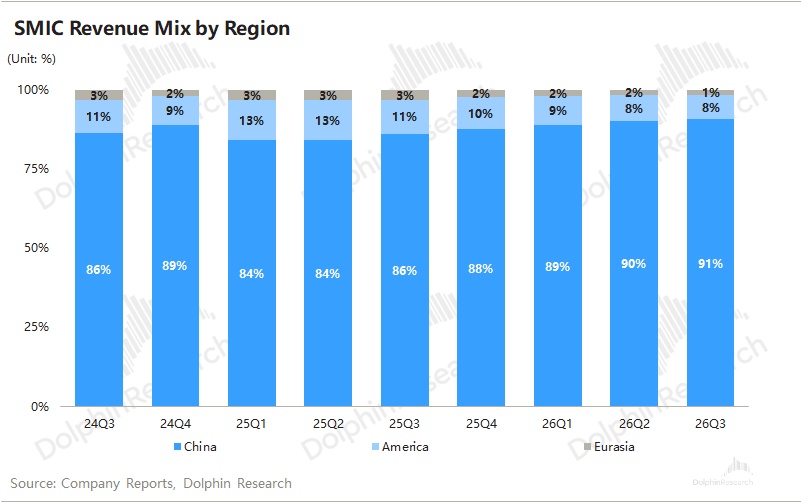
Helped by import substitution, China revenue mix rose to 90.8% this quarter, continuing to climb.
As leading foundries keep shifting capacity toward AI, SMIC continued to capture spillover orders in mature nodes, and localization mix kept rising. China revenue reached about $2.9bn (+41% YoY), while the U.S. mix fell to 7.8%.
By end-market, smartphones dropped to 14.3% amid a soft handset market. Industrial & auto rose to 19.3%, and PC & tablet increased to 18.3%.
Consumer electronics remained the largest revenue bucket at 40.6%. Wafer revenue in PC & tablet and in industrial & auto each grew ~26% QoQ, supported by AI-adjacent demand.
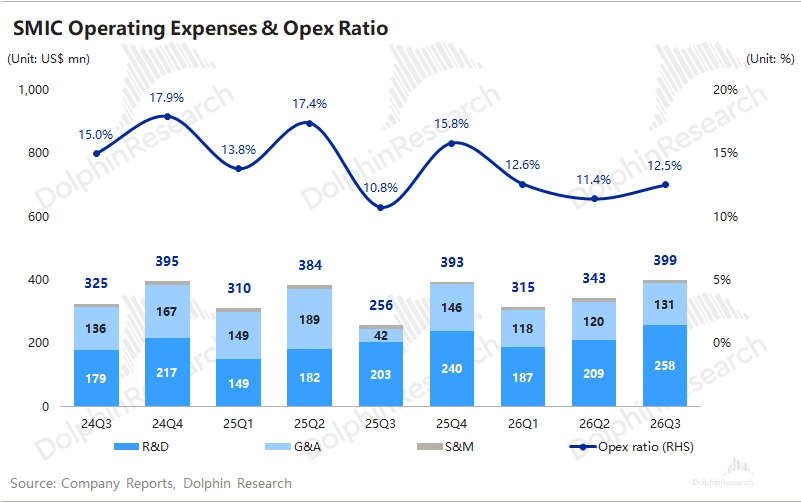
4) Opex and capex: Opex is mainly R&D and G&A, with ratios relatively stable. Q3 opex (after other operating income) was $243mn, up 7.4% QoQ, driven primarily by increased R&D activity.
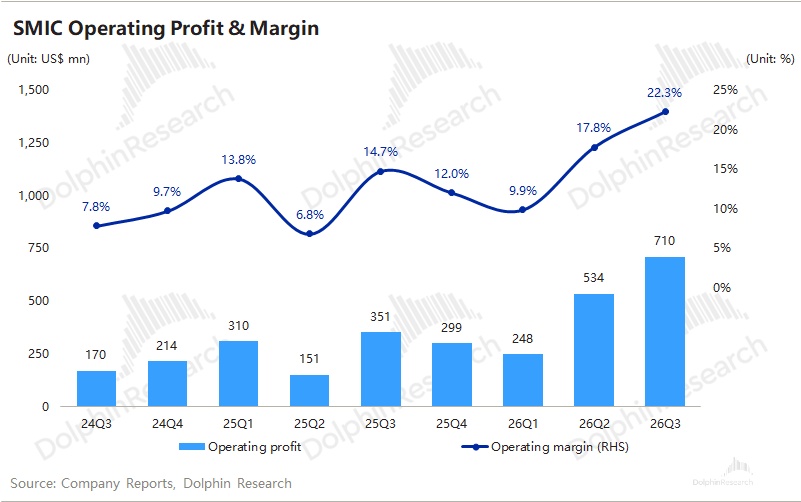
On profitability, OP was $710mn, up 32.9% QoQ, with an OPM of 22.3%, well above consensus ($540mn). Net income to shareholders was $428mn, roughly in line with the Street ($427mn), down 10.6% QoQ.
The QoQ decline in attributable NI was mainly non-operational (driven by fair-value changes in certain associate investment funds), resulting in about a $230mn QoQ drag.
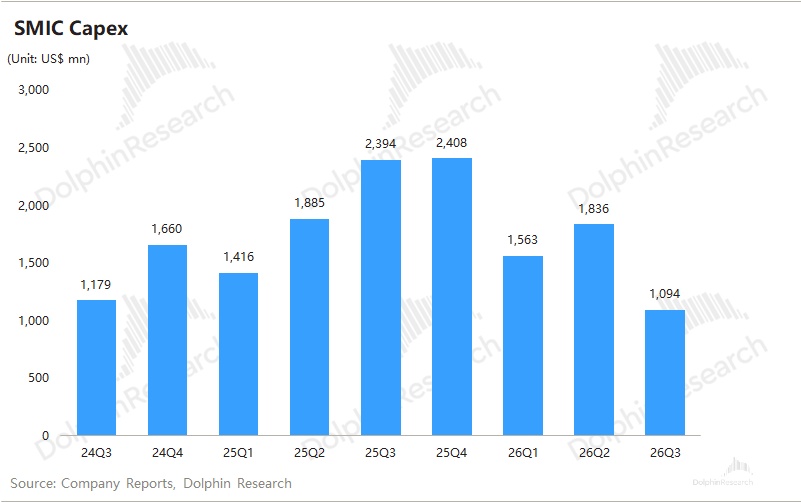
Q3 capex was $1.09bn, down 40% QoQ, well below consensus ($2.25bn) and the lowest since Q1 2022.
Given prior guidance that 2026 capex would be similar to last year (Approx. $8.1bn), Q4 would need about $3.6bn of spend, and any change to the full-year plan will hinge on management commentary on the call.
5) Q4 guide: SMIC guides Q4 revenue to grow 4–6% QoQ to $3.32–3.38bn, above consensus ($3.23bn). GPM guidance is 26–28%, above consensus (25.1%) but down QoQ, which Dolphin Research believes reflects higher D&A as projects are capitalized.
Dolphin view: full utilization takes over from pricing, GPM resets higher
On the surface the print was an across-the-board beat with GPM at a new high, but Q4 GPM guidance implies a QoQ pullback.
Under the hood, revenue growth was almost entirely shipment-driven with little move in per-wafer pricing. GPM gains were mainly from full utilization diluting depreciation and from mix, shifting the driver from 'pricing' to 'full utilization + mix'. But with lines near full, further dilution looks limited.
GPM trajectory since 2026: Q1 (20.1%) -> Q2 (25.3%) -> Q3 (29.9%) -> Q4 (guide 26–28%).
The midpoint of Q4 guide (27%) is lower QoQ primarily on higher depreciation. Based on management's ~30% YoY increase in 2026 depreciation, Q4 D&A likely rises by another ~$100mn QoQ, which would pressure GPM by roughly 2.5ppt.
Dolphin Research maintains that AI spillover plus localization keeps the medium-term 'volume + price up' thesis for mature nodes intact.
Key focus areas remain: capex and capacity, mature-node pricing, and progress in advanced nodes.
a) Capex, capacity, and depreciation: Q3 capex was $1.09bn, down 40% QoQ. If the full-year still tracks last year (~$8.1bn), Q4 would require about $3.6bn; watch for any tone-down on the call.
On one hand, long-term depreciation pressure could ease, though near term D&A will keep rising as projects move from CIP to fixed assets. On the other, with utilization already near full, a slower pace of new capacity will cap shipment growth, leaving revenue to lean more on price and mix.
Driven by sustained investment, SMIC's period-end monthly capacity reached 1.117mn 8-inch-equiv. wafers, up by ~20k QoQ. Utilization rose further to 97.3%, essentially full.
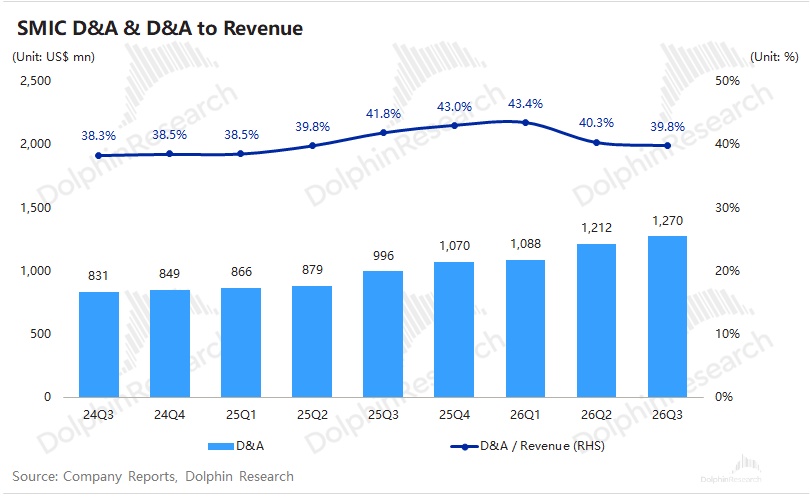
Expansion has also pushed D&A up rapidly: Q3 D&A was $1.27bn, up 27.6% YoY. Management previously guided 2026 D&A to rise ~30% (near $5.0bn), raising concerns that D&A may outpace revenue and cap GPM upside into 2027.
In Q3, D&A remained about 40% of revenue. Higher revenue and utilization effectively absorbed the D&A burden.
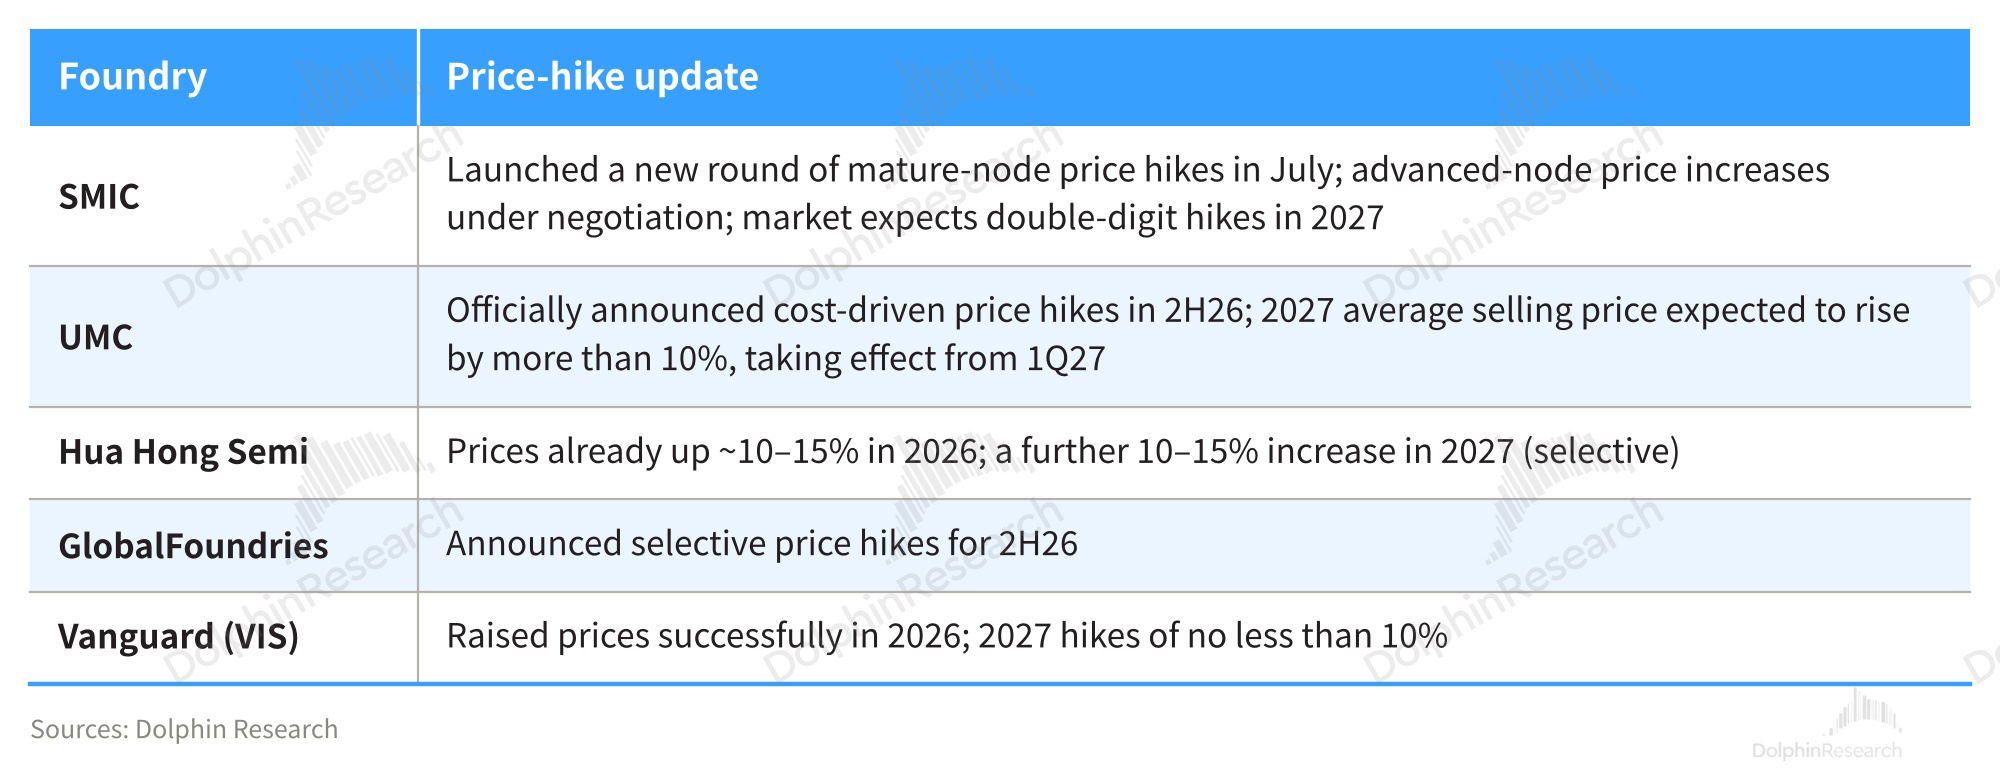
b) Foundry pricing: Industry checks in Q3 indicate analog and power capacity is full at both 8-inch and 12-inch, with tightness likely lasting into H2 2027. Downstream chipmakers have raised prices multiple times this year, passing through higher costs.
That said, the breadth of price hikes remains debated. Management said at the Sep briefing that pricing is 'strategic rather than opportunistic', deferring hikes for weaker end-markets like smartphones and consumer electronics. Recently the PC chain saw order cuts, and some consumer analog clients have struggled to pass on foundry increases.
SMIC's Q3 per-wafer revenue rose only ~0.4% QoQ, making price a much smaller contributor than in Q2. But with Q4 revenue guided to grow 4–6% QoQ and utilization already near full, growth likely reflects not only incremental capacity but also price and mix; there is no sign of a price reversal.
How 2027 price negotiations evolve, and whether smartphone/consumer clients accept hikes, remain key watchpoints.
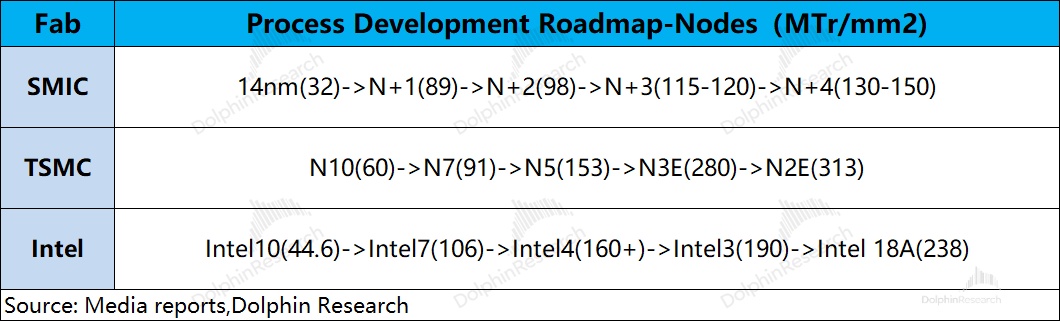
c) Competitiveness and node progress: SMIC is firmly in the second tier of foundries alongside UMC and GlobalFoundries, while still pushing toward the first tier.
Based on company and industry info, SMIC is iterating N+1, N+2, N+3 etc. via multi-patterning on DUV. Third-party teardowns suggest N+3 transistor density near ~115 MTr/mm², and the next-gen N+4 will approach TSMC's 5nm level. However, pure DUV multi-patterning brings many mask layers, higher cost, and a tougher yield ramp.
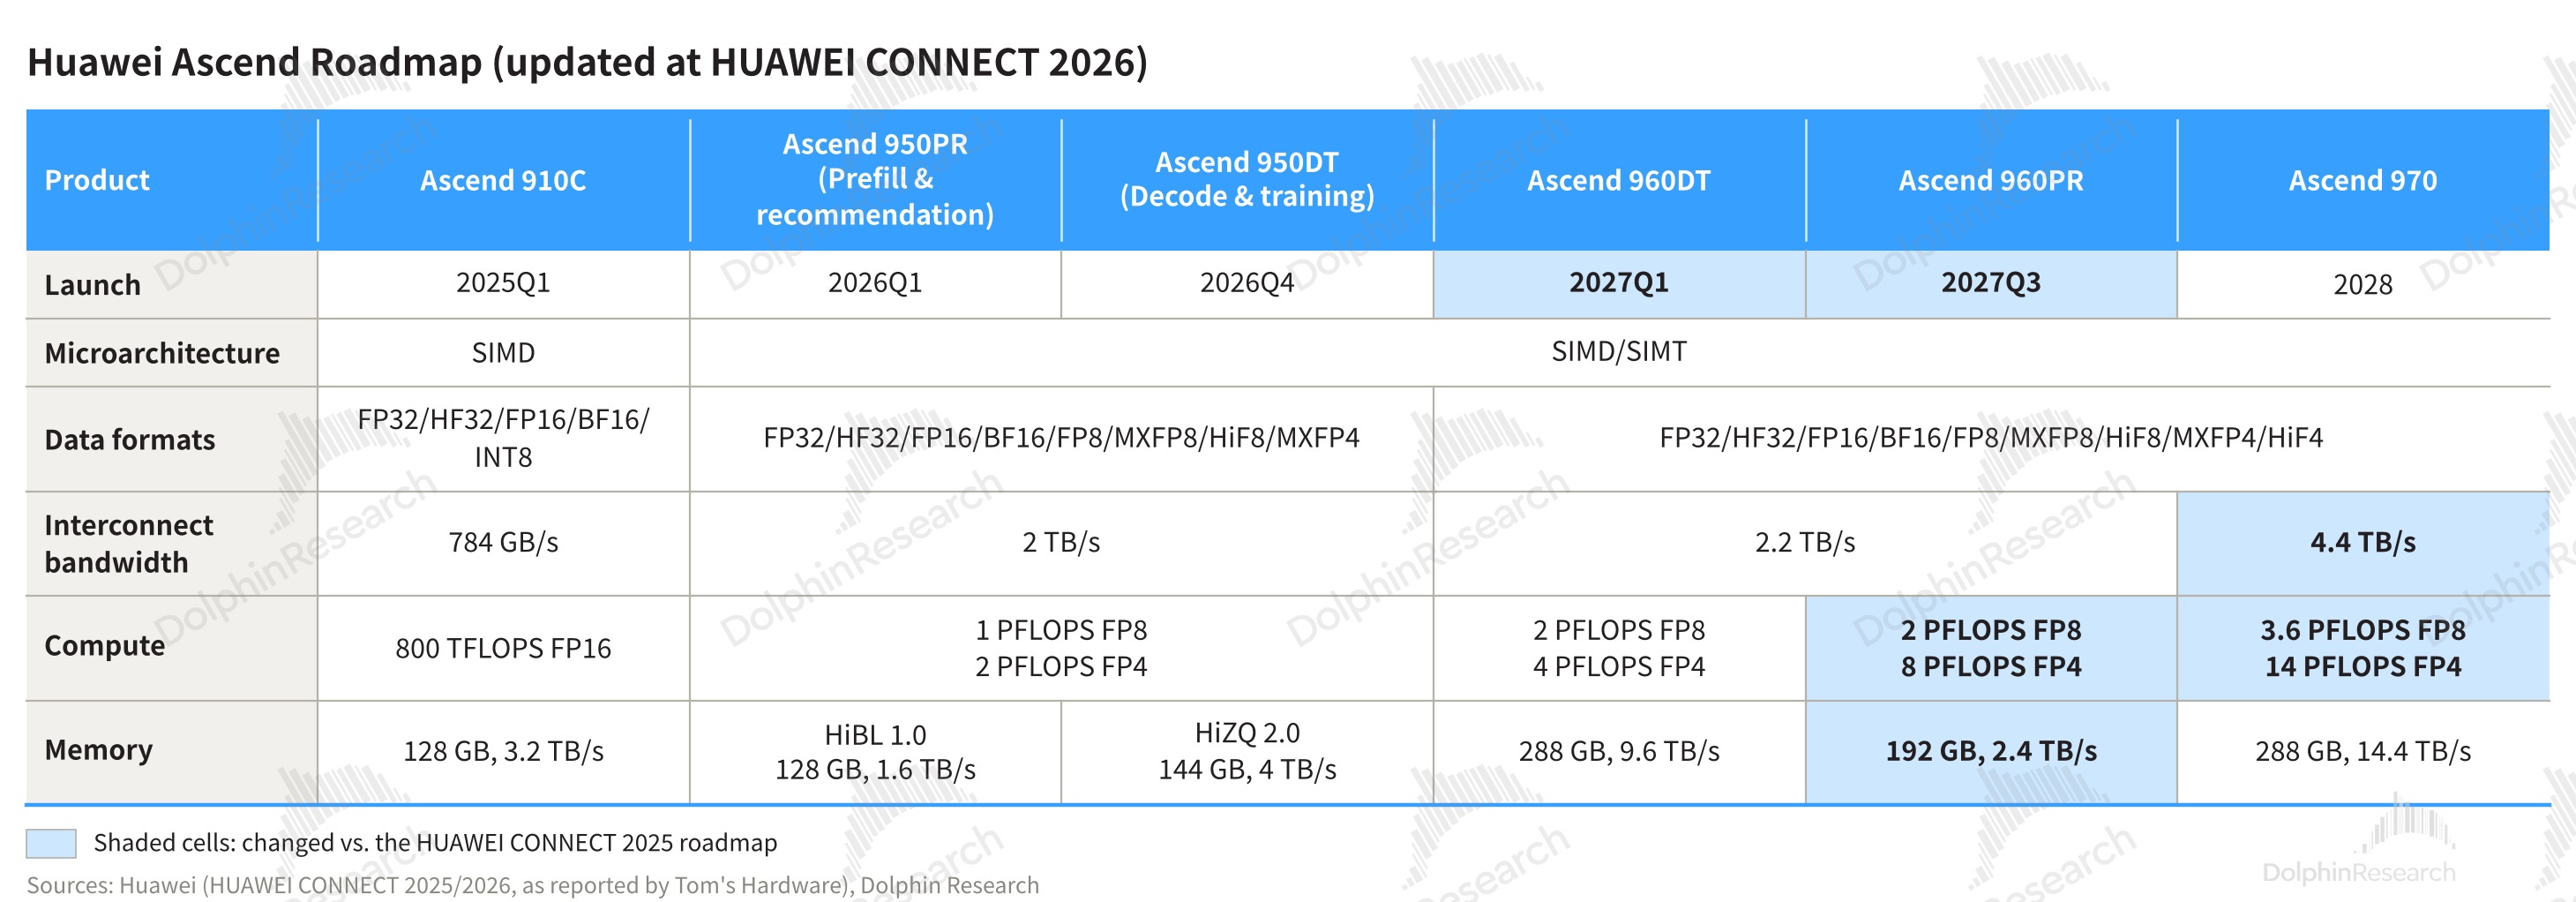
Beyond mature-node pricing, multiple expansion hinges on expectations for SMIC's advanced nodes. H is itself a major customer, and as Ascend 950DT/960DT shipments ramp, advanced-node revenue should see a notable lift.
With a current market cap of HKD 425.2bn, shares imply roughly 19x 2027 core after-tax operating profit (Est.) assuming a 2-year revenue CAGR of +26%, GPM at 28%, and a 7.5% tax rate. As the semi cycle turns, GPM has entered the 25–30% range, and earnings recovery should work down the P/E.
On P/B, major foundries trade roughly as: TSMC 9.7 > UMC 2.7 > SMIC (H) 2.2 > GlobalFoundries 2. With the pullback, SMIC's P/B has clearly fallen below UMC.
Overall, SMIC delivered a standout Q3: revenue, shipments, and OP all hit record highs, with GPM near 30%. The GPM uplift came mainly from cost dilution at full utilization, showing that even with rising D&A, SMIC can keep margins elevated.
While Q4 GPM guidance is lower vs. Q3, the 26–28% range is still well above the Street, and given management's conservative style, the GPM run-rate has likely stepped up.
The company remains in a favorable pricing cycle, and several foundries have indicated price hikes will continue into 2027. Further pricing realization or scaling advanced-node production are potential catalysts, and earnings could improve further; Dolphin Research maintains SMIC is at a 'sweet spot'.
Do watch the earnings call. If management provides an upbeat 2027 outlook, it could further boost confidence.
Dolphin Research SMIC archive:
Earnings season
Aug 13, 2026 call recap 'SMIC (Trans): Pricing to be negotiated with clients; 2027 will be the D&A peak'
Aug 13, 2026 quick take 'SMIC: Cycle upturn + domestic AI chips, dual engines lifting off'
May 14, 2026 call recap 'SMIC (Trans): Foundry pricing trending up; hikes to persist'
May 14, 2026 quick take 'Two hands: price hikes and a new story — is SMIC about to surge?'
Feb 10, 2026 call recap 'SMIC (Trans): Handset pessimism overdone; memory tightness to ease by Q3'
Feb 10, 2026 quick take 'SMIC: Counter-cyclical capex — the hope of domestic AI chips?'
Nov 13, 2025 call recap 'SMIC (Trans): Memory prices rising; OEMs turn cautious on next year'
Nov 13, 2025 quick take 'SMIC: Not chasing the short-term print — is 'domestic AI chips' the true faith?'
Risk disclosure and disclaimer: Dolphin Research Disclaimer and General Disclosure
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.