


HSAI: Soft guidance — is the sector leader stalling?


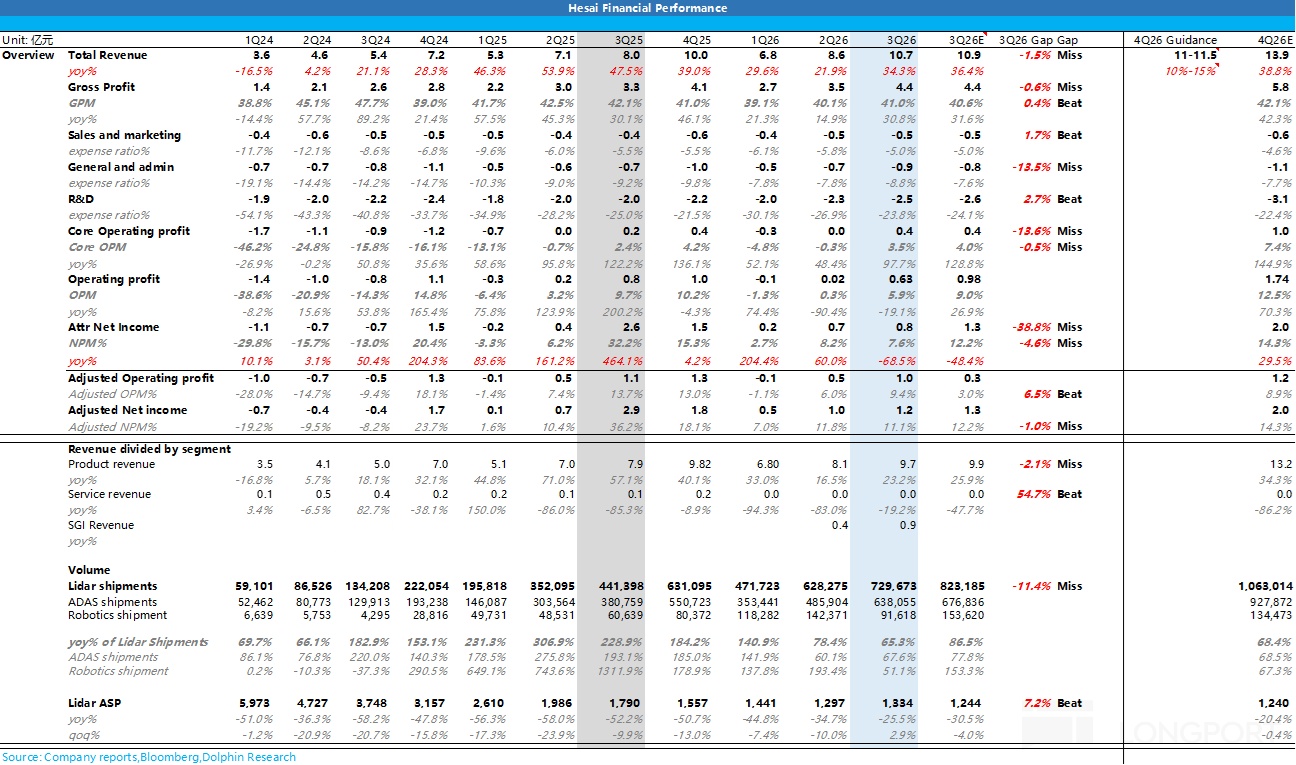
Overall, $Hesai(HSAI.US) delivered a 'good price, weak volume, soft guide' print. Revenue missed the low end of guidance, shipments fell well short, and 4Q revenue guide is ~20% below Street. That said, lidar blended ASP rose QoQ for the first time after a long slide, and GPM beat.
① Total revenue missed guidance: Q3 revenue was RMB 1.068bn (+34.3% YoY), below the RMB 1.10–1.15bn guide low end (~3% short). This was the first miss vs. guidance in recent quarters.
By segment, SGI (Kosmo and actuator modules) delivered RMB 91mn, roughly doubling QoQ, reaching ~RMB 135mn YTD and already above the RMB 100mn full-year goal set at the start of the year. Core lidar revenue was RMB 978mn (+22.9% YoY), constrained by shipments running well below plan.
② Lidar volumes were far below expectations: Shipments were 729.7k units in Q3 (+65% YoY) vs. guidance of 800–850k and Street at 823k. Breakdown as follows:
a. ADAS lidars were 638.1k (+68% YoY), slightly below the 677k expected. The shortfall was tied to weaker-than-expected sell-through on downstream models, with several OEMs cutting 2026 volume targets. b. Robotics lidars were just 91.6k, down 36% QoQ and well below the 154k expected. The drag stemmed from issues at a key downstream customer, weighing on low-price JT series (mainly lawnmowers), while Robotaxi and humanoid-robot lidars tracked in line.
③ But pricing inflected upward: Blended ASP was ~RMB 1,334, up ~3% QoQ and down ~26% YoY, well above the ~RMB 1,210 expected. The rebound was mix-driven.
Management indicated robotics lidars contributed ~50% of lidar revenue. Back-solving implies robotics ASP at ~RMB 5,300 and ADAS ASP at ~RMB 770. With fewer low-price lawnmower units and more high-price Robotaxi units, blended ASP rose while ADAS ASP itself stayed low.
④ GPM beat, reaching 41%: Q3 GPM was 41.0%, above the 39.9% expected, up 90bps QoQ and down 110bps YoY (higher mix of lower-margin products). Despite shipment shortfalls, mix shift toward higher-priced Robotaxi/humanoid-robot units and tech-driven cost-downs supported margin.
⑤ OP missed; SGI losses widened: Q3 OP was RMB 63mn vs. ~RMB 98mn expected. Lidar segment OP rose 88% YoY to RMB 145mn with ~15% OPM, but SGI was a drag: revenue roughly doubled QoQ to RMB 90mn, while loss widened to ~RMB 83mn.
This marks a shift from 'price for volume' to 'core holds price while new biz burns cash'. Short-term earnings elasticity now hinges on SGI investment cadence.
⑥ GAAP net income fell sharply YoY on one-offs: GAAP net income was RMB 81mn vs. ~RMB 132mn expected. The 69% YoY decline was due to a RMB 185mn one-time gain in the base; ex-one-offs, GAAP net income rose ~14% YoY.
Dolphin Research key takeaways:
Net-net, the quarter was 'good price, weak volume, soft guide': both revenue and shipments missed, while GPM and ASP beat, and OP was dragged by SGI losses.
More importantly, 4Q guide of RMB 1.10–1.15bn is ~19% below Street at ~RMB 1.39bn, implying just +10–15% YoY and +3–8% QoQ, undermining the H2 ADAS peak-season ramp thesis. At ~RMB 1,300 ASP, 4Q shipments imply ~750–800k units vs. Street at 1.06mn.
On the 4Q midpoint, 2026 full-year revenue would be ~RMB 3.73bn (+~23% YoY), ~11% below the lower end of the RMB 4.2–4.6bn initial guide and below Street at RMB 4.11bn. Full-year shipments would be ~2.6mn (+60% YoY), below the 3.0–3.5mn guide; YTD net income is ~RMB 170mn, implying full-year likely ~RMB 250mn vs. the RMB 500–700mn goal.
On the call, management only reiterated three full-year items: 2026 SGI revenue of RMB 200–300mn, GPM near 40%, and Opex up ~20% YoY (all incremental from SGI, lidar Opex down YoY). The 3.0–3.5mn shipment and RMB 500–700mn net income targets were not reaffirmed, effectively abandoned. For a weak 4Q, the company cited 'moderate downstream demand'.
Thus, the issue has shifted from last quarter's 'price falling too fast' to 'price stabilized but volume lagging'. Per management, the shipment slowdown reflects a soft China auto market and OEM target cuts, plus a single-customer issue on JT series, rather than broad-based demand erosion.
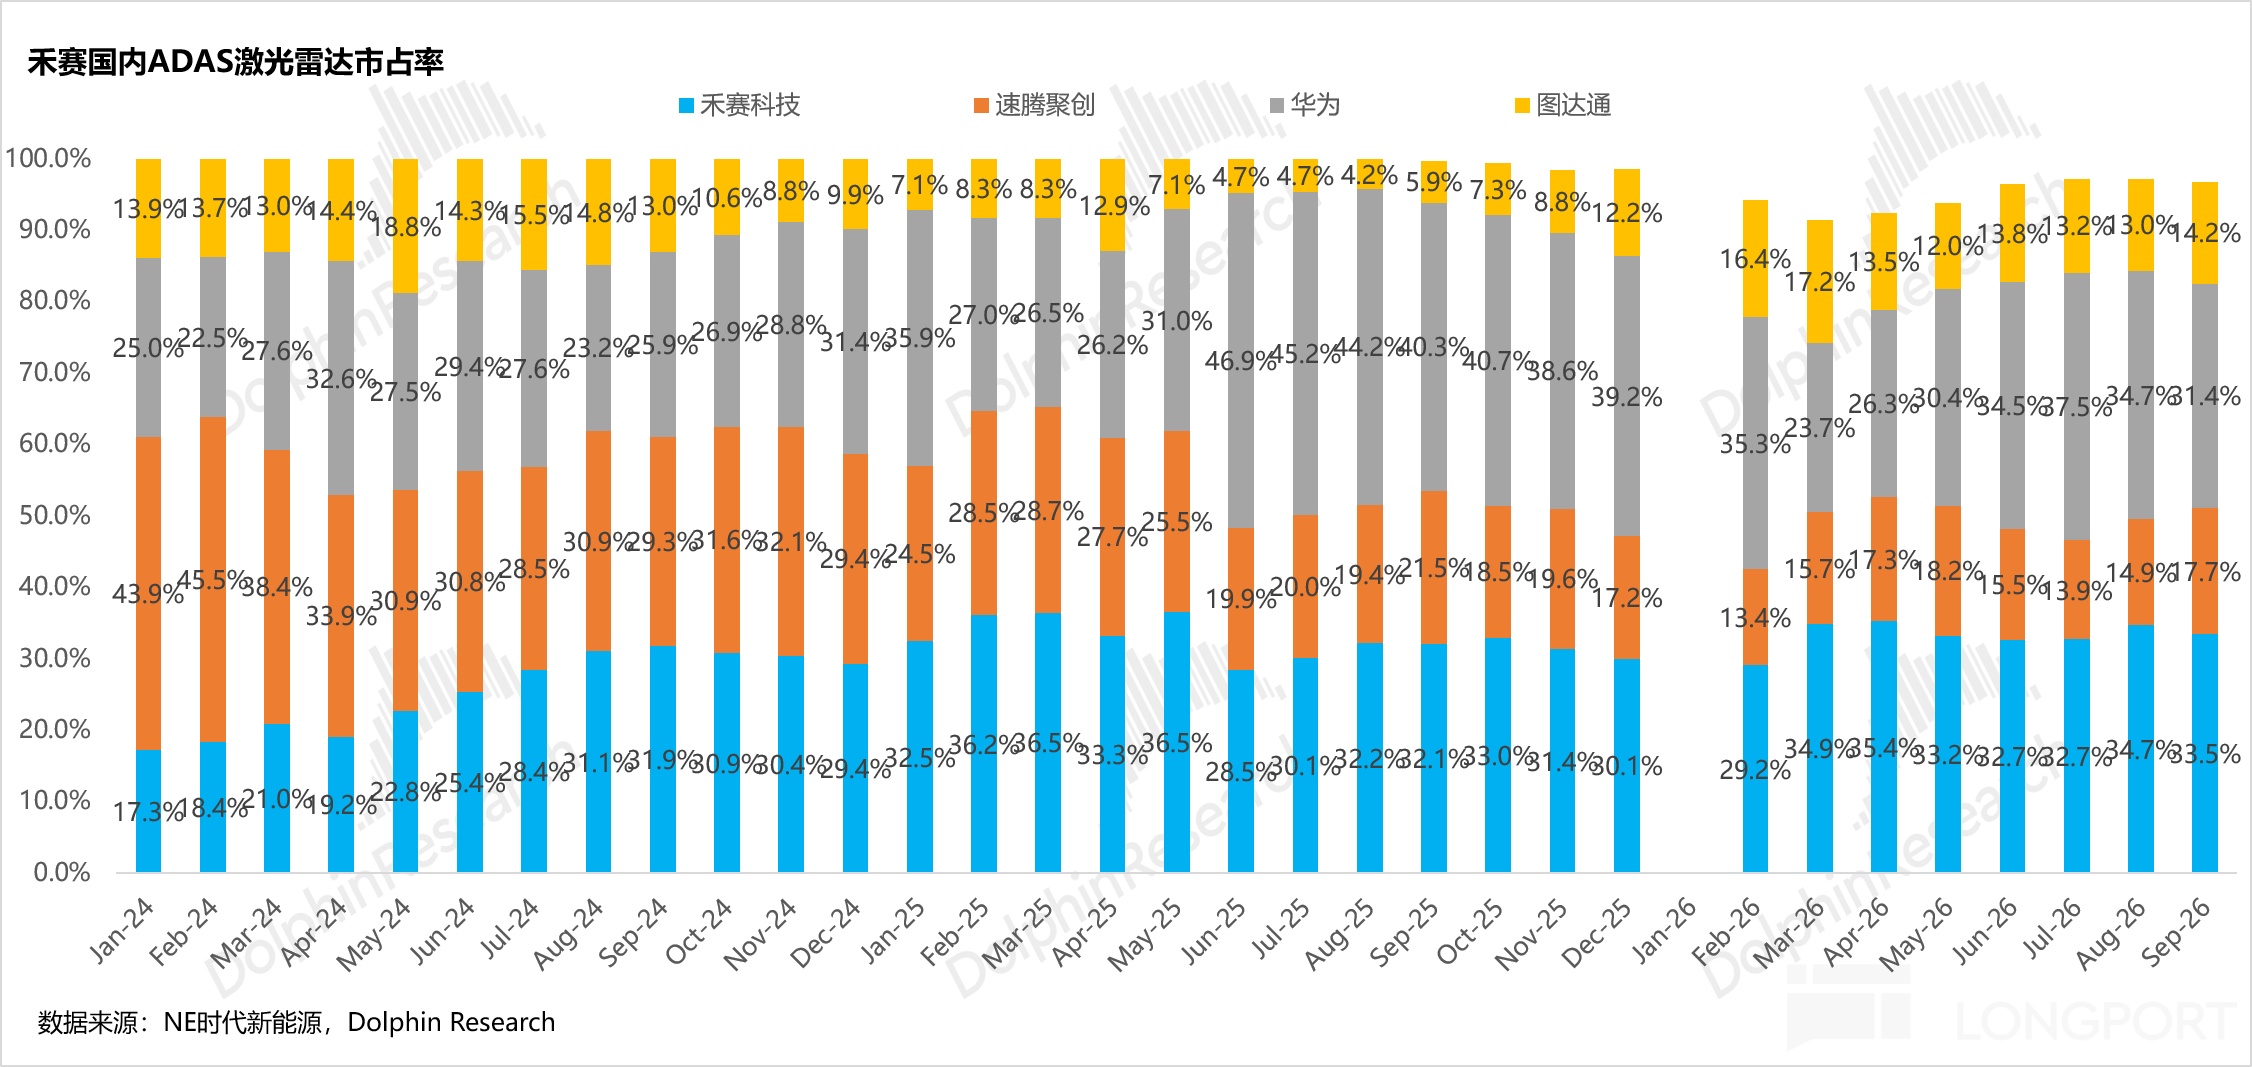
Dolphin Research also sees share loss as a factor: China long-range ADAS share fell to 43% in Sep from 55% in Mar, with Xiaomi onboarding RoboSense as a second source and Huawei's blind-spot lidars catching up. Management did not address this directly, saying it will not trade quality for price.
For Hesai, this is the necessary pain of navigating the price-war cycle while positioning for next-gen sensor ecosystems:
① ASP stabilization is the most important positive this quarter:
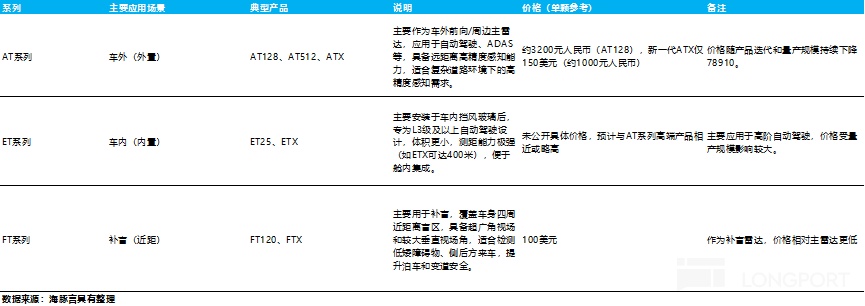
Last quarter's core worry was the rapid ASP decline (Q2 YoY -35%). This quarter's blended ASP uptick was mix-driven, but the real signal was management commentary: based on signed 2027 ATX contracts, ADAS pricing is turning rational and 2027 ATX price and margin should 'further stabilize'. That aligns with our view that 2027 shifts from deflation to steady annual declines.
Support comes from premiumization and multi-lidar configs: the high-end ET series has five awards from global OEMs (a top European OEM, Cadillac, Geely, Great Wall, and a leading NEV maker), with over 1mn units on order and pricing above ATX. ET with in-house Picasso chip is under customer validation. FT blind-spot lidars have wins at Leapmotor and a top European OEM; L3 is pushing toward 'premium main lidar + multiple blind-spot units'. But with most core parts and ASICs already in-house, cost-down headroom narrows, leaving future margin more reliant on price stability and mix.
② Shipments stalled, full-year target likely out of reach:
ADAS: Q3 shipments were 638.1k, +31% QoQ but below guide. New awards include AT series at SAIC-GM-Wuling, expanding into mass-market models; seven OEM export awards (incl. Chery) have not disclosed SOP timing, described only as '0 to 1' incremental; via the JV, there are awards at 10 global OEMs with volume expected next year. Robotics: Q3 shipments were 91.6k, down 36% QoQ, mainly due to the JT-series single-customer issue.
Even so, YTD robotics shipments reached 352k, more than doubling YoY, with high-end products (Pandar, OT, QT, XT) revenue up over 60%. Robotics lidars now account for ~50% of lidar revenue. Drivers include Robotaxi fleet expansion (62% global share in 2025, ranked No.1), multi-lidar per humanoid robot (JT128 may ship six figures next year), and physical-AI use cases in industrial and retail (incl. JD.com's plan to deploy 4mn devices over five years). Management believes the robotics lidar TAM is at least 10x ADAS.
③ SGI continues to beat on revenue, but losses are widening:
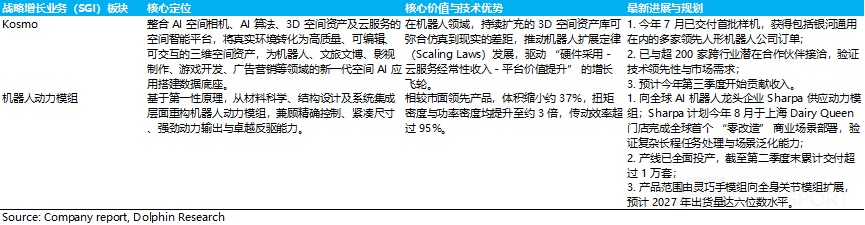
Q3 SGI revenue was RMB 91mn, roughly doubling QoQ; YTD reached ~RMB 135mn. The company reiterated the full-year RMB 200–300mn guide (implying RMB 65–165mn in Q4). Within SGI:
a. Actuator modules: Q3 shipments were 23.4k, +97% QoQ, with cumulative shipments ~35k; current monthly capacity is 10k, and 2027 shipments could reach six figures, contributing the bulk of this year's SGI revenue. Flagship customer Sharpa has entered commercial deployment, with its full-body robot D01 and dexterous hand W02 both using Hesai modules. Key components are self-developed, delivering torque and power density ~3x leading peers, and the company is in talks with multiple humanoid-robot firms.
b. Kosmo (3D world data engine): Revenue began in Q3. Hardware dominates this year, while software subscriptions and 3D asset licensing should grow materially next year, with GPM likely to exceed 40% at scale. Partners include Pixar RenderMan (film), Galaxy Universal and Dexmal (robot training), and Gaode (1,000-location spatial commerce pilot).
SGI loss widened from RMB 64mn in Q2 to ~RMB 83mn, as demand outpaced expectations and the company stepped up investment. This will cap near-term profitability.
The 2027 targets are clear: SGI revenue of ~US$100mn (~RMB 700mn), >10% of total revenue, with breakeven that year and no major capex uplift required.
④ GPM and expenses:
Q3 GPM was 41.0%, ahead of expectations. A higher mix of high-margin robotics lidars plus in-house chips offset scale deleverage from lower shipments. Management guides 2026 full-year GPM near 40% and broadly stable in 2027.
On costs, R&D and G&A both rose ~28% YoY, driven by SGI and professional fees; ex-SGI, lidar expenses declined YoY. Lidar segment OPM was ~15%, indicating the core remains profitable.
At the current share price, we model 2026 revenue at ~RMB 3.7bn (+~23% YoY) and GAAP net income at ~RMB 250mn (4Q at midpoint guide and 40% GPM implies ~RMB 80mn). That is well below the initial RMB 500–700mn guide.
For 2027, while management has not provided specifics, we assume lidar unit growth of +28% YoY to 3.33mn, ASP down ~7% YoY to RMB 1,246, and with ~RMB 700mn SGI revenue, total revenue up ~30% YoY to RMB 4.86bn. On profit, if SGI breaks even and offsets this year's ~RMB 250–300mn loss, and lidar profit resumes growth, net income could reach ~RMB 600mn (+174% YoY).
At 11/11 close, market cap was ~RMB 15.1bn, implying ~60x 2026 P/E, or ~36x ex net cash of ~RMB 6.1bn. On RMB 600mn in 2027 net income, P/E is ~25x, or ~15x ex net cash.
Back in the Q2 review, we argued upside elasticity into 2026 was limited when market cap was ~RMB 18.0bn. Today it is ~RMB 15.1bn. ATX price stabilization, ET awards, and SGI breakeven targets are positives, but shipment stall and a much weaker 4Q guide push the earnings repair from 'late 2026' into 2027.
Dolphin Research sees a lack of near-term catalysts and would wait for: ① 2027 full-year guide, ② ET mass production plus execution on overseas and JV awards, and ③ narrowing SGI losses.
Medium to long term, lidar has 'Moore-like' attributes (exponential point-cloud density up, exponential cost down) and high moats. With dual engines of ADAS penetration and robotics, Hesai remains a high-certainty long-term beneficiary:
① Near-term share under pressure, but tech stack is comprehensive; mid-to-long-term share should hold:
Share has slipped from 55% in Mar to 43% in Sep, but Hesai has been No.1 for 20 consecutive months. Its next-gen pipeline is broader: Picasso full-color SPAD-SoC, 4,320-line ET, MT series, and FMCW. We expect share to be resilient over time.
② L3 drives a step-up in per-vehicle content:
L3 shifts demand from a single main lidar to 'one main + multiple blind-spot units', lifting per-vehicle content from ~US$200 to US$500–1,000. New ET and FT awards show multi-lidar configs are landing in China and abroad, with China L3 regulation expected around 2027.
③ Overseas markets entering a breakout phase:
The base is in place: ET awards from a top European OEM and Cadillac, FT awards from a top European OEM, seven export awards from Chinese OEMs, and JV awards at 10 global OEMs. Hesai is also a selected supplier for Mercedes-Benz L3 across multiple platforms in Europe and China, and the reference lidar on Nvidia Hyperion. It has opened an office in Stuttgart and is building a plant in Thailand. Higher ASPs and margins overseas help offset the domestic price war.
④ Robotics and physical AI form the second growth curve:
Hesai positions itself as 'physical-AI infrastructure', spanning see (lidar), understand (Kosmo), and act (actuators). This quarter, robotics-related revenue already exceeded 50% of lidar revenue. A humanoid robot can require 100+ actuators, more than half of BOM cost. If SGI reaches ~RMB 700mn in 2027 and breaks even, the valuation anchor should move higher.
⑤ The 2027 pricing inflection from deflation to 'steady annual declines' may be pulling forward:
We previously expected lidar ASP decline to narrow to ~10% in 2027. With management signaling 2027 ATX price stability, plus ET, multi-lidar, and overseas mix support, pricing may enter a steady -5–10% p.a. decline earlier, as lidar becomes a standardized auto component. However, with price stabilizing while shipments stall and share slips, there is a trade-off between price and share that needs 4Q validation.
From a long-term TAM lens, the ~RMB 14.0bn market cap, or ~RMB 9.0bn ex net cash, does not yet reflect the domestic passenger-car ADAS base (conservatively a RMB 40bn market by 2030). Near-term shipment and earnings concerns look largely priced, while price stabilization, high-end and overseas awards, and robotics optionality provide medium-to-long-term upside.
Please cf. valuation in 'Hesai: Tesla's castoff? Lidar's elegant comeback is underway'.
Risk disclosure and statements: Dolphin Research Disclaimer and General Disclosure
Previous reports:
Hesai deep dives:
'4x Hesai: Why the lidar 'rejected' by Tesla is shining again?'
'Hesai: Tesla's 'castoff'? Lidar's elegant comeback'
Hesai earnings
'Hesai: ASP keeps plunging, how long will the pain last?'
'Hesai: soaring 'eyes of autonomy', can it take off again?'
'Hesai: chased by RoboSense, cutting prices to defend the No.1 spot?'
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.