


ATAT: Retail as lifeline, hotels bleeding; how long can its 'boutique-chic' image hold up?


On Nov 10, 2026 Beijing time, ahead of the U.S. open, Atour (ATAT) released its Q3 2026 results. Overall revenue beat estimates, and the company raised full-year revenue guidance from +30% to +33%-35%. On profits, ex-SBC results also came in ahead of expectations, but the weak same-store trend, coupled with a large SBC charge, led to a slight YoY decline in GAAP net income. $Atour(ATAT.US)
Key takeaways are as follows:
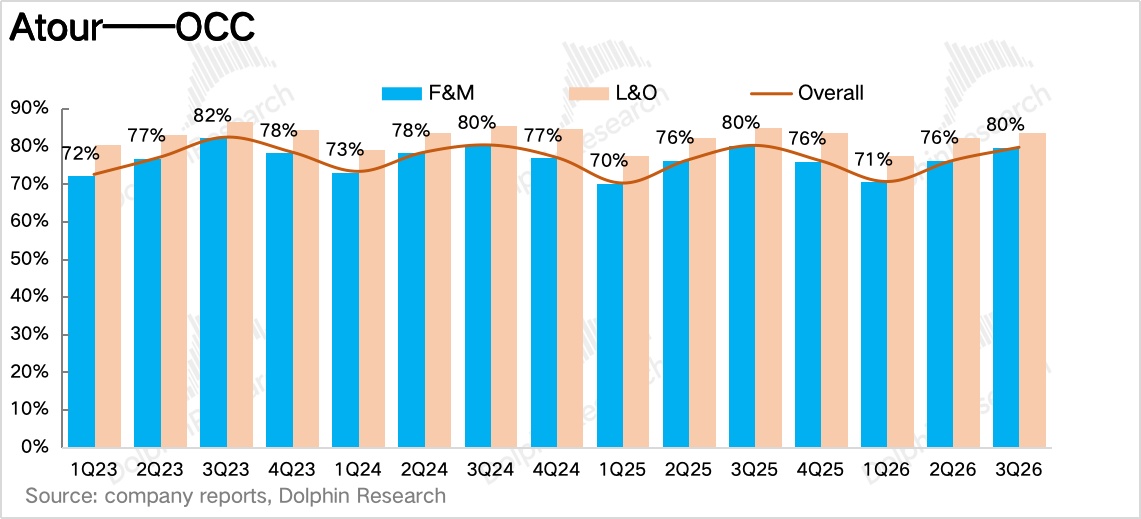
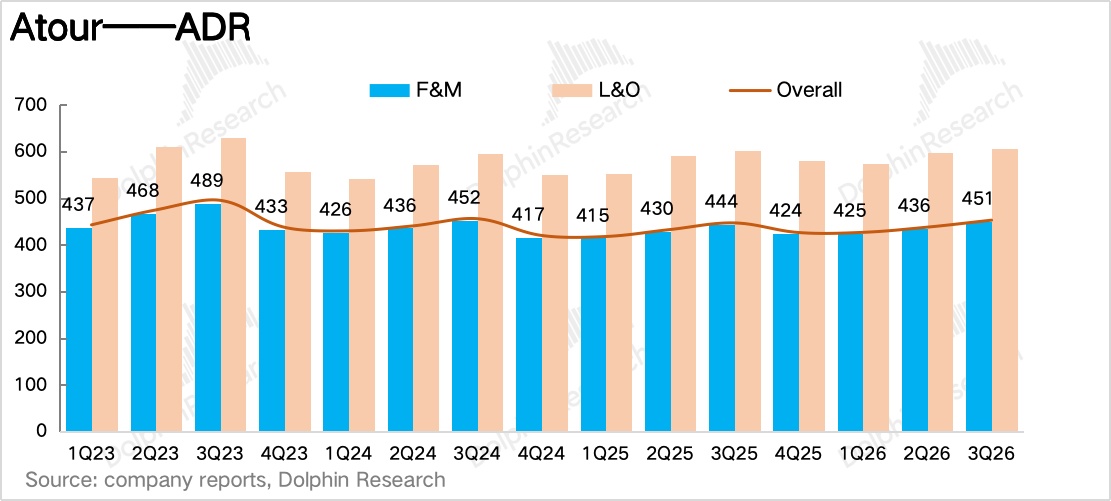
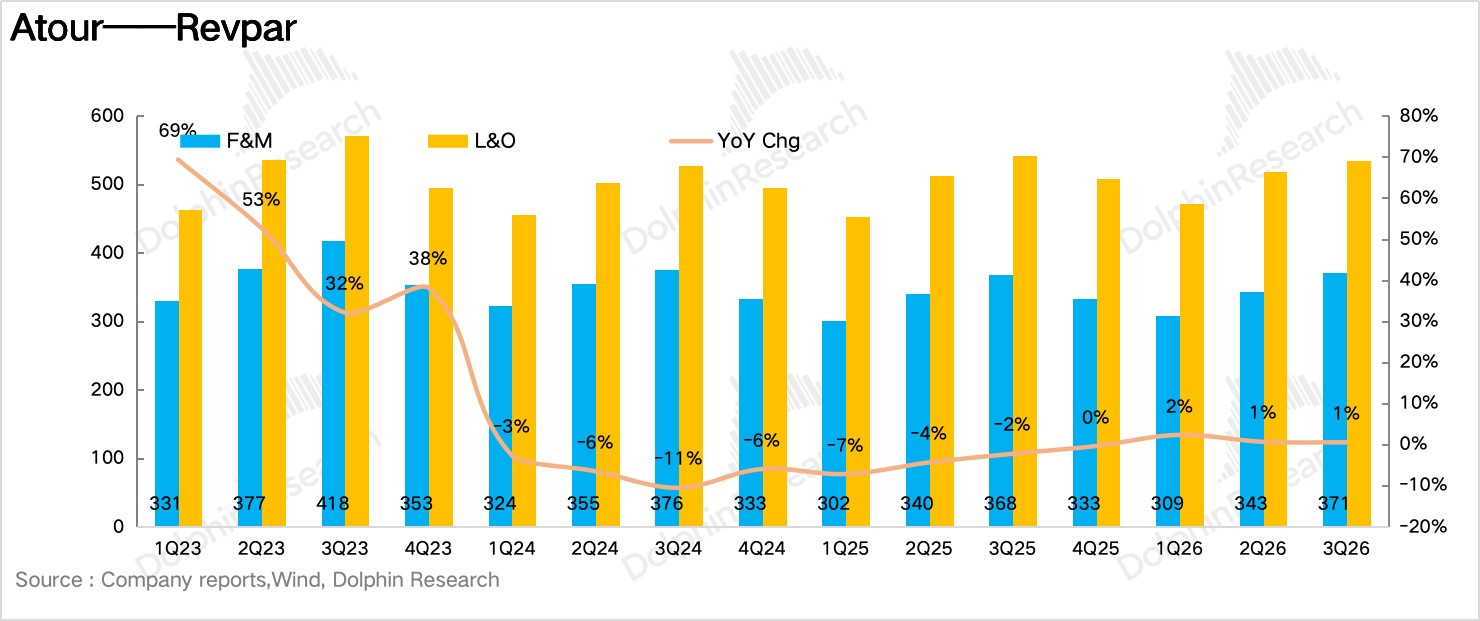
1) RevPAR barely positive; same-store weakness persists. RevPAR came in at RMB 373/night in Q3, up 0.5% YoY, just holding positive growth. ADR rose 1.3% YoY, while OCC fell 50bps YoY. Importantly, same-store performance deteriorated further, with same-store RevPAR down 4.2% YoY, widening vs. Q2, and both price and volume down. The blended RevPAR staying positive was driven by new hotels.
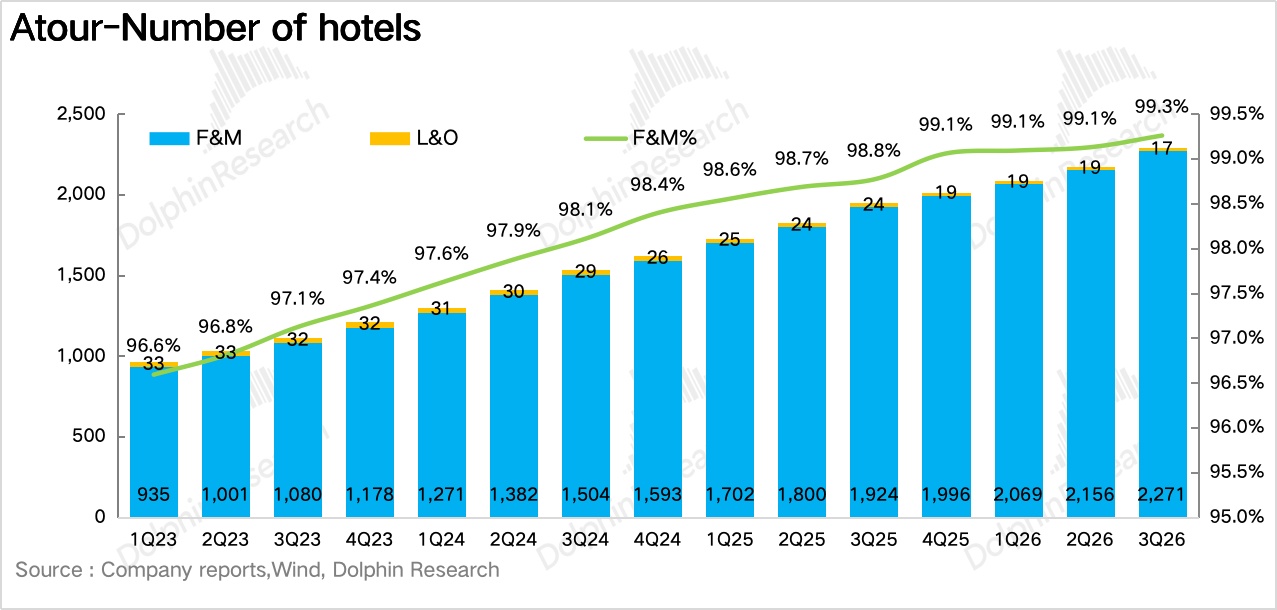
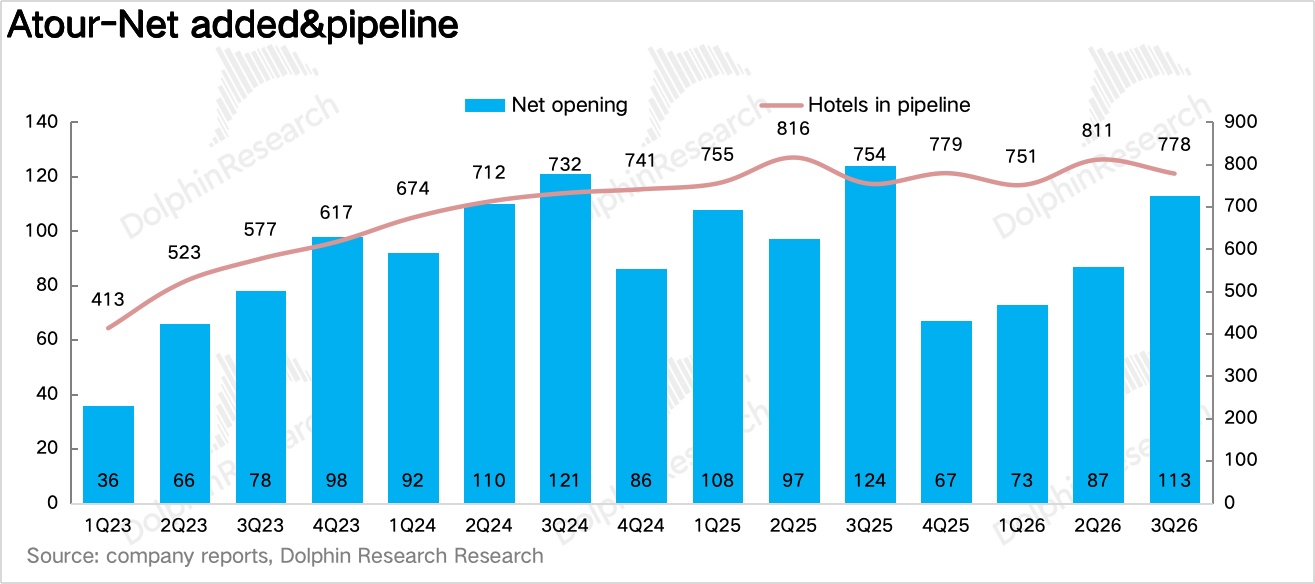
2) Openings on plan, but signings slowed materially. Atour opened 128 hotels and closed 15 in Q3, for a net add of 113, roughly flat YoY, ending the quarter with 2,288 operating hotels. By brand, the core Atour brand remained the main growth driver, and the Light Residence format accelerated expansion. However, the pipeline shrank to 778 from 811 in Q2; a rough read implies only ~95 new contract signings in the quarter, clearly below Q2. Dolphin Research believes the ongoing same-store decline is starting to weigh on franchisees' payback expectations.
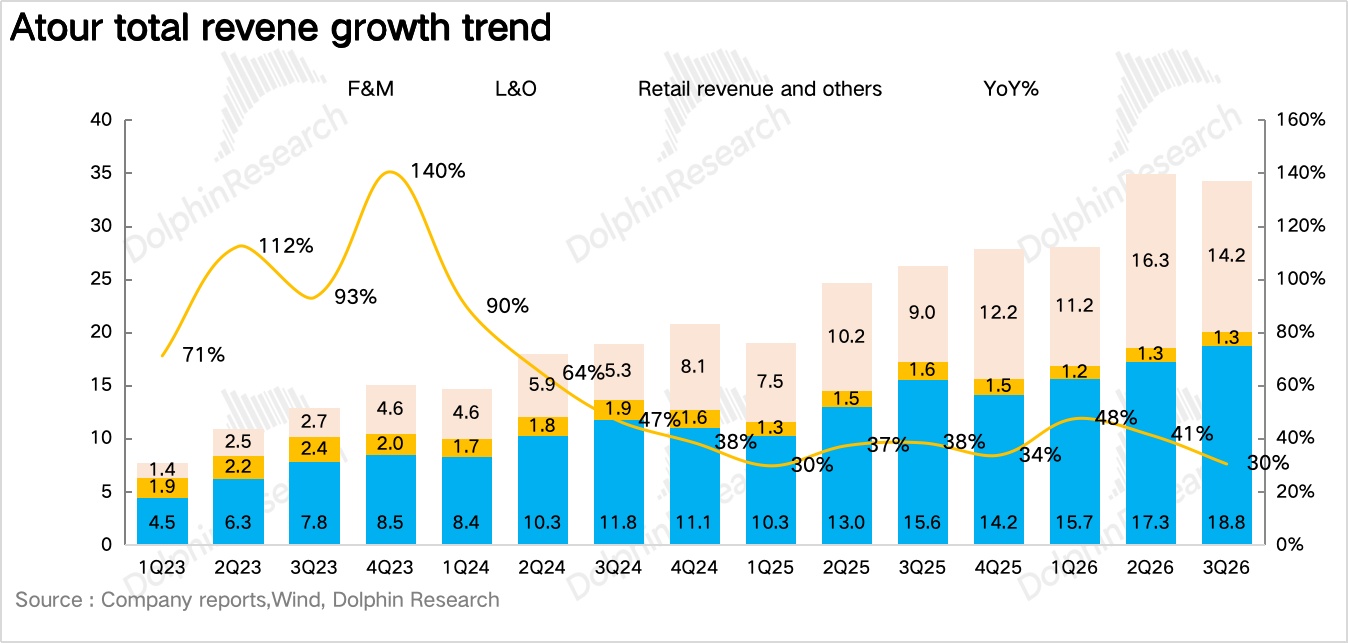
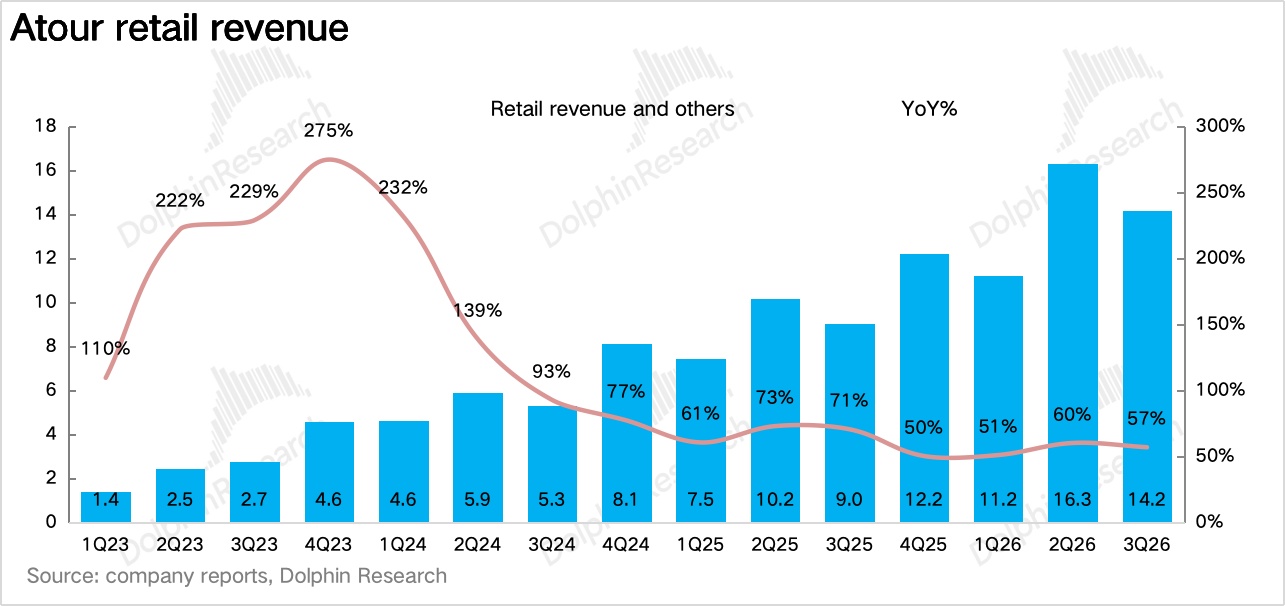
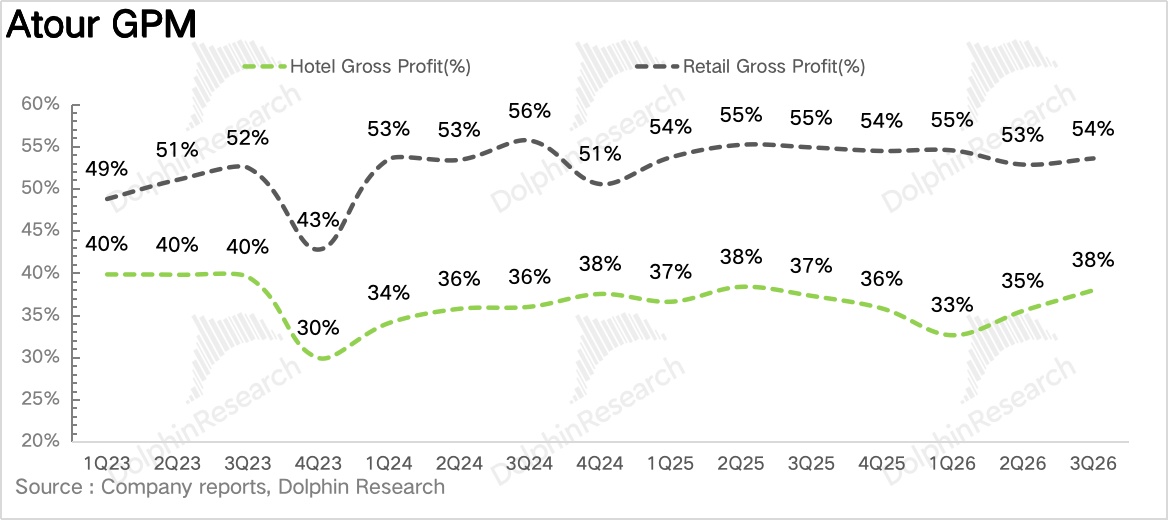
3) Retail biz. continued to grow fast. Benefiting from stronger brand awareness and category expansion, retail revenue reached RMB 1.36 bn, up 61% YoY, broadly in line with Q2. The retail mix rose to roughly 40% of revenue from 32% a year ago. More importantly, retail GPM recovered to 52.1% in Q3, with the YoY decline narrowing to 60bps from 190bps, easing prior concerns that Atour Planet had been dragged into a home-textile price war.
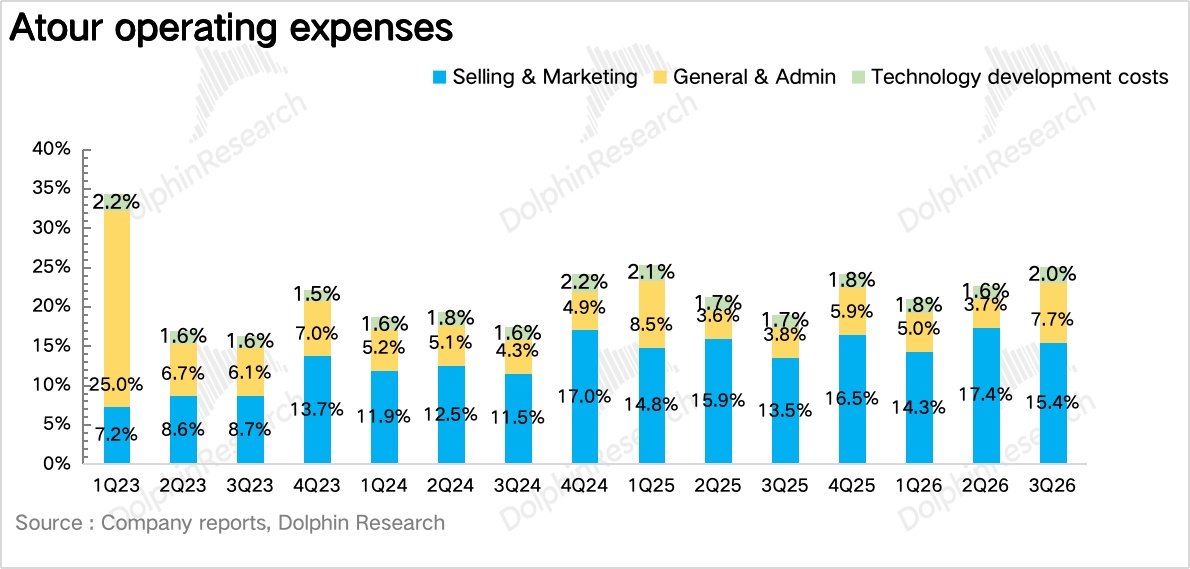
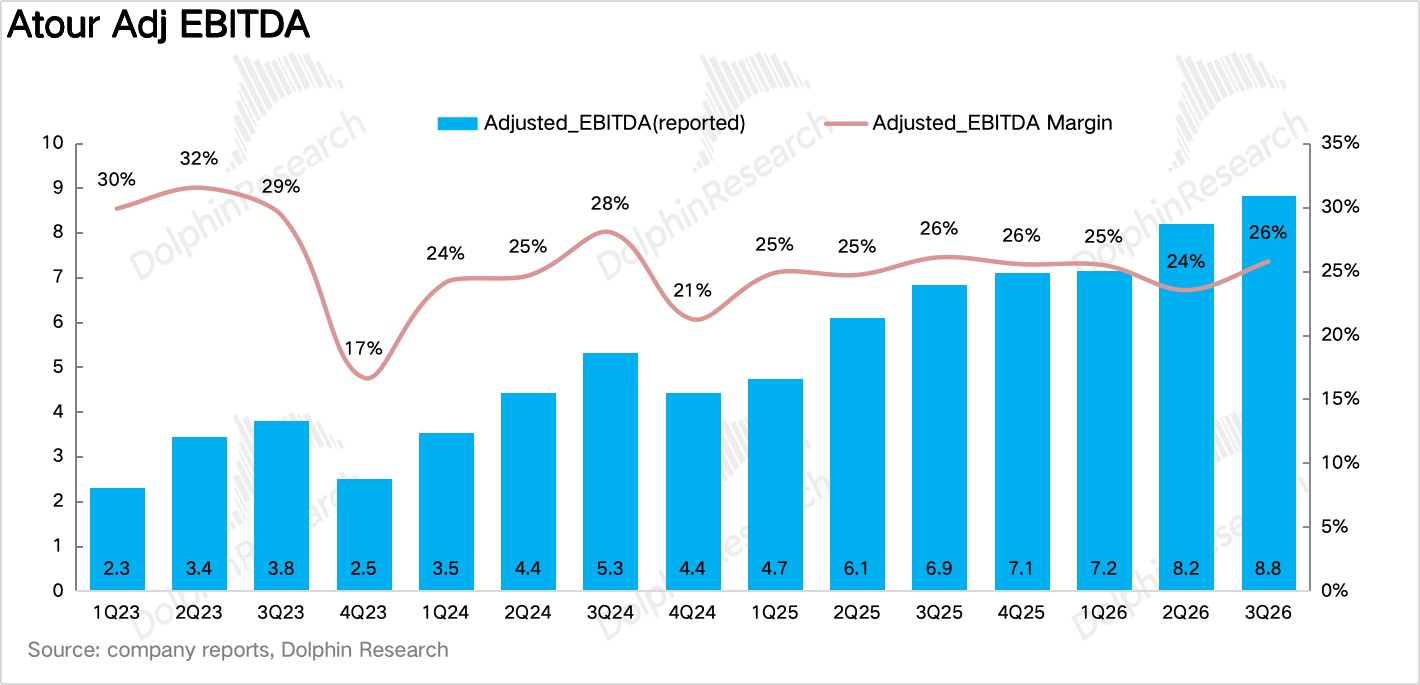
4) GPM improved, but SBC weighed on GAAP earnings. A higher mix of retail, which carries higher GPM, plus better hotel margins lifted total GPM by 110bps YoY to 44.4%. On opex, the selling expense ratio rose 190bps YoY to 15.4% but eased vs. Q2. The real drag was SBC: quarterly SBC expense jumped to RMB 167 mn (vs. RMB 13 mn a year ago), and this item is non-deductible for tax, pushing up the effective tax rate and resulting in a 5.5% YoY decline in GAAP net income. Ex-SBC, adj. net income was RMB 620 mn, up 26% YoY, beating market expectations.
5) Guidance raised; shareholder returns stepped up. The company lifted full-year revenue guidance to +33%-35%. On this basis, Q4 revenue growth implies ~18%-25%, a notable slowdown vs. Q3's +30.5%. On capital returns, the company announced a second cash dividend of about $69 mn this year, bringing total dividends to about $140 mn. Including RMB 820 mn of buybacks in the first three quarters, total shareholder returns are about 5.5% of the current market cap.
6) Financials at a glance
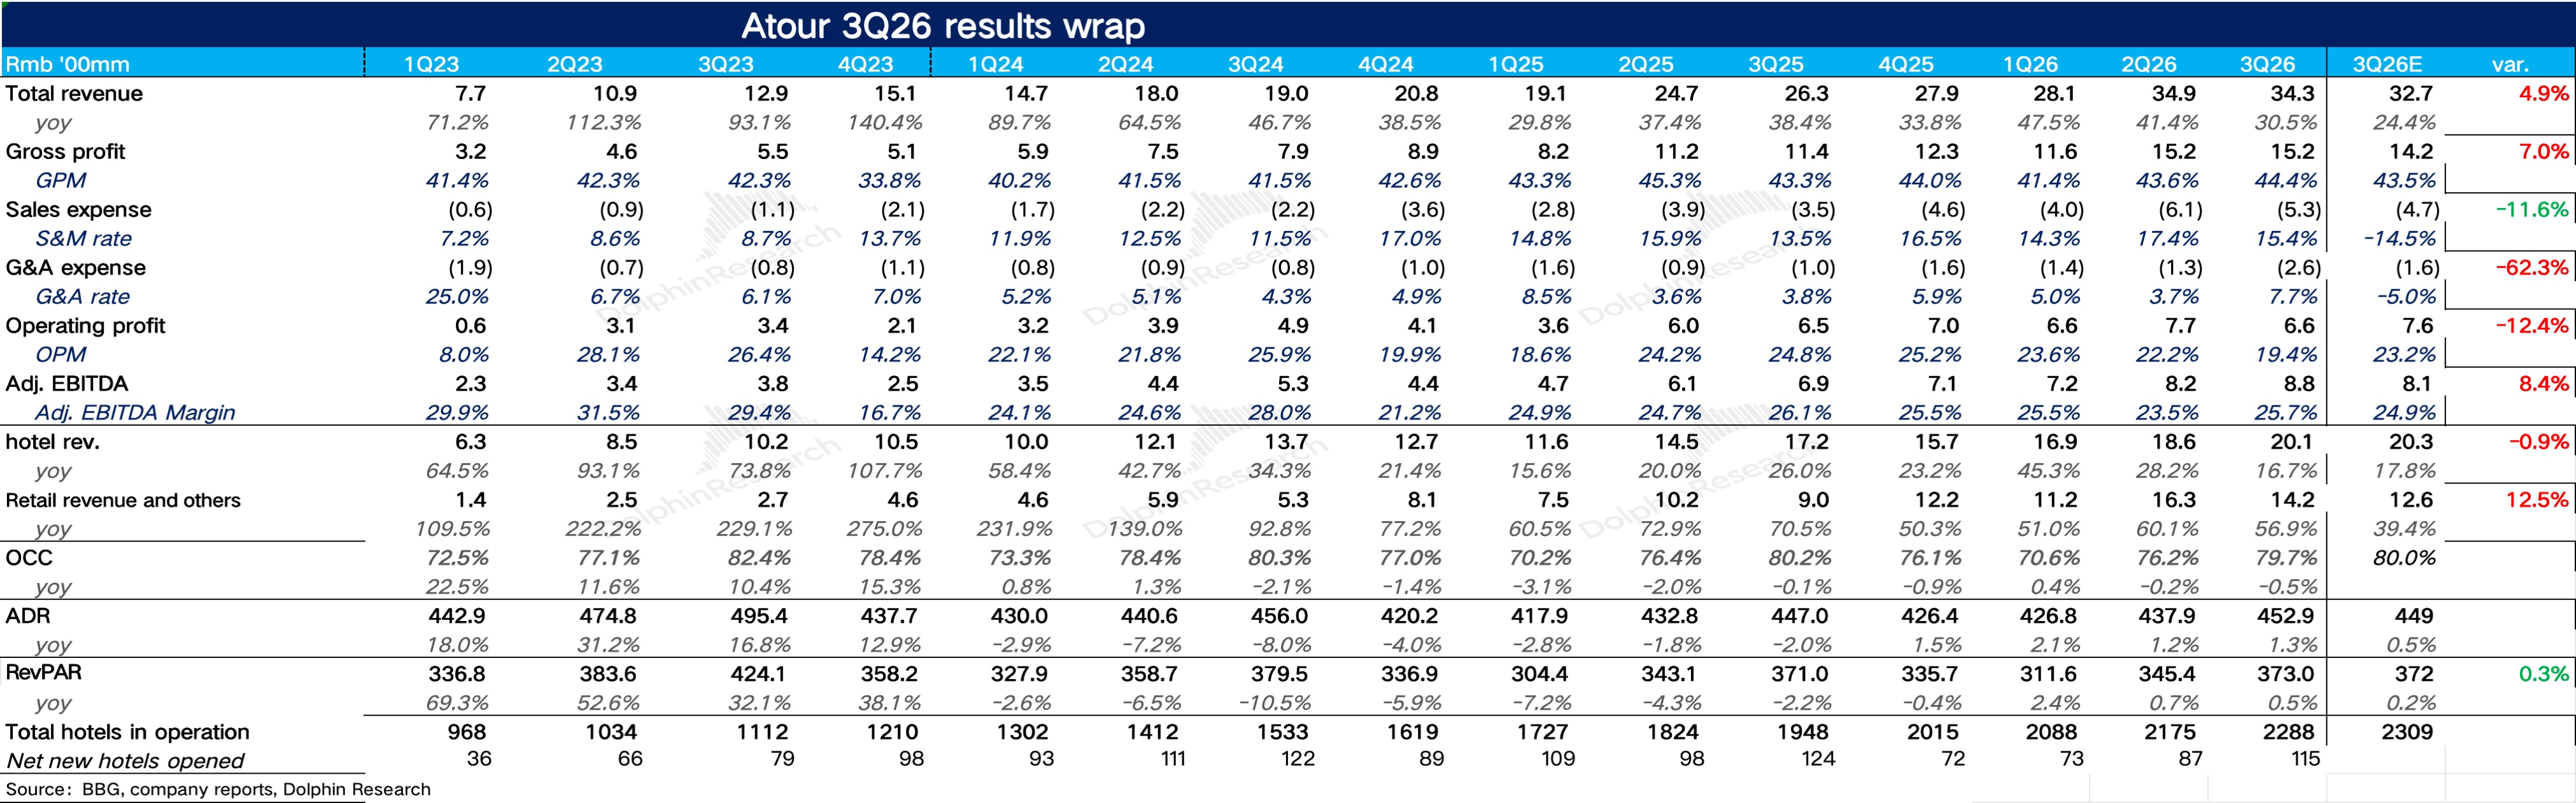
Dolphin Research: overall view
For retail, in our Q2 review we highlighted the key concern that GPM fell from 54.5% in Q1 to 51.4%, alongside lower ASPs for pillows and duvets and a jump in selling expenses, suggesting Atour Planet may have been pulled into a home-textile price war in pursuit of scale. In Q3, retail maintained high growth while GPM recovered to 52.1%, and the selling expense ratio fell notably vs. Q2. This indicates demand is real rather than purely driven by discounting and paid traffic, which is a positive.
If in Q4, during Singles' Day and the seasonal peak for quilts (the year's heaviest promo period), Atour can hold its GPM and keep the selling expense ratio from rising meaningfully, then it will truly validate Atour Planet's ability to defend pricing in major promos, cementing brand strength.
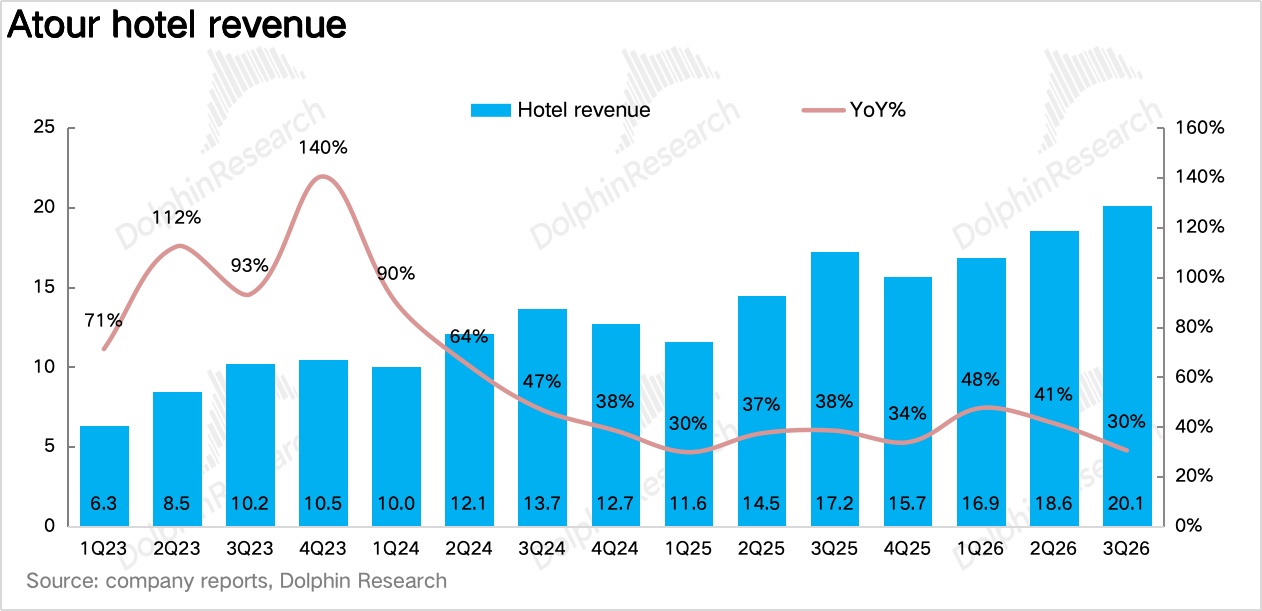
For hotels, while the direct profit impact from same-store declines is limited, the key risk in our view is the indirect effect: sustained same-store weakness may undermine franchisees' payback expectations. Store openings are the core growth driver for Atour's hotel biz., and blended RevPAR staying positive relies on new openings. If slower signings persist, 2027 opening cadence will likely be affected, and blended RevPAR could turn negative.
On guidance, full-year revenue growth was raised from +30% to +33%-35%, but the first three quarters already grew 39%. The midpoint implies Q4 growth of about +22%, clearly slower than Q3's +30.5%. Assuming hotel growth of ~15% in Q4, the implied Q4 retail growth is around 30%, also a notable decel. vs. the +60% in the first three quarters.
On SOTP, given the widening decline in same-store RevPAR and clearly slower signings, Dolphin Research lowers the valuation multiple for the hotel segment. Applying 12x to 2026 adj. hotel EBITDA of RMB 2.2 bn yields roughly RMB 26.4 bn; adding RMB 3.5 bn net cash, hotel value totals about RMB 30 bn. For retail, we keep prior assumptions: 2029 revenue of ~RMB 10.7 bn and a 6% net margin, implying net income of ~RMB 640 mn at 15x, discounted back to 2026 at 11% WACC, for about RMB 7 bn. Combined, the SOTP is about RMB 37 bn, implying roughly 14% upside vs. the current level.
In addition, total 2026 shareholder returns, including about $140 mn in dividends and RMB 820 mn of buybacks in the first three quarters, come to roughly RMB 1.8 bn, about 5.5% of the current market cap, providing some support for the stock.
Detailed charts below:
Dolphin Research on 'Atour': past analyses
Reviews:
Aug 21, 2026 'Atour: Buying Growth with Cash Burn — How Long Can the Retail Story Hold?'
May 13, 2026 'Atour: Hotels Rebound, Retail Surges — Is the 'Indie Chic' Hotel Finally Breaking Through?'
Mar 17, 2026 'Atour: Retail Surges — The 'Haidilao' of Hotels Is Smiling Again?'
Deep dives
Jan 13, 2026 'Atour: How the 'Haidilao' of Hotels Was Built'
Mar 4, 2026 'Atour: Fan-building in Hotels, Cash Generation in Retail — How Long Can the 'Indie Chic' Hotel Keep Smiling?'
Risk disclosure and statement: Dolphin Research Disclaimer and General Disclosure
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.