


IREN: Pricing and funding improving, but where is the 2027 backlog?


$IREN(IREN.US) released FY1Q27 results (for quarter ended Sep 2026) pre-mkt on Nov 6 Beijing time. Revenue modestly beat, Adj. EBITDA broadly in line. However, the $4bn ARR go-live was pushed from year-end to Jan 2027, and next quarter opex will step up again. The good news: better pricing, larger client prepayments and clearer financing capacity, but ATM issuance continued with Oct share sales exceeding the entire Sep quarter.
On Nov 5, $IREN(IREN.US) fell 17% alongside AI peers, now ~75% off its 52-week high. The market worries about two things: whether 2027 capacity can be contracted, and whether FY27’s near $20bn CapEx will still rely on equity. How much did this print address?
1) Key takeaways
1. Revenue & ARR: beat on revenue; $4bn ARR delayed by 1–2 months
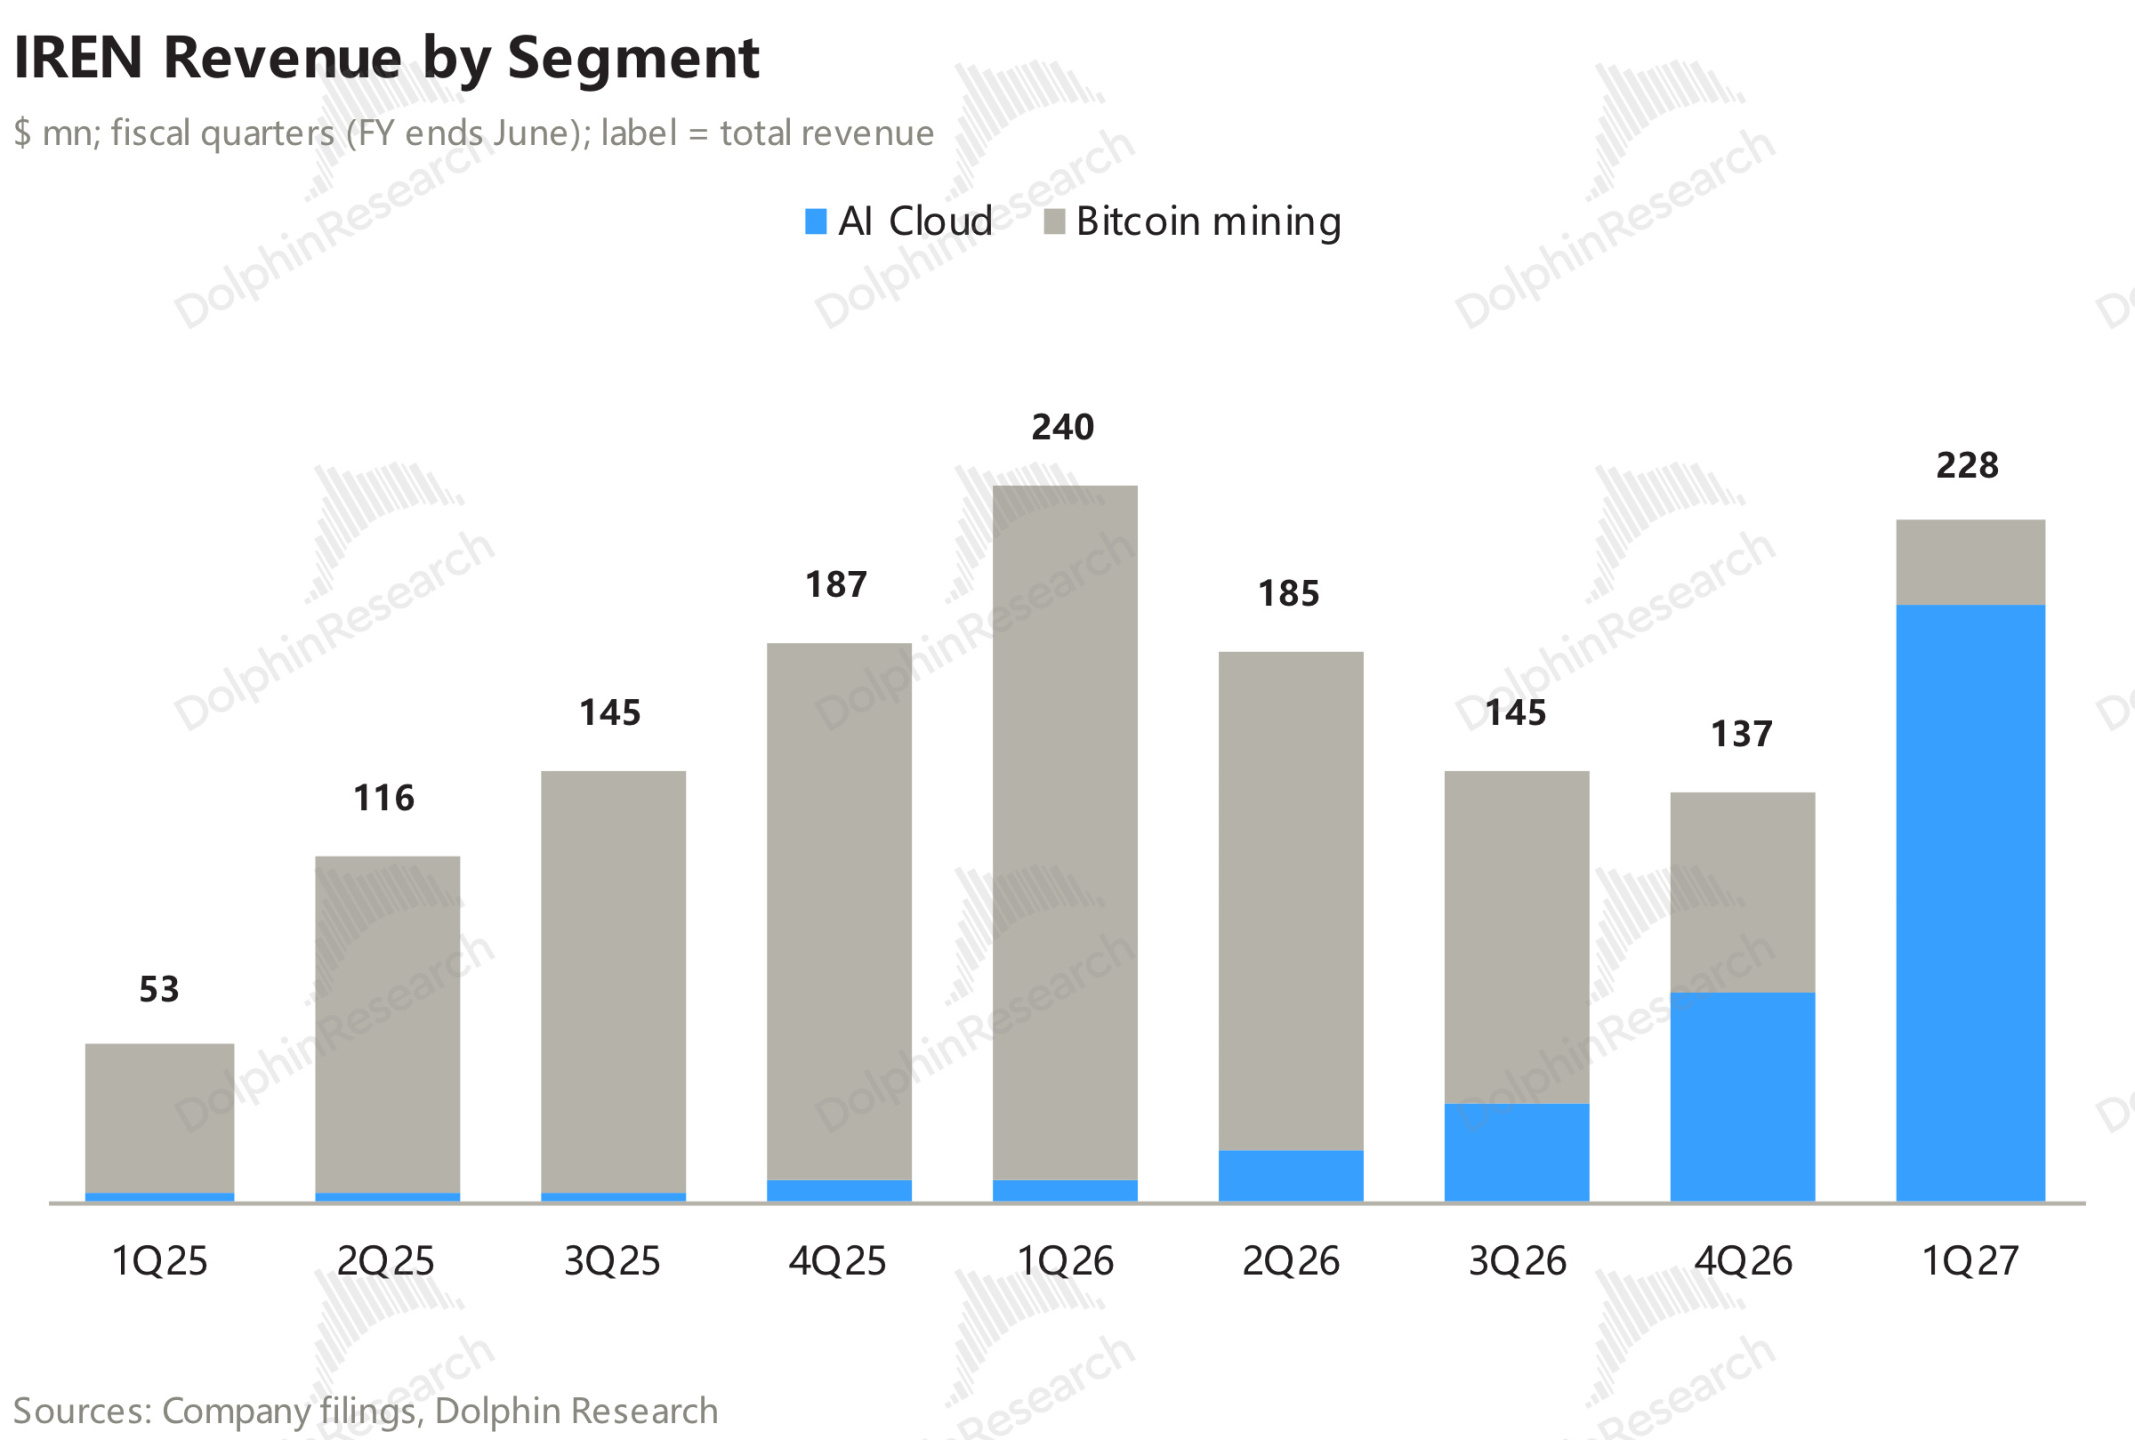
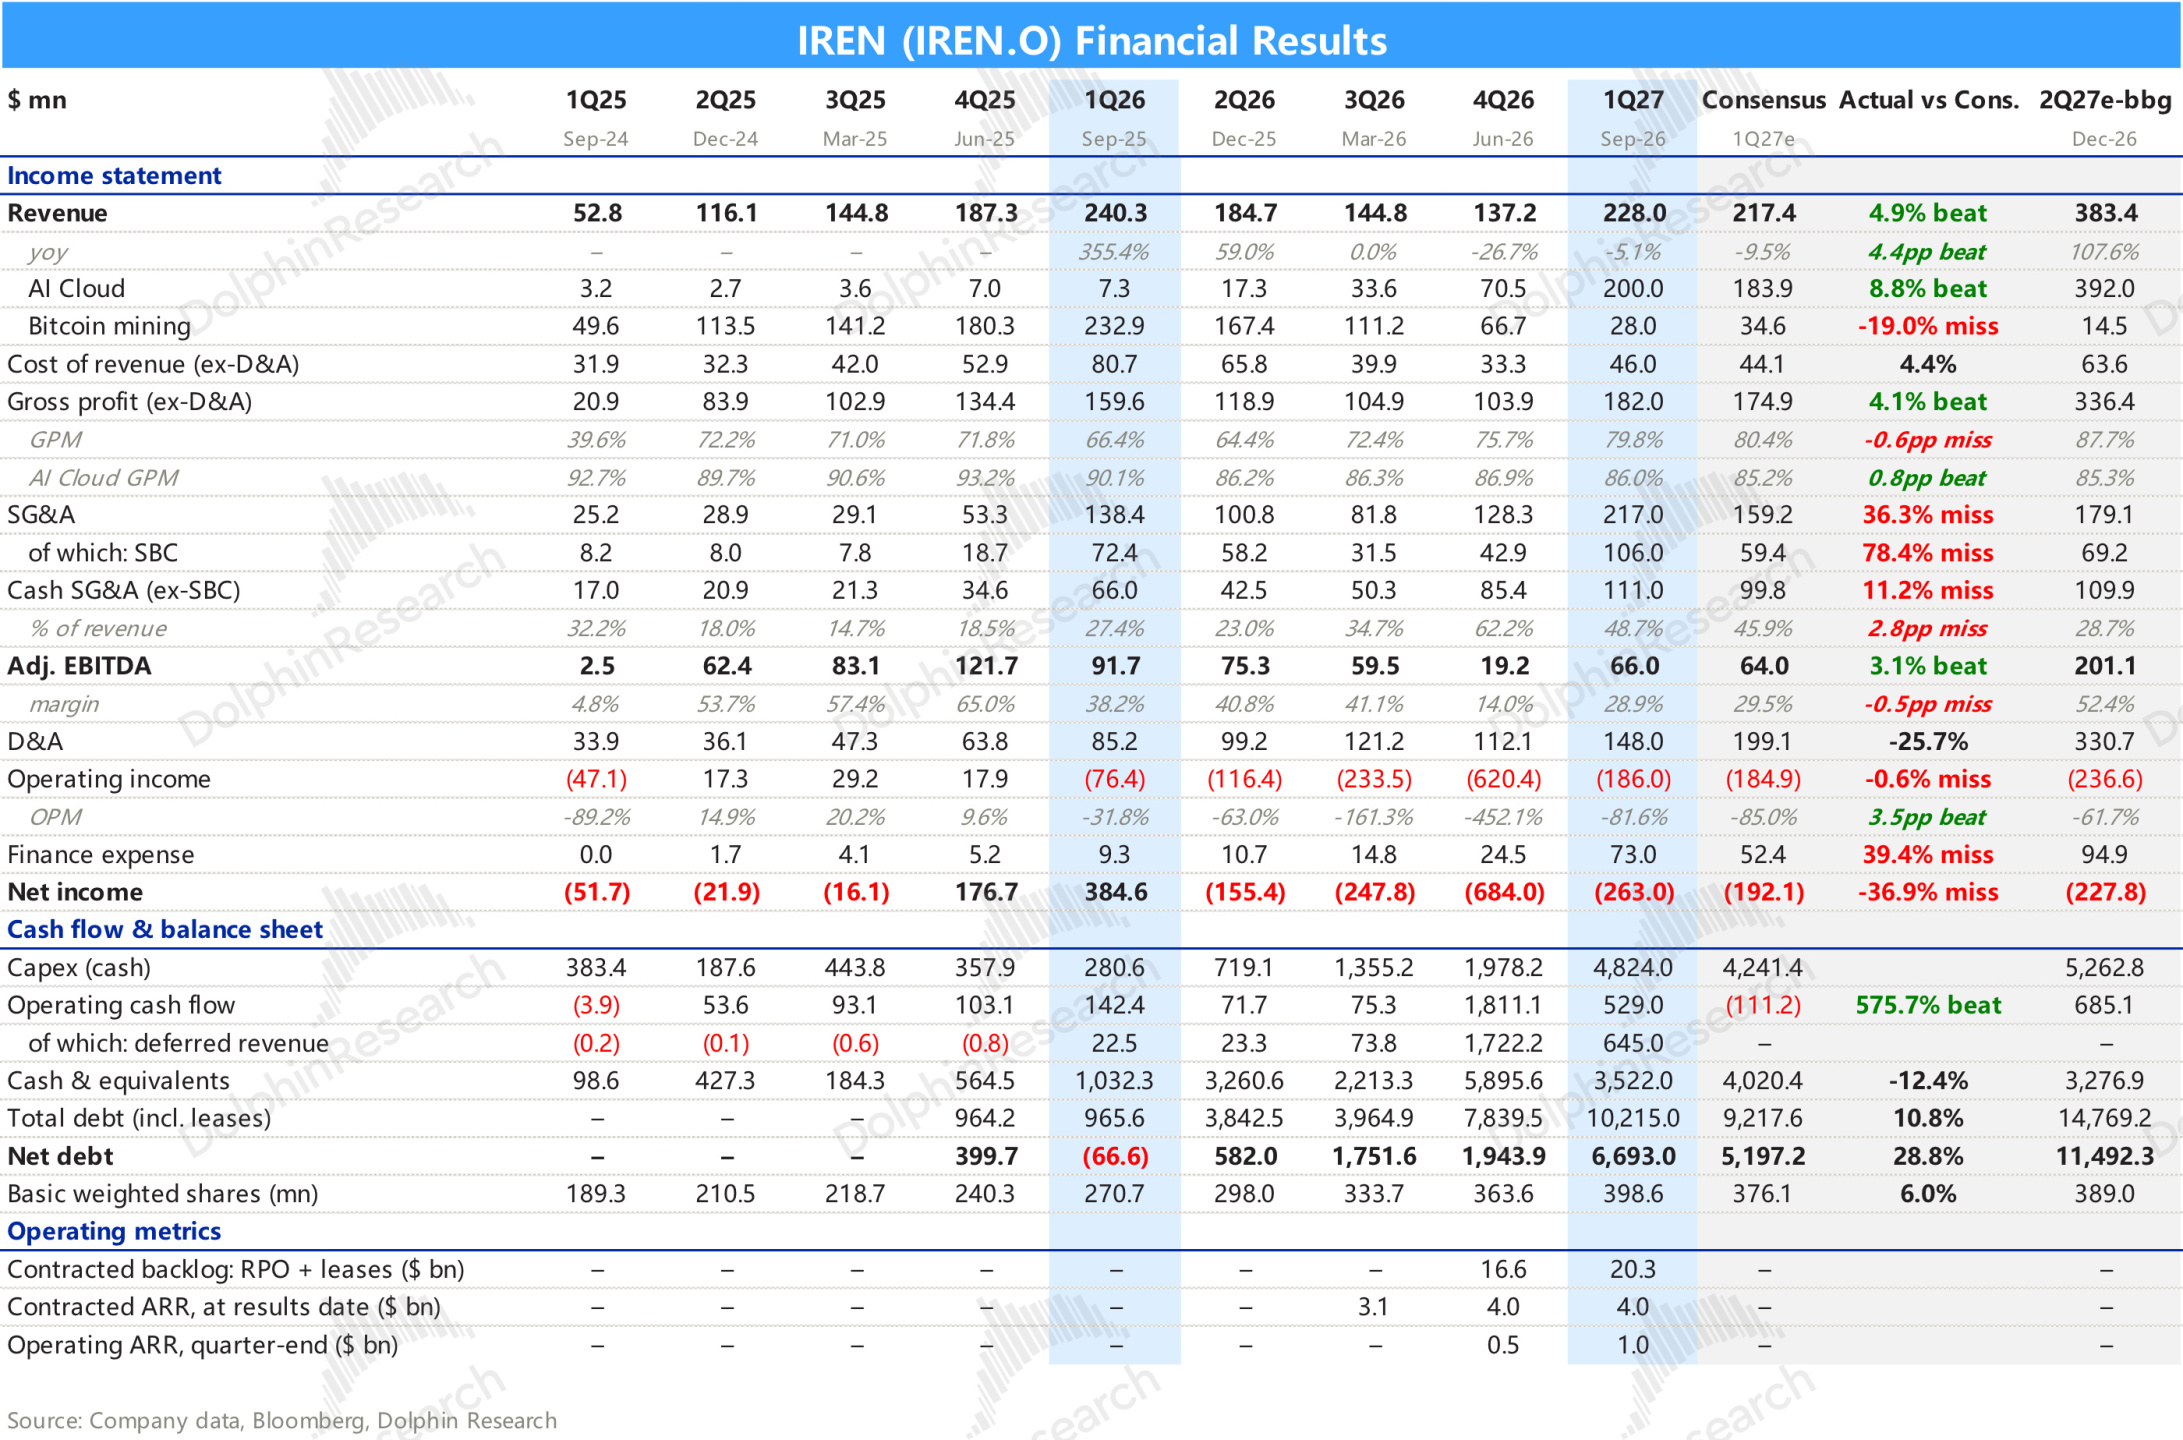
Revenue beat on Horizon 1 delivery and AI Cloud ramp. Total revenue was $228 mn vs. Bloomberg consensus $217 mn, +66% QoQ. AI Cloud was $200 mn (vs. $184 mn est.), +1.8x QoQ; Mining $28 mn, which mgmt expects to largely exit by year-end.
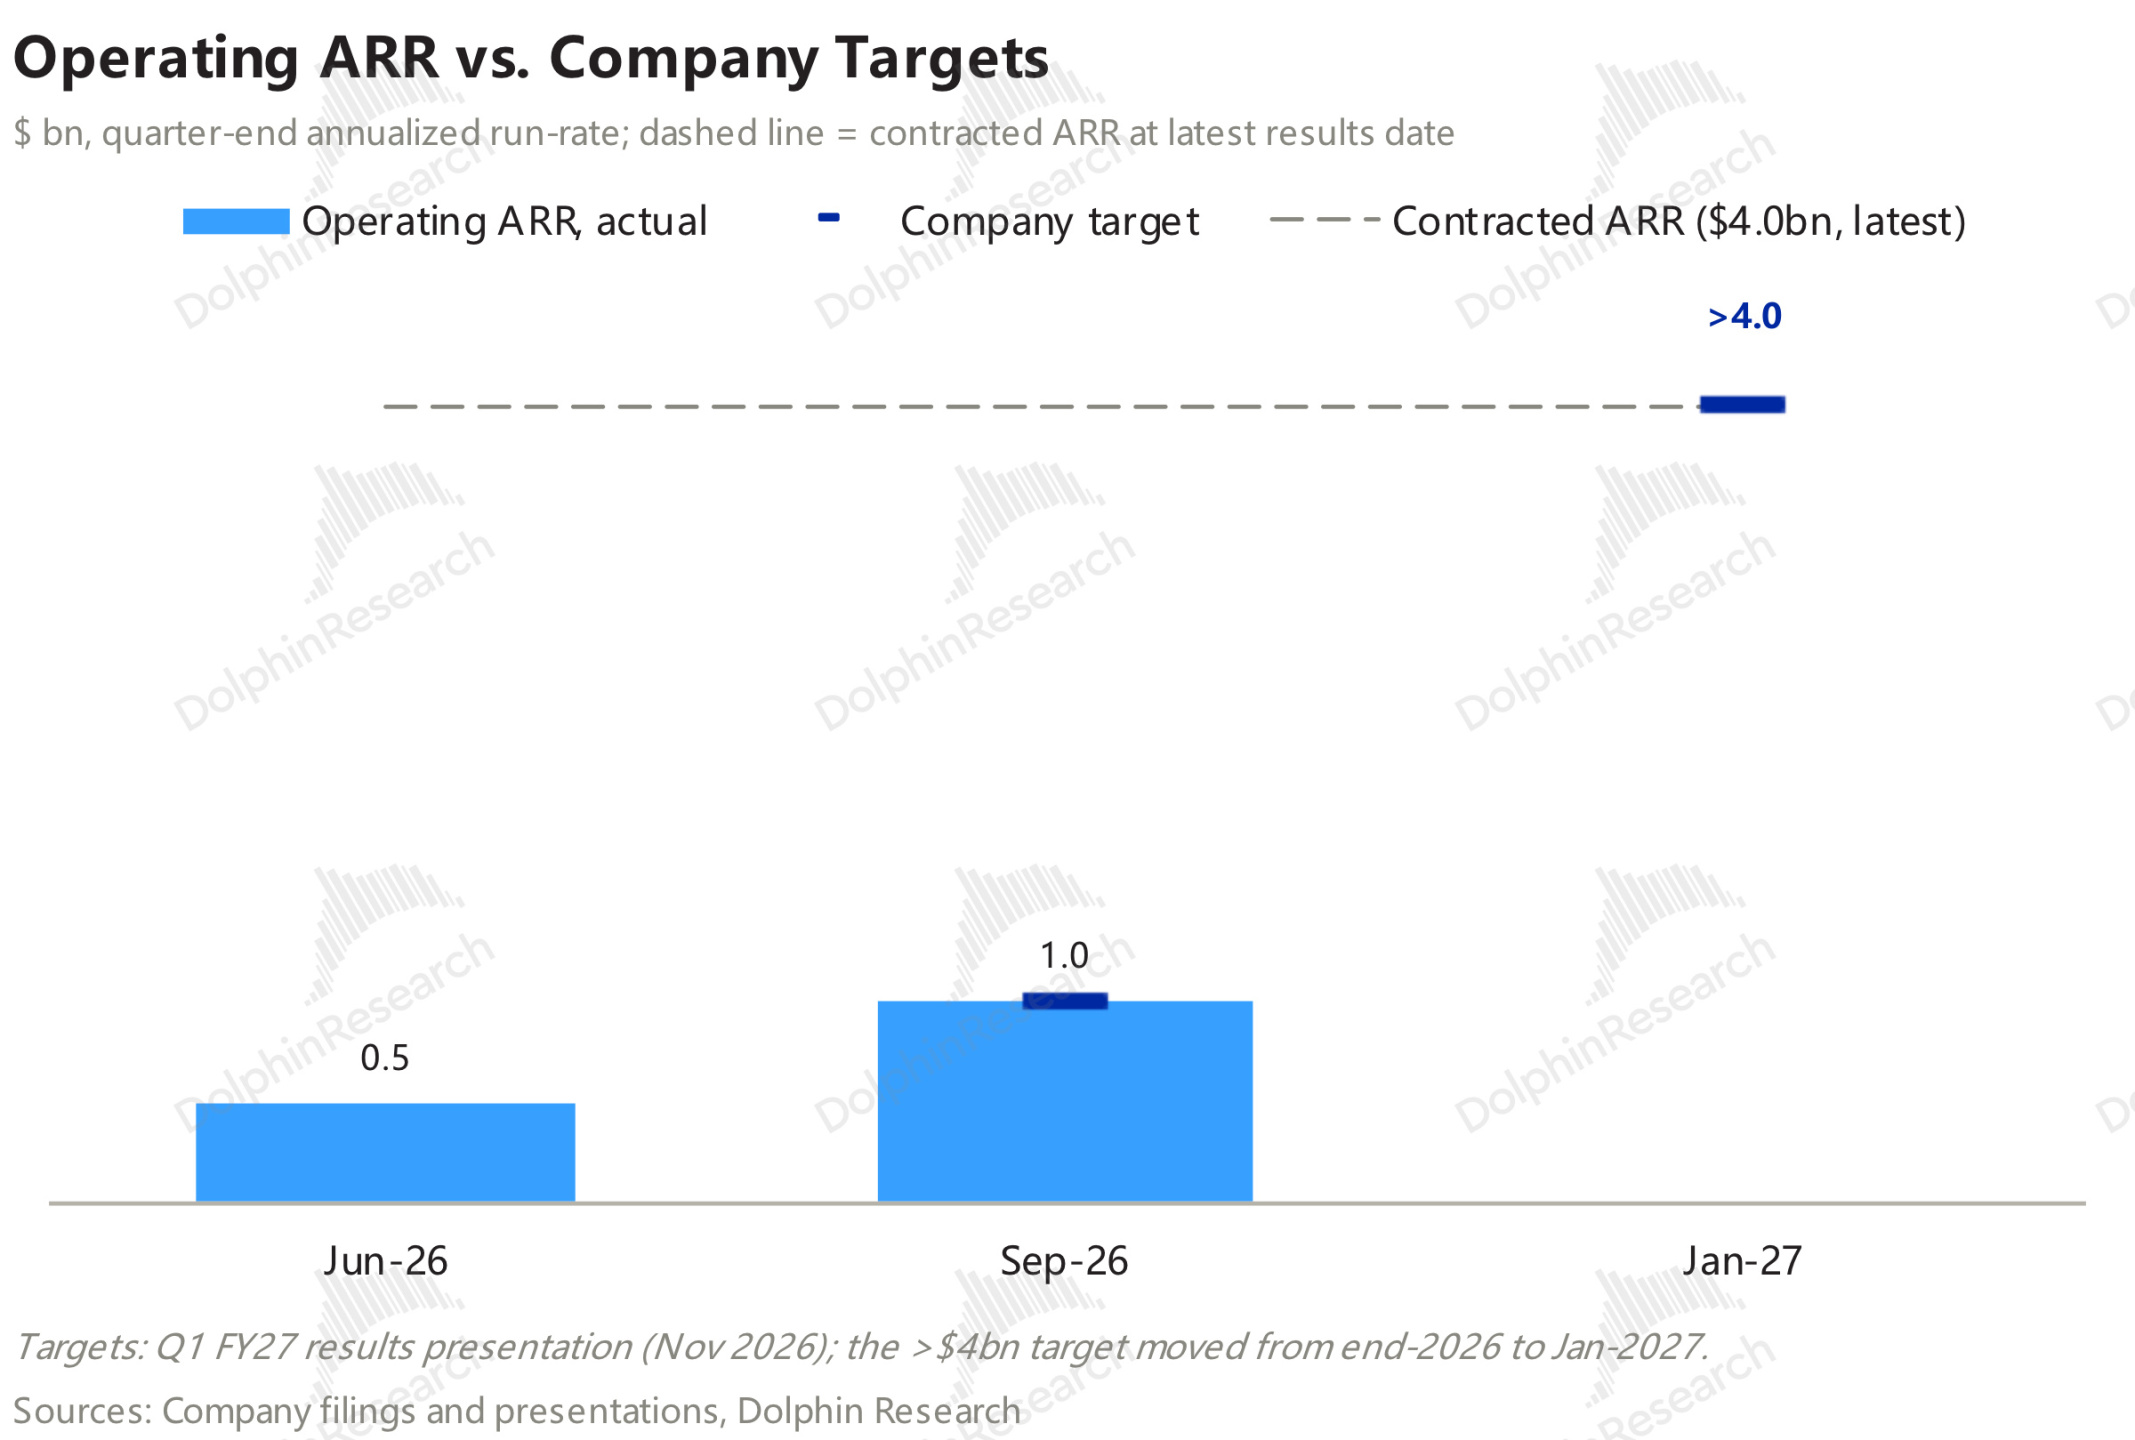
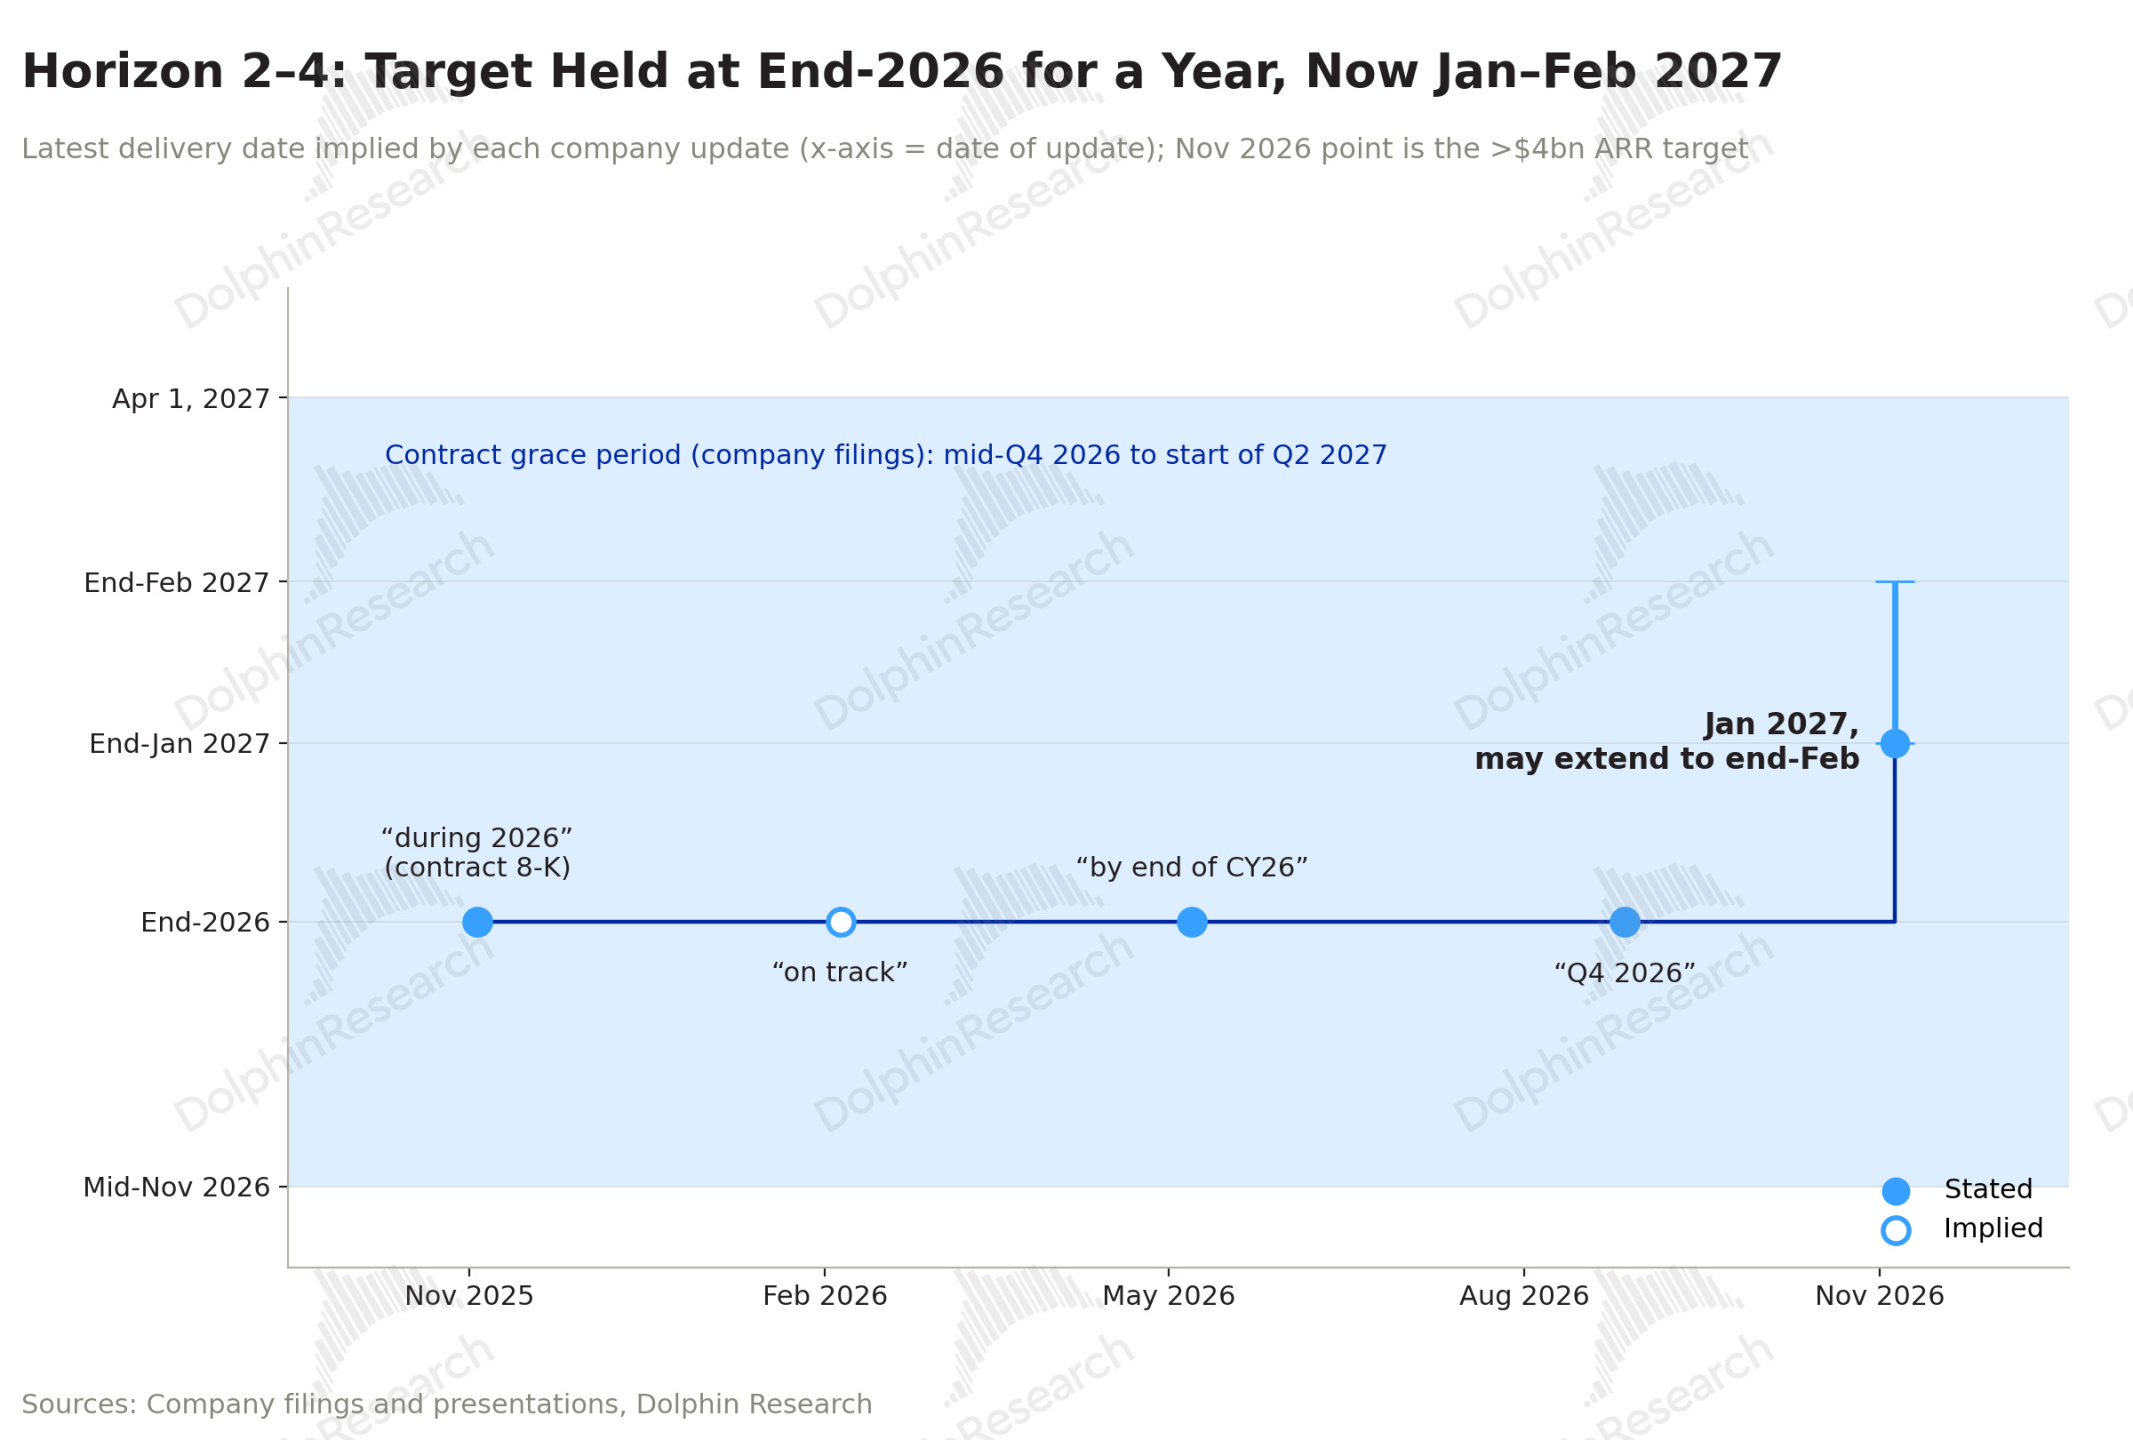
Operating ARR reached $1bn by quarter-end, but showed no growth in Sep. It hit $1bn on Aug 26, while the $4bn target moved from end-2026 to Jan 31, 2027, possibly slipping to late Feb. Reasons included client-requested design changes, supplier timing and third-party delays; Microsoft requested, post-Horizon 1, a 200MW network upgrade to run latest frontier models.
The practical impact is limited. Still within contractual grace, and MS-driven changes extend delivery dates per contract without penalties. Revenue is deferred, not lost: Horizon 2–4 annualized revenue is ~$1.46 bn, with service terms starting at each batch delivery; a one-month slip defers roughly $120 mn.
Operating ARR should exceed $4bn by end-Jan, implying Horizon 1–4 fully online and initial air-cooled capacity at Mackenzie and Childress commissioned. Progress varies across Horizons, with Horizon 4 tightest. H2 is built with Dell commissioning and one integration test remaining; H3 GPUs are fully on site; H4 GPUs arrive in weeks. H1 took ~14 weeks from early-May install to mid-Aug acceptance; on that pace, late Feb is not roomy.
Next quarter revenue to be roughly flat. Mgmt guides Dec-quarter AI Cloud revenue of ~$250 mn, about one-quarter of Sep-end ARR. Bloomberg 2Q27 AI Cloud consensus of $392 mn likely needs a ~one-third cut.
2. Profit: Adj. EBITDA in line; opex step-up not done
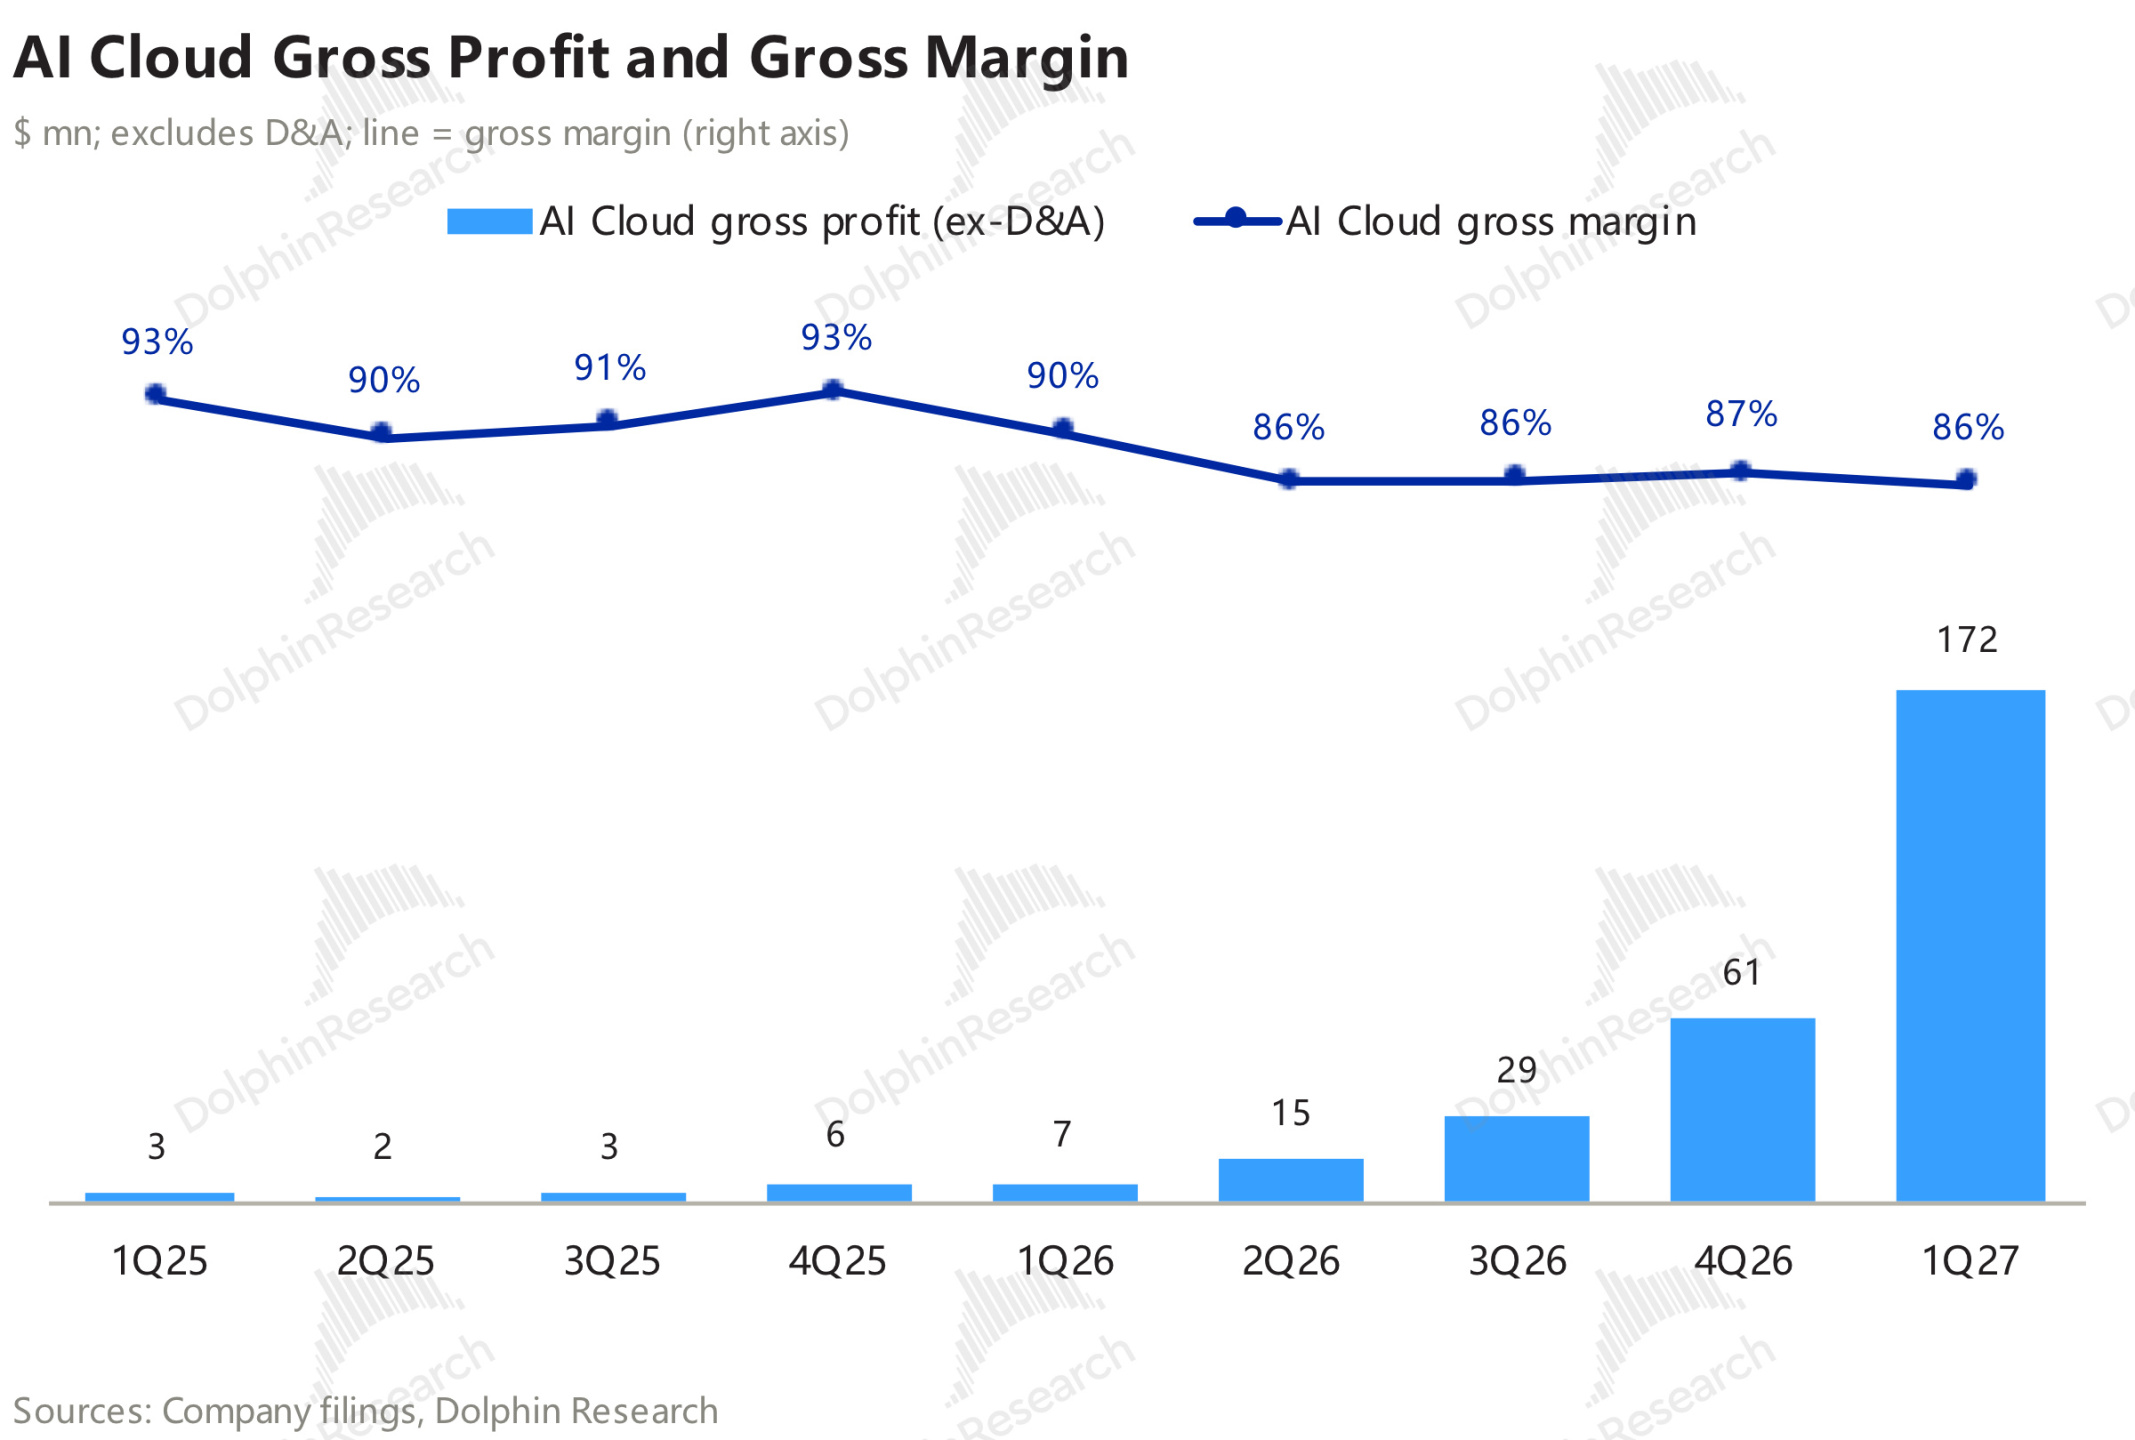
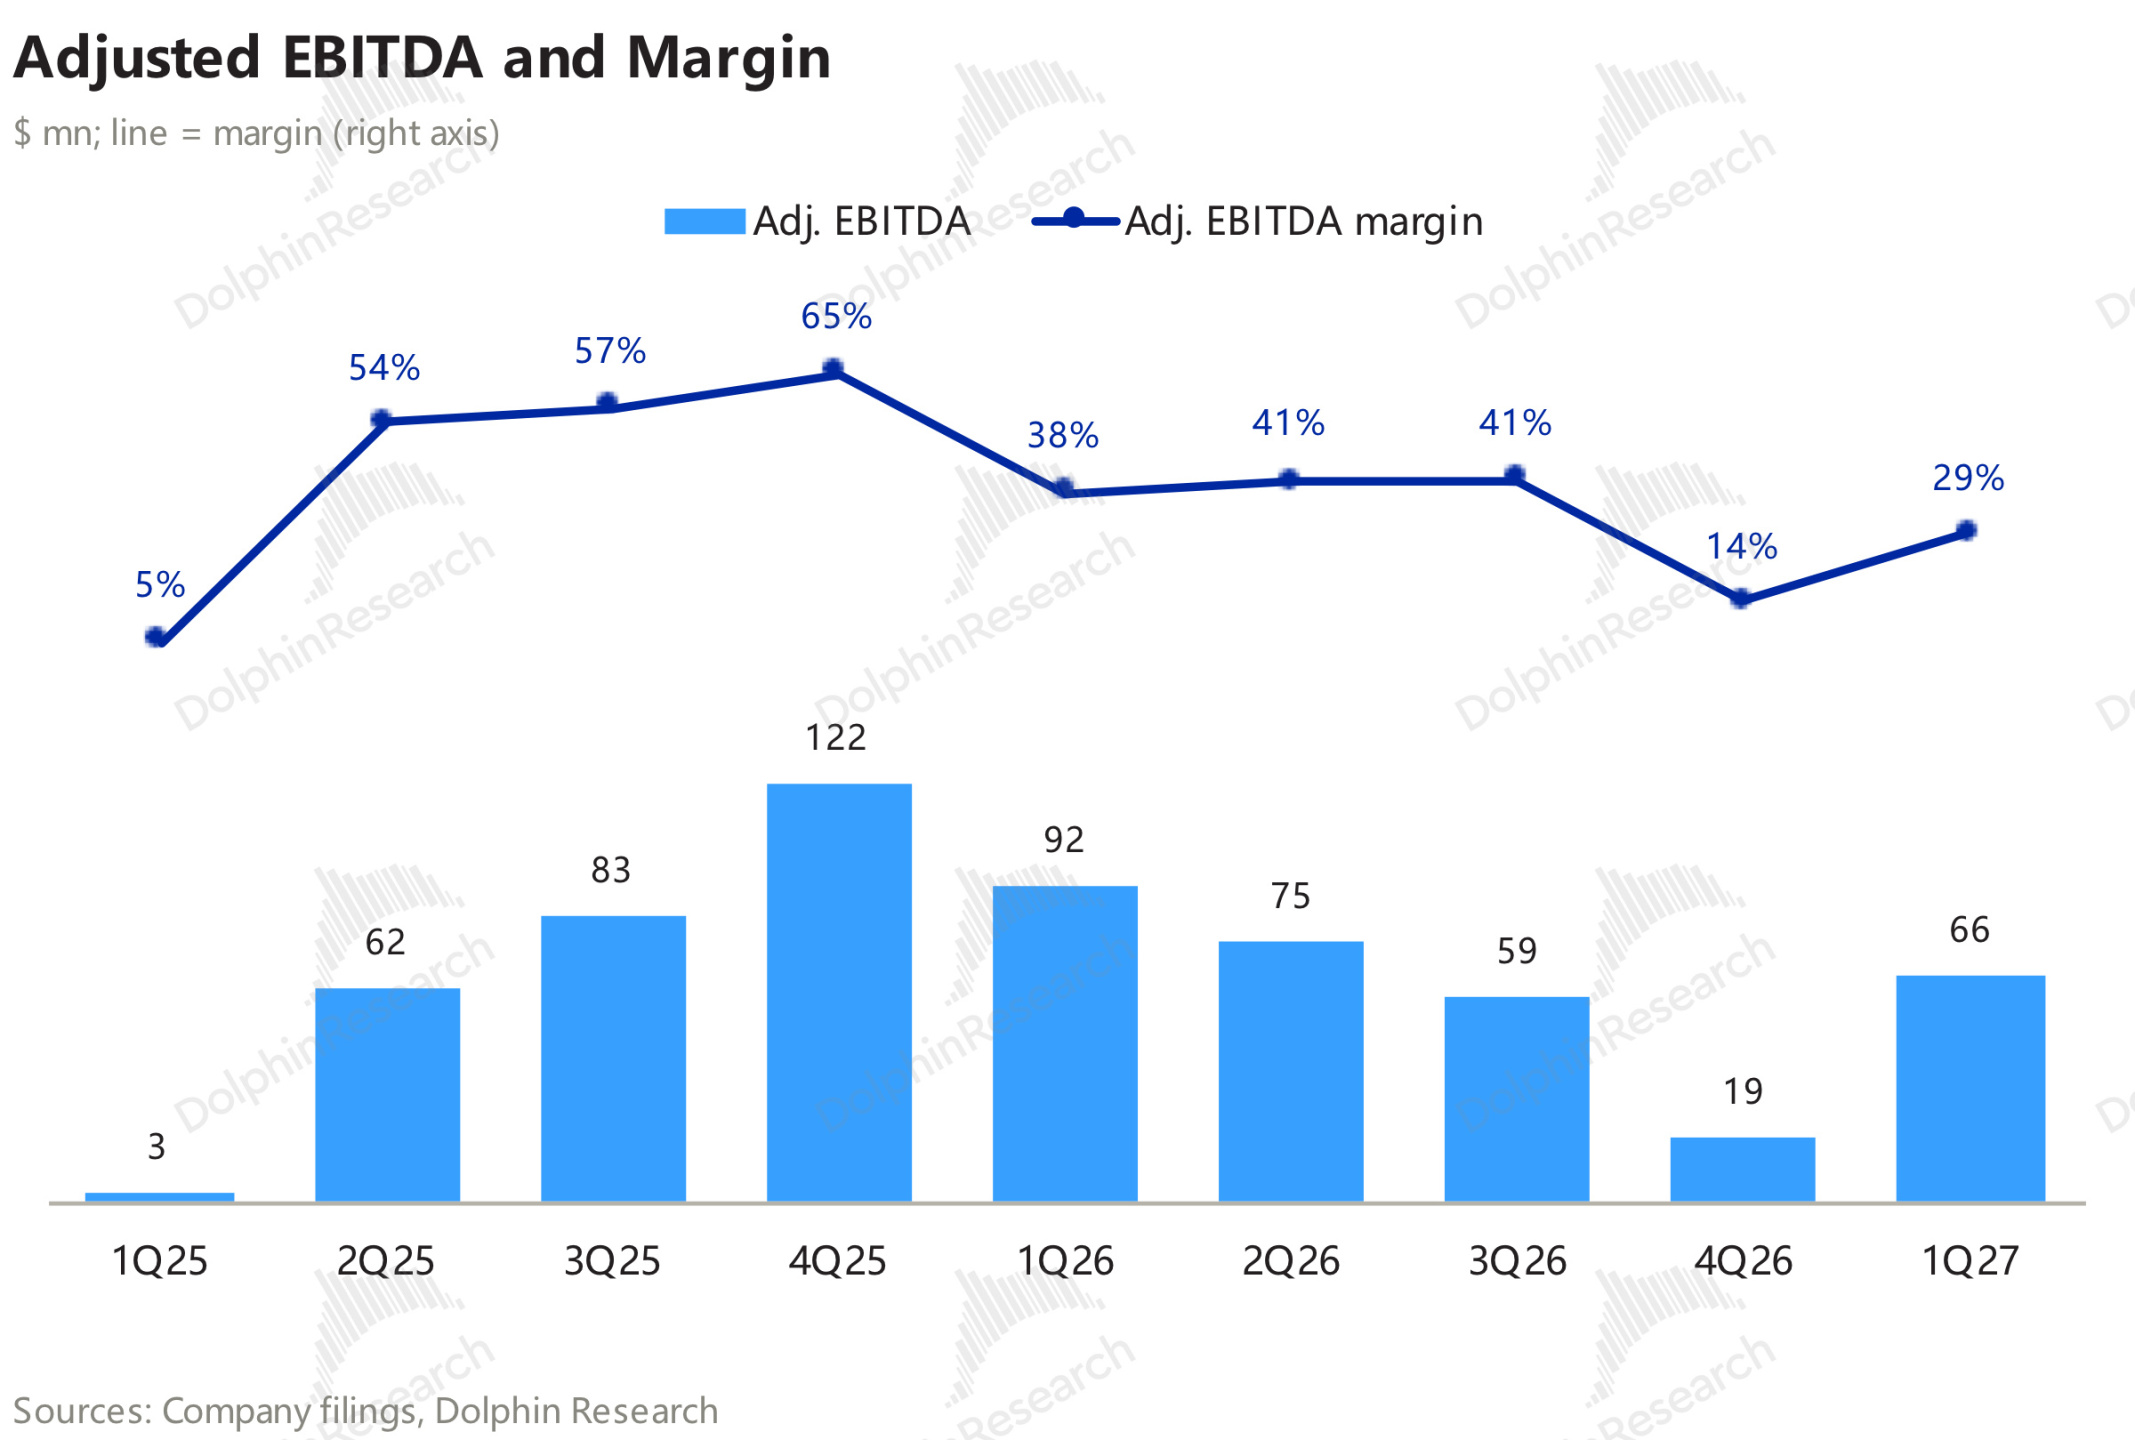
Profit was broadly in line, with pressure shifting to next quarter. Adj. EBITDA was $66 mn (vs. $64 mn est.), margin rose to 29% from 14% last quarter. AI Cloud GPM ex-D&A was 86%, roughly flat QoQ.
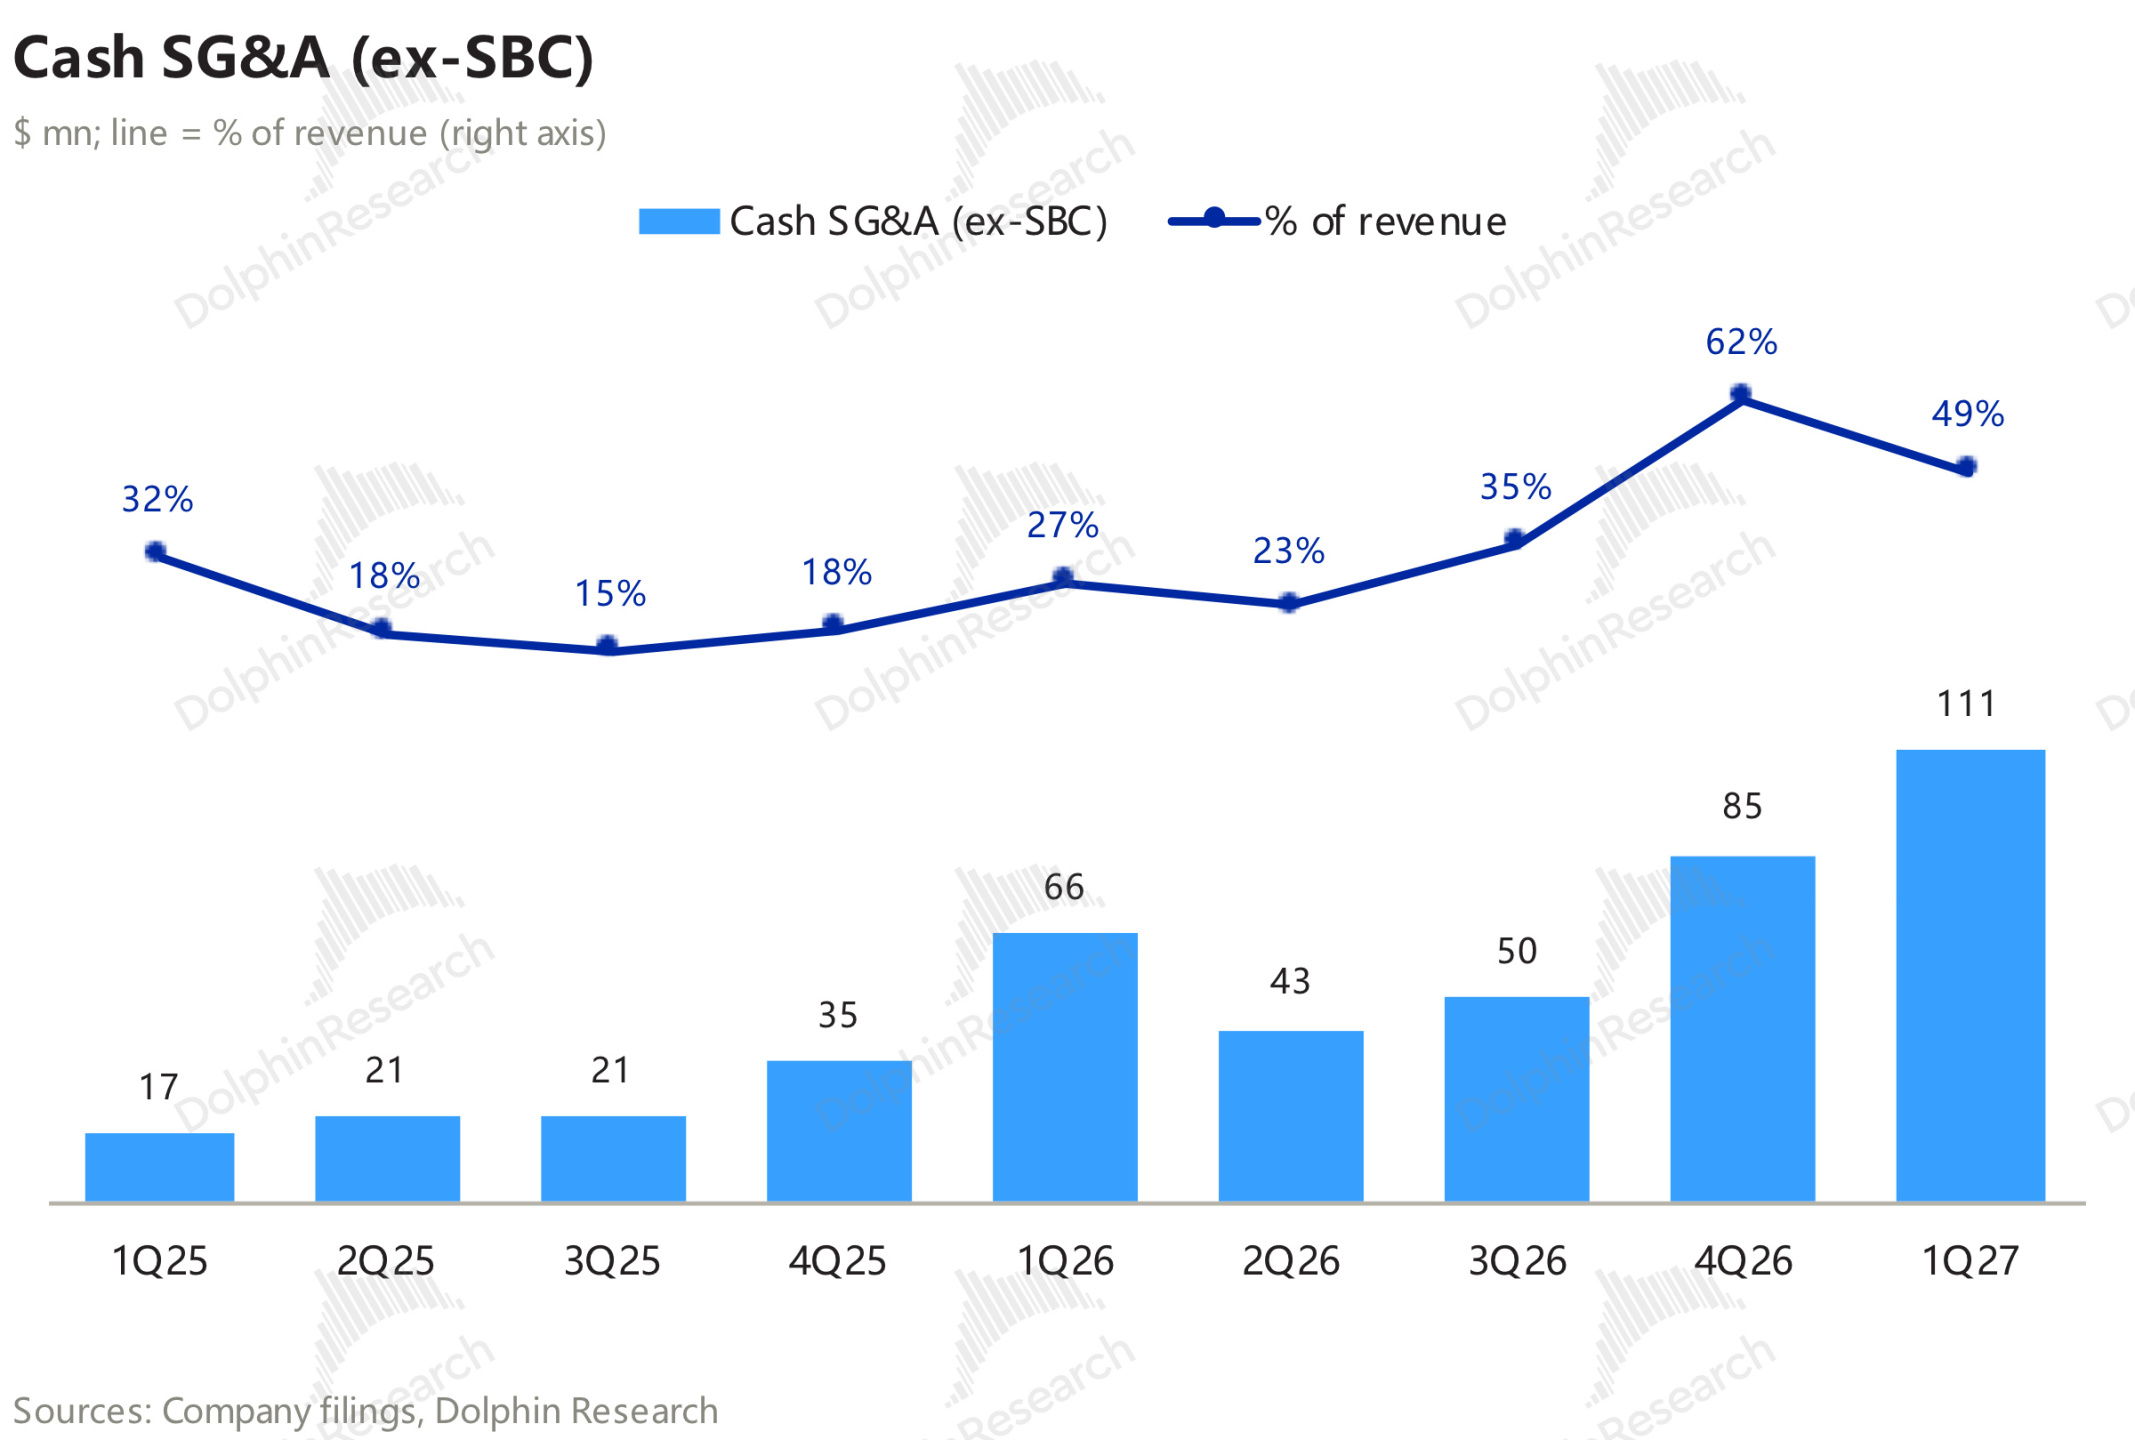
The opex step-up is not over. Cash opex (incl. R&D) ex-SBC was $118 mn vs. $85 mn last quarter, driven by Mirantis consolidation in Aug and continued hiring. Mgmt expects a further $50–60 mn increase in the Dec quarter to ~$170 mn. With flat revenue and higher opex, a rough cut puts 2Q27 Adj. EBITDA at only ~$50 mn vs. Bloomberg consensus $201 mn.
SBC was $106 mn, ~80% above expectations, mainly from July grants of 9.1 mn RSUs to each of the two Co-CEOs, with grant-date value of $276 mn per person, vesting over four years. Unamortized service RSUs stand at $594 mn, to be amortized over ~2.17 years, implying ~$100 mn SBC per quarter for some time. GAAP net loss was $263 mn, ~$70 mn wider than expected, driven by SBC and interest expense.
3. Bookings & pricing: better pricing and prepayments; volumes undisclosed
All new bookings were post-quarter with improved terms, but client names and MW were undisclosed. Mgmt said the following were signed this week: a) a 5-year contract with per-MW annual revenue of ~$22 mn and client prepayment covering ~90% of related GPU capex (vs. prior new-deal norms of 45–55%); b) a 3–6 month short-term contract with per-MW annualized revenue of $40 mn; c) an expansion with a 'Leading Frontier AI Lab' doubling scale; d) H100 re-signed at twice the Prince George original contract pricing on a multi-year basis.
Pricing is trending up. This quarter, contracted per-MW annual revenue was $19–23 mn for 3-year terms and ~$17 mn for 5-year terms, up 11% and 12% QoQ, respectively. Backlog rose to $20.3 bn at Sep-end, +22% vs. Jun-end; Microsoft accounts for 47%, NVIDIA 17%, and two-thirds is from investment-grade clients.
4. CapEx & financing: proactive slowdown; first quantified debt capacity
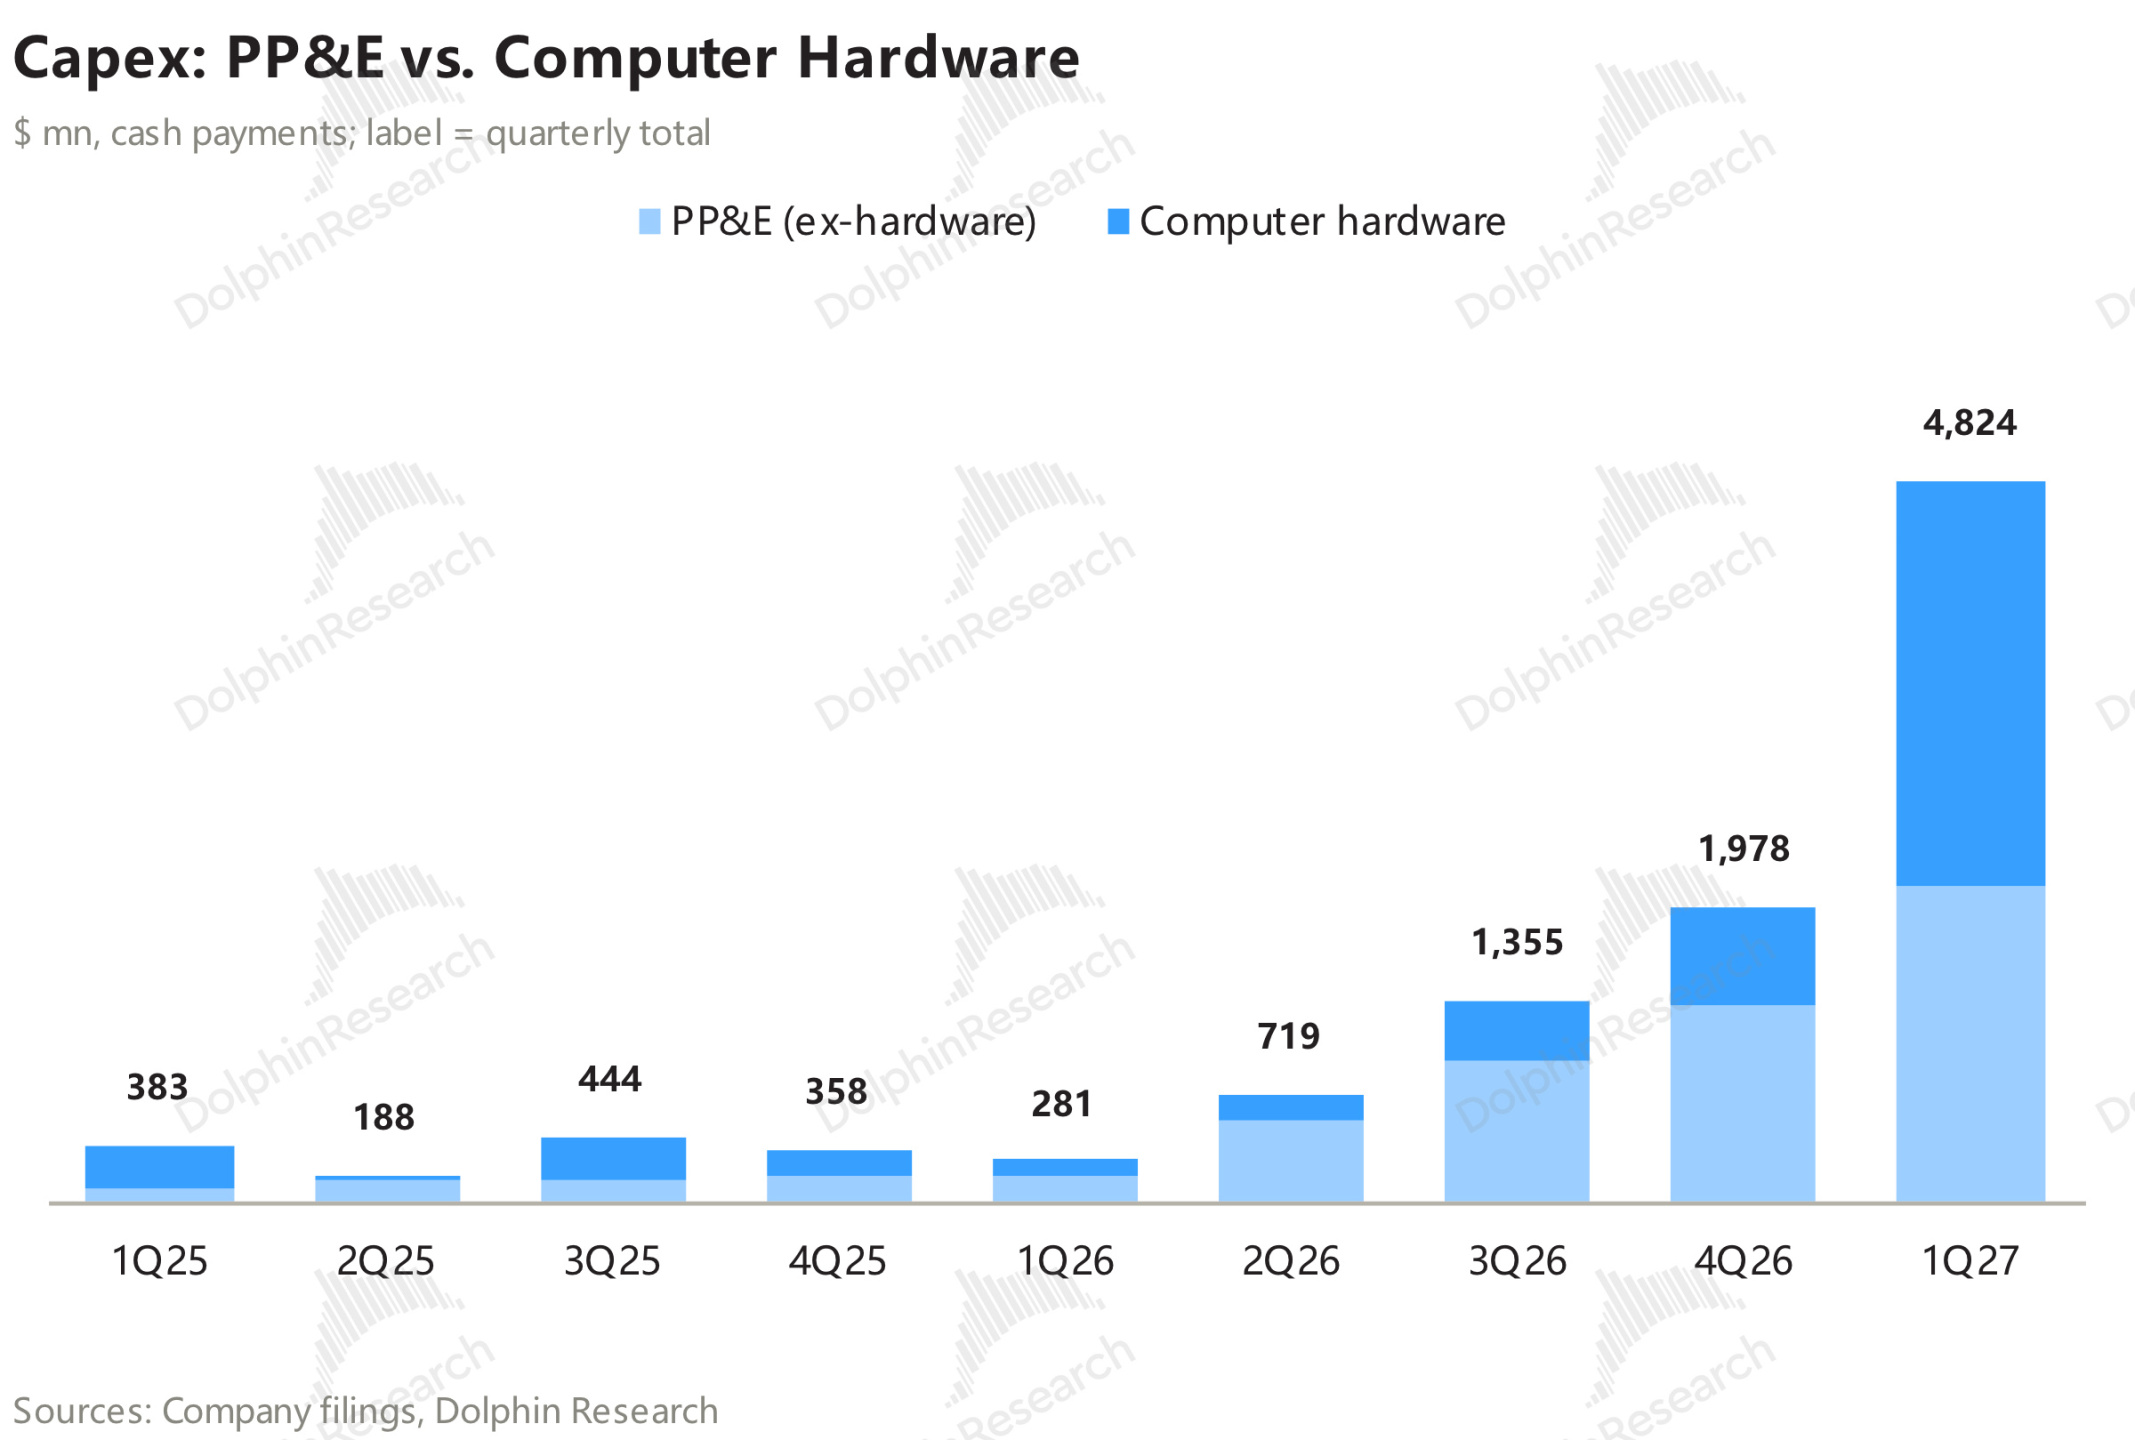
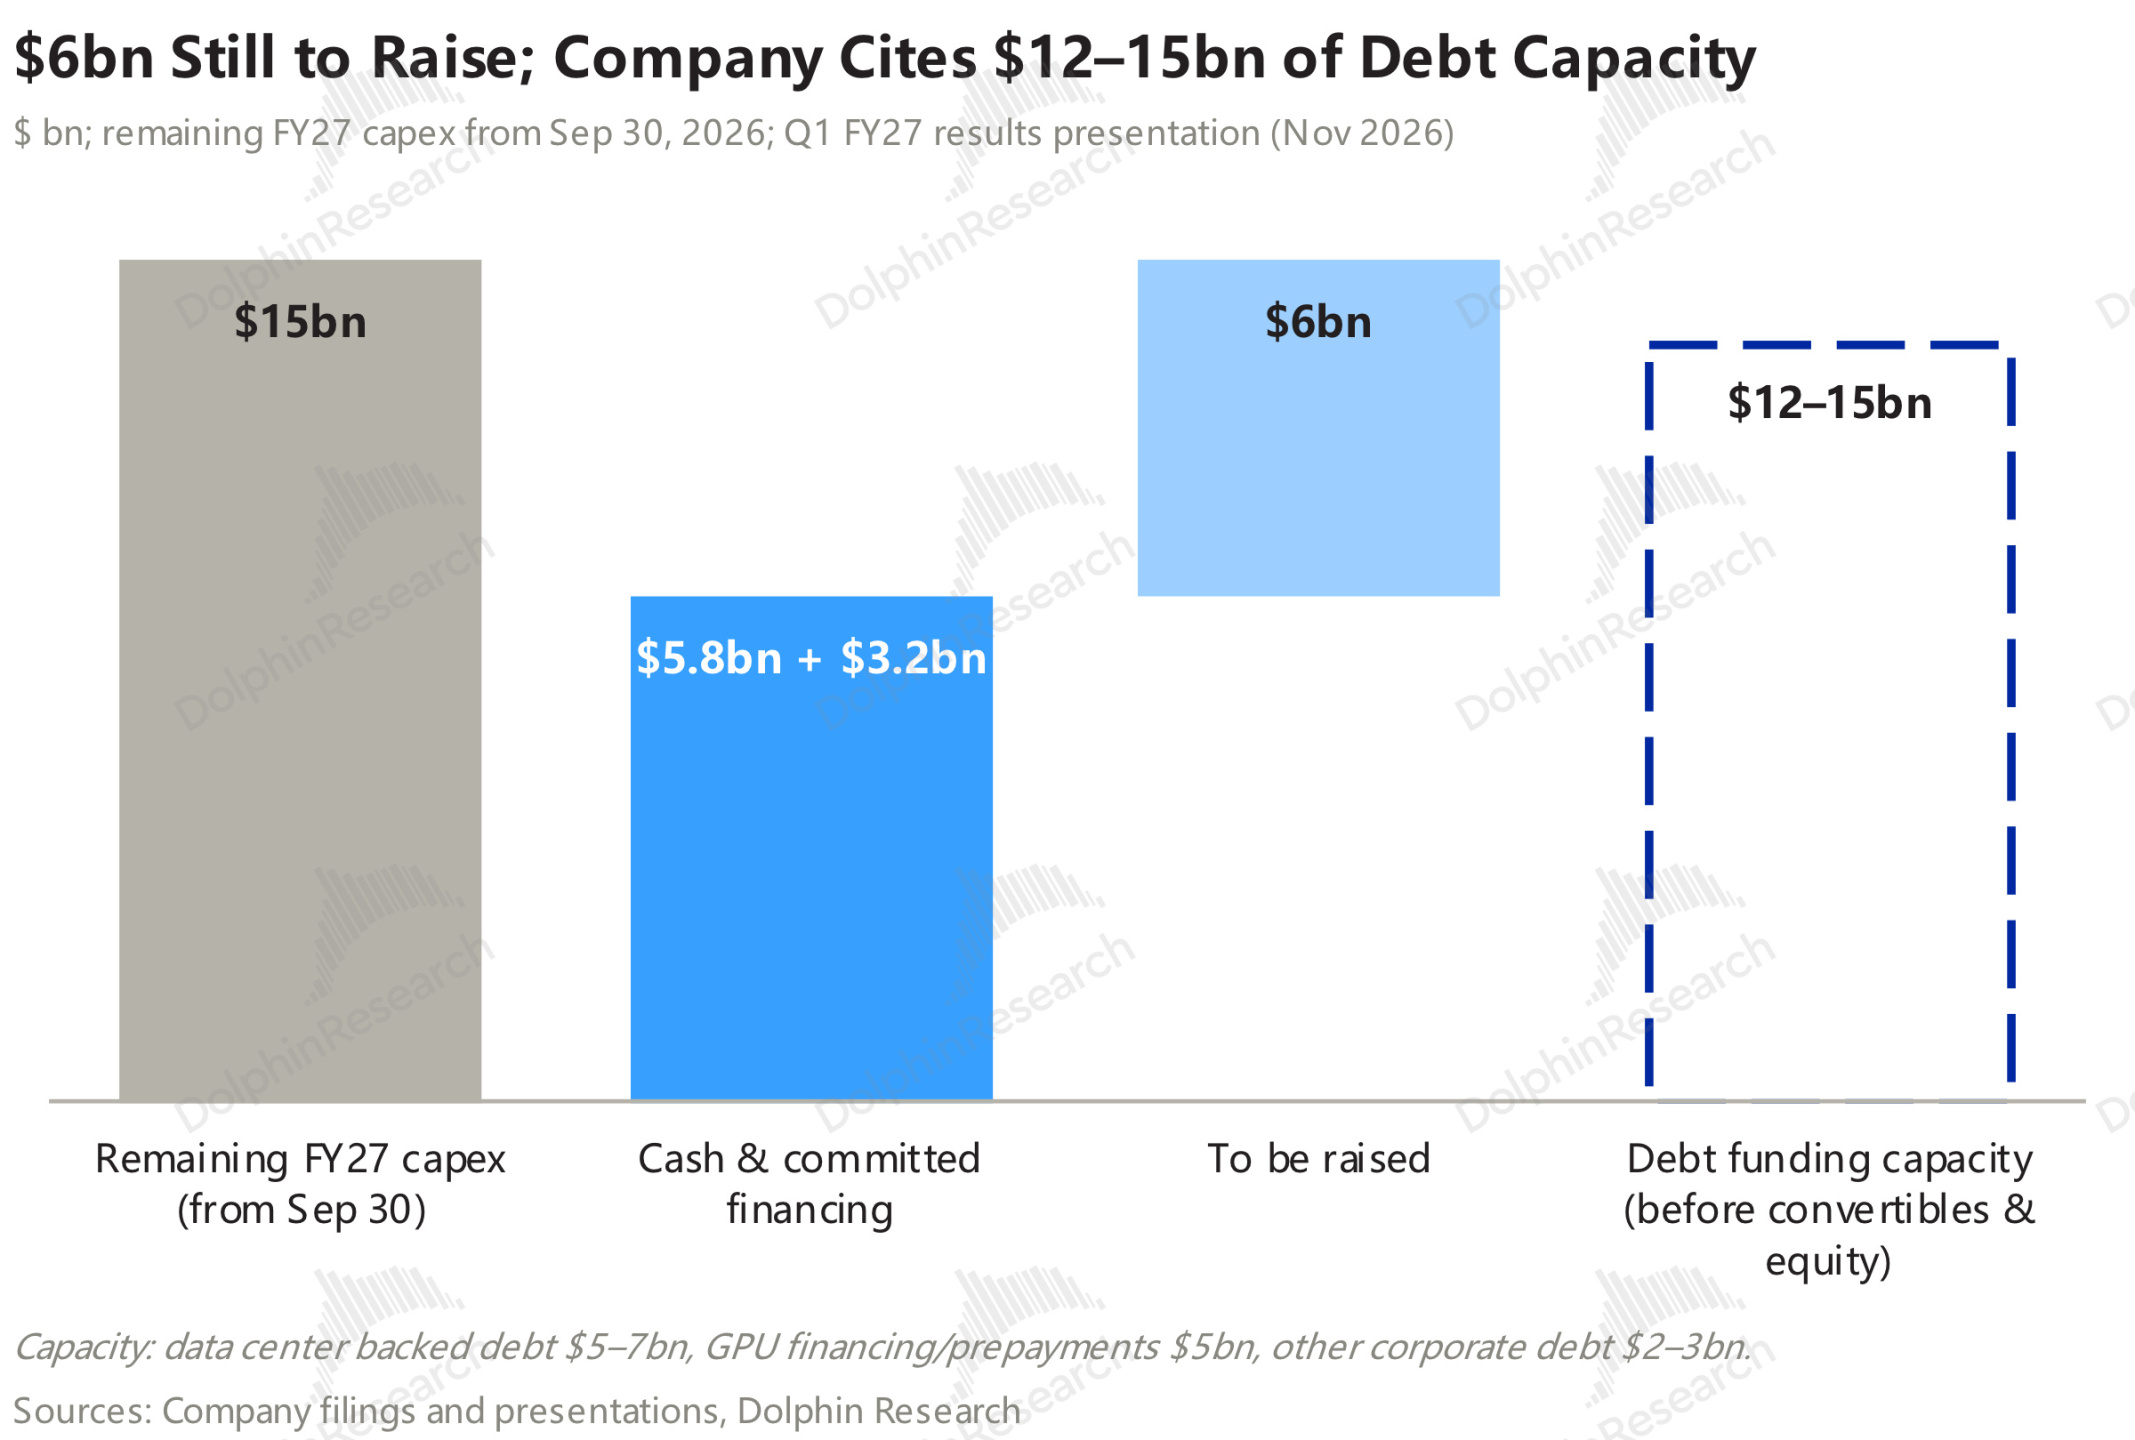
Single-quarter CapEx continued to expand, while FY27 CapEx guidance was proactively cut. CapEx was $4.82 bn, 2.4x QoQ. FY27 is no longer guided at $25–30 bn for the year; from Sep-end, the remaining need is $15 bn: cash $5.8 bn, committed GPU financing and prepayments $3.2 bn, and ~$6 bn to be financed. Mgmt said two consecutive cuts reflect a proactive pace aligned with capital markets, shifting Childress air-cooled deployment from front-loaded to spread across 2027; the 0.8 GW year-end 2027 target remains.
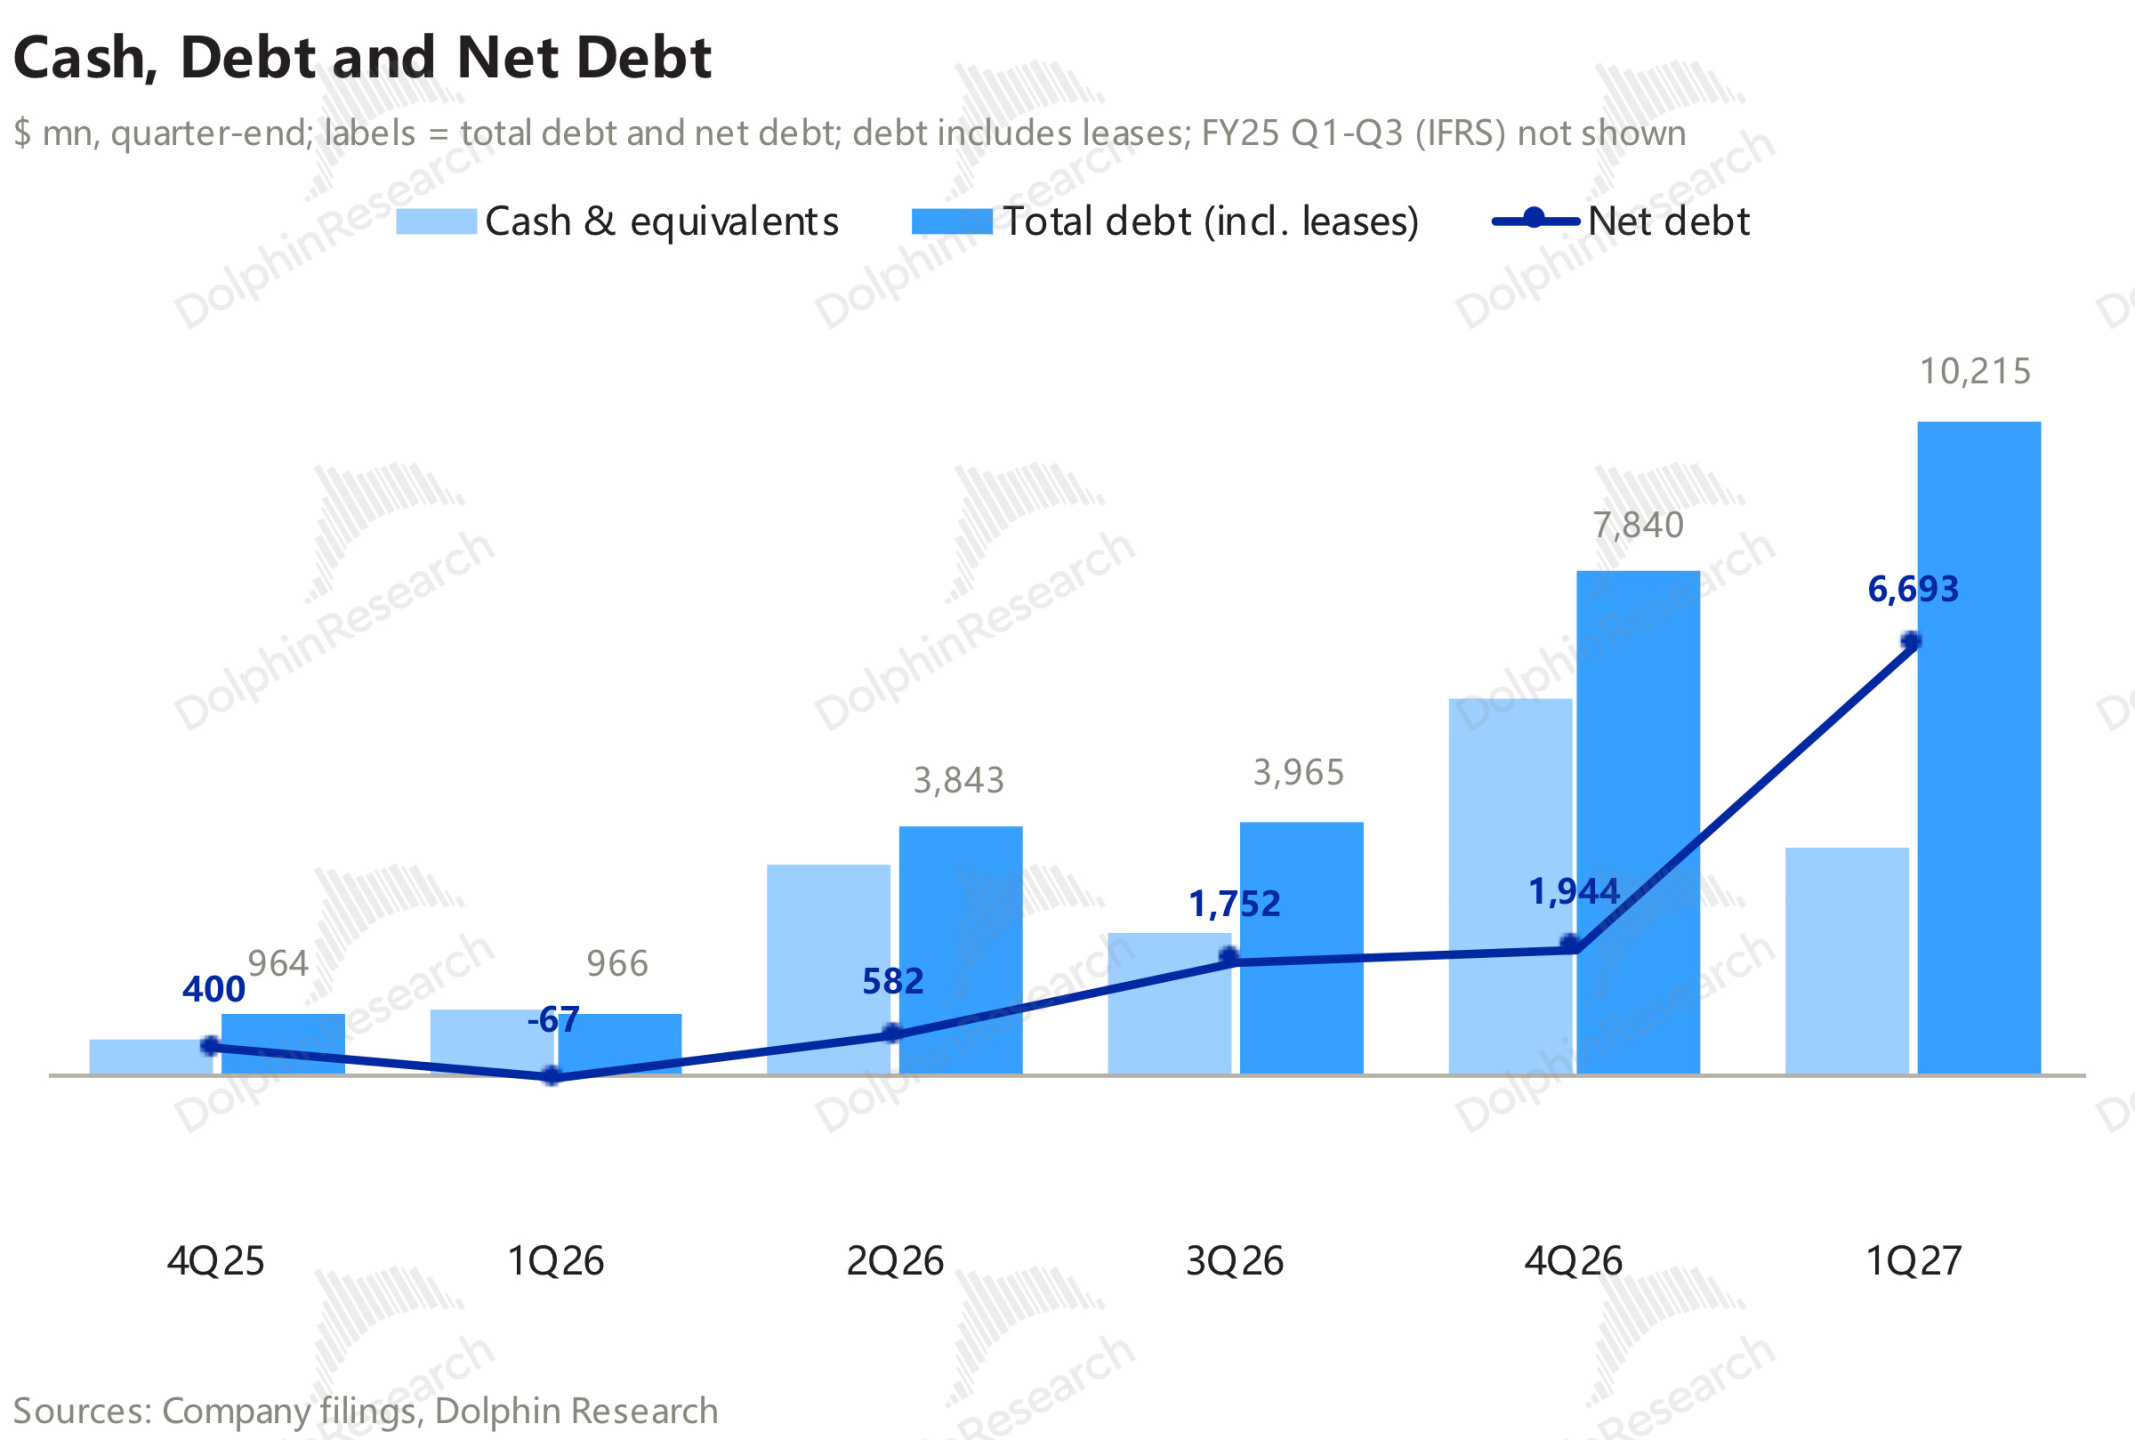
More notably, the company quantified debt capacity for the first time: data center mortgage debt of $5–7 bn, GPU financing and prepayments of $5 bn, and other corporate debt of $2–3 bn, totaling $12–15 bn, explicitly 'before convertible notes and equity'.
New funding still skewed to GPU financing: $2.36 bn drawn, plus $500 mn via ATM equity and $645 mn client prepayments, with no new converts. ATM issuance continued and at lower prices: average from ~$55 last quarter to ~$44 this quarter; post-quarter in Oct, 17.37 mn shares were sold for ~$630 mn at ~$36 on avg., exceeding the entire Sep quarter in both shares and proceeds.
5. For more on this quarter, cf. Trans 'IREN (Trans): $4bn ARR to Jan; CapEx proactively slowed'
6. Performance overview
2) Dolphin Research View
1. Limited impact from delivery delays; financing is the rare positive
Negatives this quarter center on deliveries and opex: delays mainly defer revenue, while higher opex will compress next-quarter profit. The rare positive is financing.
Financing was the bright spot. The $12–15 bn debt capacity is ~2–2.5x the $6 bn funding gap; last quarter, the company listed 'corp. debt and equity' as gap fillers, while this quarter equity is no longer named in the funding plan. At the current share price, this signals mgmt’s intent to minimize equity issuance.
But it is not a commitment. The company still lists 'convertible notes and equity (incl. ATM)' among tools, and the filing preserves equity language. Per media, Co-CEO Daniel Roberts said in late Aug FY27 CapEx 'isn't an equity number', yet the company sold stock via ATM in Oct.
Shares rose ~10% after-hours, which we read as the market valuing the change in financing stance.
2. Core watch: who signs 2027 capacity, and at what price
Pricing and prepayments improved, but volumes remain opaque; 2027 booking risk looks higher than last quarter.
Per company targets, 2027 adds ~0.5 GW (IT basis), rising from 0.3 GW in Jan to 0.8 GW by year-end. Of that, 0.3 GW of GPUs are ordered (Dell ~$6.7 bn), with 0.2 GW to be ordered. Last quarter mgmt said a 'sizable portion' of 2027 capacity was in late-stage negotiations; this quarter that line is gone, replaced by 'selective contracting'. Cards are ordered, but deals are not disclosed.
Backlog does not yet show scale bookings. The 'other customers' bucket rose by ~$3.7 bn QoQ, roughly aligning with the $2.8 bn deal announced in Jul and the Aug frontier lab contract (Dolphin estimate). Mgmt only said the 0.5 GW includes NVIDIA and a top frontier lab, with recent bookings mainly focused on air-cooled capacity at Childress. Post-quarter deal volumes will not be visible until next quarter’s backlog.
Key checkpoints ahead: a) volume: can $IREN(IREN.US) contract most of the 0.5 GW in 2027; b) price: can per-MW annual revenue hold at or above ~$22 mn seen post-quarter; c) prepay: can the ~90% level become standard. Per company slides, GPU capex is ~$40 mn per MW; if prepay rises from 45% to 90%, every 100 MW signed reduces funding needs by ~$1.8 bn versus the ~$6 bn gap.
3. Risks to watch
a) Funding sources. The $12–15 bn capacity is still on paper, with no data center mortgage debt signed; FY27 may need incremental CapEx to reach 0.8 GW, with no amount disclosed. The Aug GPU financing carries ~9% interest and each draw amortizes within 30 months; debt principal due by FY28 is ~$1.06 bn. Next, watch two items: whether Horizon 1–4 (serving Microsoft) secure the first mortgage debt and at what rate; and next quarter’s ATM issuance volumes/prices, with ~$2.3 bn capacity remaining.
b) Delivery and regulation. Supplier delays are not new: Horizon 1 was previously pushed by NVIDIA component shortages. Sweetwater is the only greenfield campus, and mgmt no longer reiterates last quarter’s '4Q27' delivery timing. In Texas, mgmt said Sweetwater 1 (1.4 GW) is connected to the grid, and Sweetwater 1 & 2 together (2 GW) are conditionally in ERCOT’s base-load 'Batch Zero'. On whether client cancellations or prepay refunds could occur if community opposition causes delays, the call did not answer directly.
c) Post-expiry pricing. Most contracts are 3–5 years; pricing on legacy GPUs at renewal is the largest swing factor in valuation. H100 re-signed at 2x the Prince George original price on a multi-year term is the first positive datapoint, but it is only one deal and the original signing date and price were undisclosed.
d) Client concentration. Microsoft is 47% of backlog, NVIDIA 17%, and the top three clients were ~70% of revenue this quarter. New client credit directly affects financing cost: GPU financing rates are ~6% for investment-grade clients vs. 9–9.5% for non-IG.
4. How to value $IREN(IREN.US)?
At the Nov 5 close of $18.03, market cap is ~$7.6 bn. Adding net debt, EV is roughly 3x the $4 bn operating ARR targeted for end-Jan.
Common valuation multiples fit poorly. GAAP losses make P/E unusable; on Dolphin’s FY28 EBITDA estimate, the stock trades at ~5.6x, which looks reasonable, but most EBITDA will go to recoup GPU capex. Roughly 90% of FY28 EBITDA would be consumed by depreciation, leaving ~10% OP; renewal pricing remains uncertain.
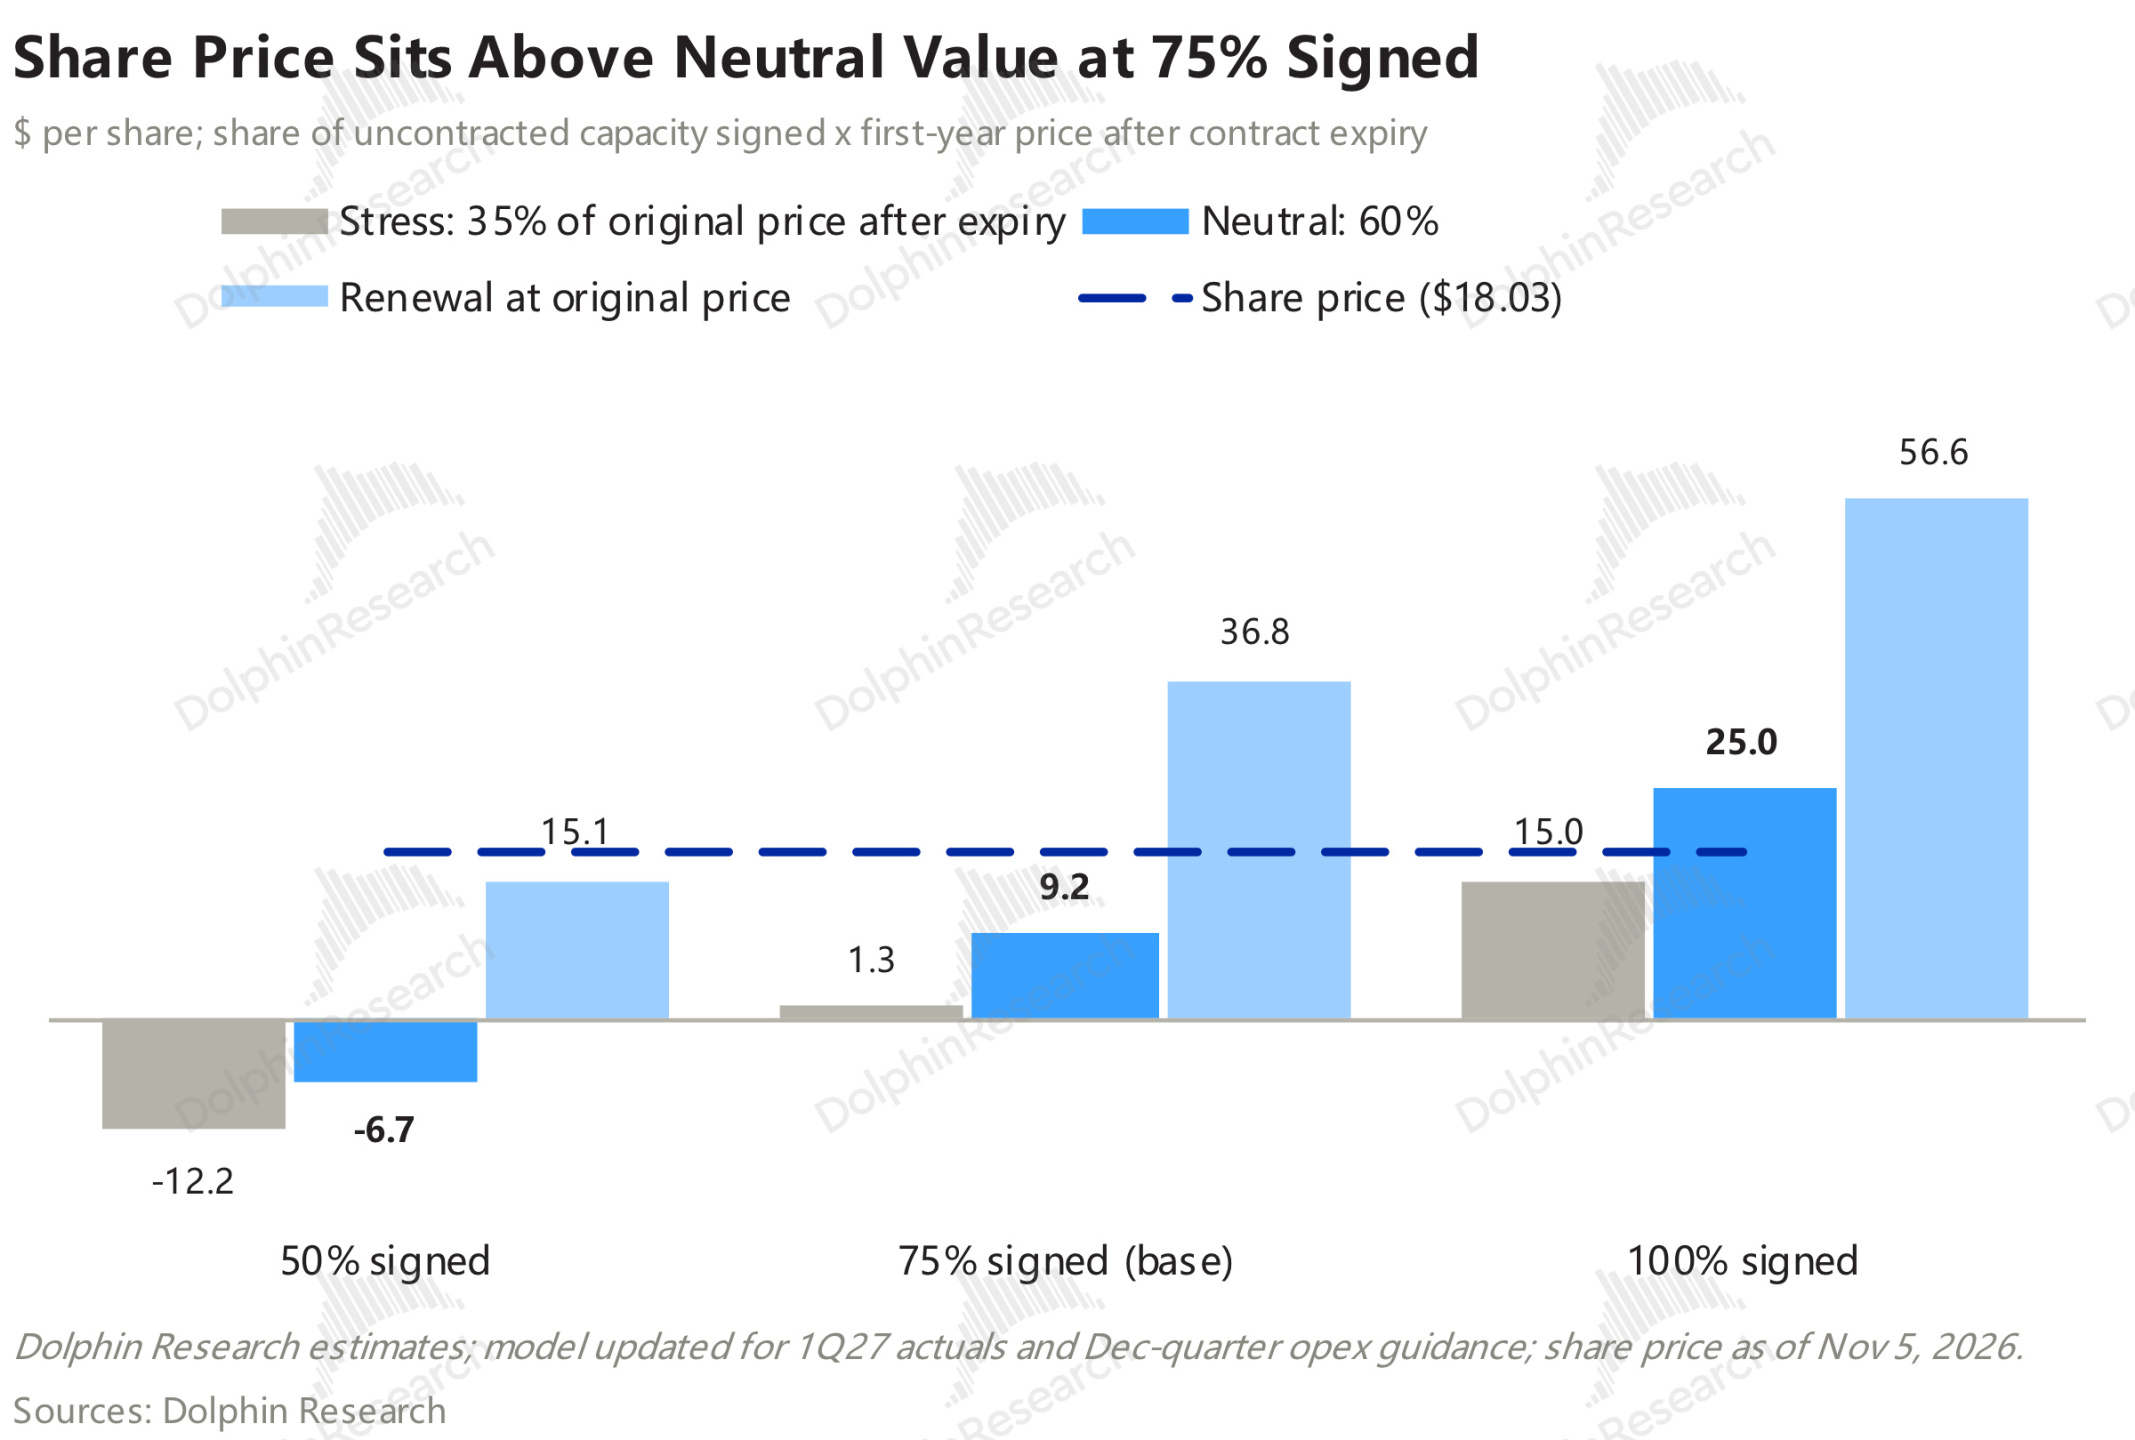
Dolphin discounts contract blocks, with value driven by two variables: 2027 capacity booking rate and post-expiry pricing. Under a neutral case (75% of uncontracted capacity gets signed; first-year renewals at 60% of original price), fair value is ~$9.2/sh, ~4.6x FY28 EBITDA and ~50% below spot.
Both variables swing widely. At a 75% booking rate, per-share value is ~$1.3, $9.2, $36.8 under 35%, 60%, 100% of original pricing at renewal, respectively. At neutral renewal pricing but 100% booking, fair value is ~$25/sh. In other words, the current price roughly implies ~90% booking at neutral renewal pricing, or ~75% booking with renewal pricing at a bit over 70% of original.
Valuation is highly sensitive to opex given leverage. Equity holders get EV minus debt; in Dolphin’s neutral case, >70% of EV is debt. Debt does not shrink when operations weaken, so shortfalls hit equity in full: if the next-quarter opex step is considered structural, FY28 EBITDA falls only ~4%, but neutral per-share value drops nearly 30%.
Dolphin believes the stock prices in optimistic booking and renewal assumptions. Pricing, prepayments and financing stance improved this quarter, but booking volume — the largest variable — remains unanswered.
For holders, watch three items: whether $4bn ARR is achieved by end-Jan; how much of 2027 capacity gets signed, at what price, and with what prepay; and whether the first data center mortgage debt closes. For non-holders, waiting for a pullback toward neutral value (~$9/sh) is safer; if 2027 capacity is largely signed at not less than ~$22.5 mn per MW with higher prepay, that anchor can move up.
Dolphin Research archives on '$IREN(IREN.US)'
2026.11.06 'IREN (Trans): $4bn ARR to Jan; CapEx proactively slowed'
2026.11.06 'IREN FY1Q27 First Take'
Risk disclosure and statements: Dolphin Research disclaimer and general disclosures
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.