


Cerebras Systems Ord Shs Class A (Proposed) Stock (CBRS) Moved Up by 12.05% on Nov 13: Drivers Behind the Movement


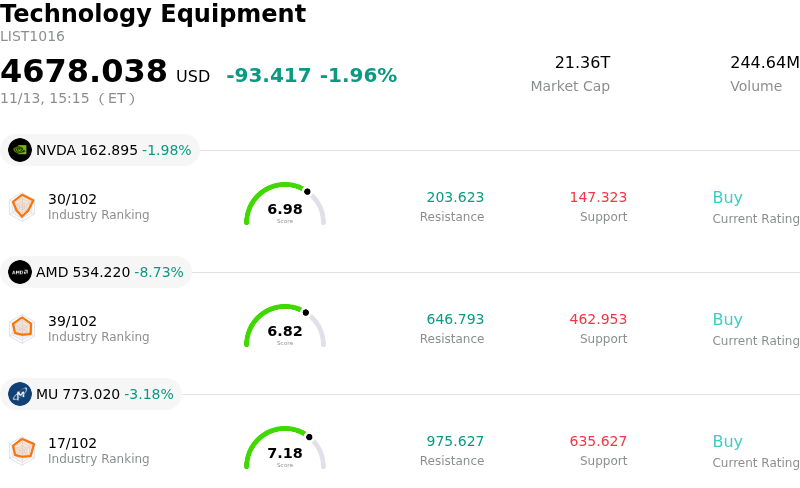
Cerebras Systems Ord Shs Class A (Proposed) (CBRS) moved up by 12.05%. The Technology Equipment sector is down by 1.96%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 1.93%; Advanced Micro Devices Inc (AMD) down 8.73%; Micron Technology Inc (MU) down 3.17%.
What is driving Cerebras Systems Ord Shs Class A (Proposed) (CBRS)’s stock price up today?
Cerebras Systems surged during today's trading session following a robust third-quarter earnings report that substantially surpassed Wall Street expectations across key financial and operational metrics. The AI infrastructure specialist posted positive core net income for the first time since its initial public offering, alongside an adjusted earnings per share outcome that beat consensus forecasts calling for a quarterly loss. Top-line expansion was spearheaded by extraordinary demand for high-speed artificial intelligence inference solutions, where core cloud and services revenues expanded sharply year over year due to increasing enterprise adoption and favorable pricing power.
Investor sentiment was further bolstered by management raising full-year revenue guidance and issuing optimistic forward projections for the fourth quarter. Cerebras signaled that hardware shipments are scheduled to ramp meaningfully into the year-end period, supporting sequential revenue acceleration alongside expected margin expansion as legacy pricing structures expire. Long-term revenue visibility remains exceptionally strong, underscored by remaining performance obligations reaching into the tens of billions of dollars and high-profile ecosystem expansions, including key commercial partnerships and new hyperscaler engagements.
Market confidence was also reinforced by management addressing capacity timelines regarding its major deployment agreements, clarifying that schedule adjustments were driven by broader industry data center power and construction bottlenecks rather than proprietary semiconductor manufacturing limitations. While sequential cloud service expansion faces near-term capacity constraints over the immediate horizon, substantial megawatts of contracted infrastructure slated to come online through 2027 provide a visible path to sustained scale. From an institutional standpoint, the company's inflection toward operating profitability and expanding presence in the rapidly growing inference sector have outweighed near-term infrastructure execution risks.
Technical Analysis of Cerebras Systems Ord Shs Class A (Proposed) (CBRS)
Technically, Cerebras Systems Ord Shs Class A (Proposed) (CBRS) shows a MACD (12,26,9) value of 6.516, indicating a neutral signal. The RSI at 45.056 suggests neutral condition and the Williams %R at 25.889 suggests buy condition. Please monitor closely.
Fundamental Analysis of Cerebras Systems Ord Shs Class A (Proposed) (CBRS)
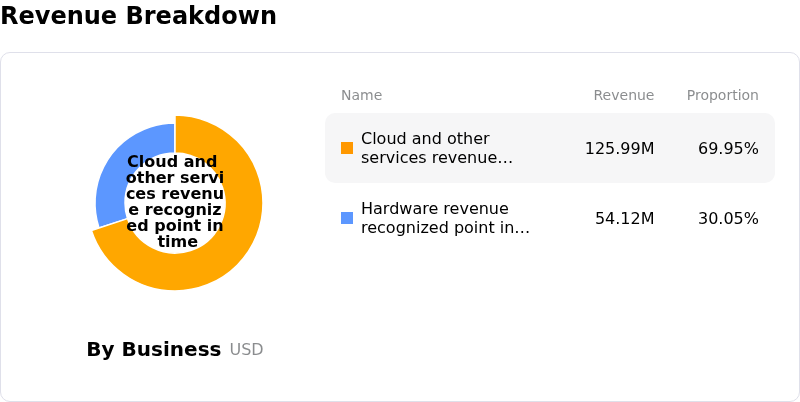
Cerebras Systems Ord Shs Class A (Proposed) (CBRS) is in the Technology Equipment industry. Its latest annual revenue is $509.99M, ranking 7 in the industry. The net profit is $87.88M, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $279.38, a high of $325.00, and a low of $175.00.
More details about Cerebras Systems Ord Shs Class A (Proposed) (CBRS)
Company Specific Risks:
- Severe Q3 GAAP Earnings and Revenue Miss: In its Q3 FY2026 earnings report, Cerebras reported a GAAP net loss of $161.2 million, or -$0.67 per share, missing Wall Street consensus estimates of a -$0.14 loss per share by roughly 379%, while GAAP revenue of $210.8 million fell short of the $214.9 million consensus.
- Contract Delivery Delays from Land and Power Bottlenecks: Management revealed delivery delays under its flagship multiyear agreement with OpenAI stemming from infrastructure, land, and data center power shortages, underscoring significant physical deployment hurdles that threaten contract realization.
- Elevated Customer Concentration and Capacity Scaling Risks: Despite a reported $26.1 billion backlog, institutional analysts continue to flag acute vulnerability surrounding revenue concentration across a handful of mega-cap clients (OpenAI, Microsoft, and Oracle), coupled with execution headwinds as the company attempts to bring 700 MW of contracted data center capacity online through 2027.
- Intraday Price Reversal and Institutional Valuation Headwinds: An initial post-earnings surge to an intraday high of $120.44 faded sharply toward the $98–$103 range amid heavy selling pressure, reflecting valuation pushback on its elevated price-to-sales multiple following recent Wall Street target cuts, including Morgan Stanley lowering its price target from $279 to $178.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.