


Fabrinet Stock (FN) Moved Down by 7.54% on Nov 13: What Signal Does It Send?


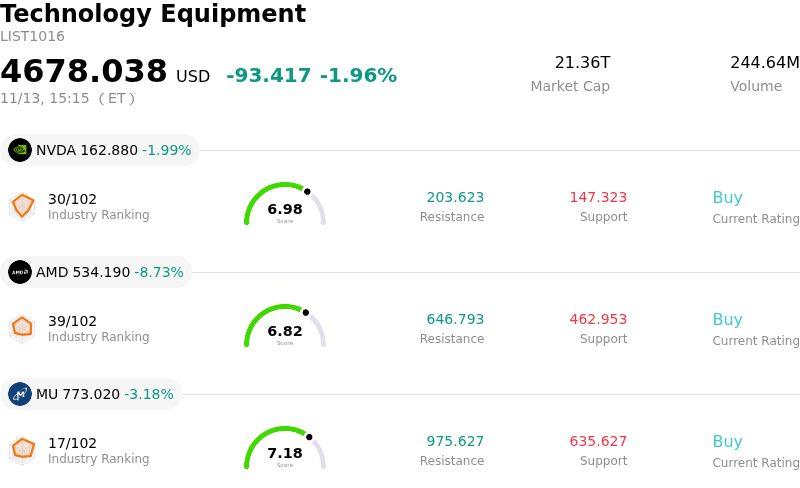
Fabrinet (FN) moved down by 7.54%. The Technology Equipment sector is down by 1.96%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 1.93%; Advanced Micro Devices Inc (AMD) down 8.73%; Micron Technology Inc (MU) down 3.17%.
What is driving Fabrinet (FN)’s stock price down today?
Fabrinet experienced significant downward pressure as a broader risk-off rotation swept through optical communications and artificial intelligence hardware suppliers. Despite the company recently delivering record quarterly revenues and robust operational execution, sentiment across the optical interconnect supply chain has deteriorated. Investors have increasingly grown cautious regarding the sustainability and cadence of hyperscaler capital expenditures, prompting institutional profit-taking and multiple compression across high-beta AI infrastructure beneficiaries.
Compounding this broader sector headwind are structural uncertainties surrounding customer concentration and industry consolidation. With major consolidation taking place among key optical component designers, particularly Marvell Technology agreeing to acquire Lumentum, market participants are reassessing long-term manufacturing allocations. Because Fabrinet generates a substantial portion of its business from a concentrated cohort of networking leaders, any ambiguity regarding whether production programs will remain outsourced or be altered under merged corporate entities introduces revenue visibility concerns over the medium term.
Financial dynamics and cash flow considerations have also dampened investor enthusiasm. While headline earnings and revenue guidance continue to showcase double-digit expansion, Fabrinet has undertaken aggressive capacity investments to support next-generation transceiver packaging. This elevated capital spending profile has pressured near-term free cash flow, turning it negative and raising concerns among value-sensitive investors about the duration of the current investment cycle.
Additionally, Wall Street firms have adjusted their near-term price targets downward to account for compressed peer multiples and broader semiconductor equipment volatility. As momentum unwind and macroeconomic uncertainty encourage institutional investors to derisk elevated technology holdings, Fabrinet has borne the brunt of sympathy selling alongside its optical networking peers. Until greater clarity emerges around hyperscaler capital expenditure continuity and post-merger packaging agreements, the stock remains vulnerable to heightened intraday volatility.
Technical Analysis of Fabrinet (FN)
Technically, Fabrinet (FN) shows a MACD (12,26,9) value of 7.973, indicating a neutral signal. The RSI at 43.917 suggests neutral condition and the Williams %R at 56.084 suggests sell condition. Please monitor closely.
Fundamental Analysis of Fabrinet (FN)
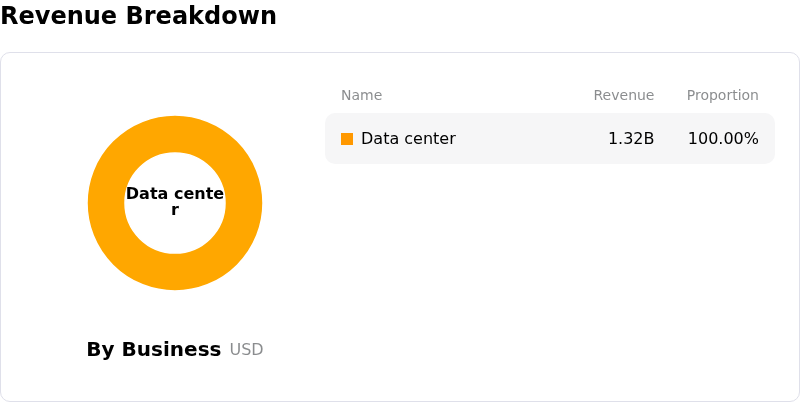
Fabrinet (FN) is in the Technology Equipment industry. Its latest annual revenue is $4.64B, ranking 16 in the industry. The net profit is $473.03M, ranking 10 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $574.40, a high of $800.00, and a low of $364.00.
More details about Fabrinet (FN)
Company Specific Risks:
- Customer Consolidation and Contract Uncertainty: Marvell Technology's transaction to acquire Lumentum—one of Fabrinet's primary accounts—creates severe risk of revenue leakage, as key optical packaging and manufacturing volumes face potential internalization, dual-sourcing, or contract renegotiation.
- Negative Free Cash Flow and Margin Vulnerability: Aggressive capital spending on new manufacturing facilities has driven free cash flow into negative territory (-$137 million), amplifying operational vulnerability given structurally thin contract-manufacturing gross margins near 12%.
- Extreme Revenue Concentration in AI Optical Hardware: Over-reliance on a narrow cohort of AI transceiver partners and hyperscale compute demand leaves the company disproportionately exposed to sudden order adjustments or inventory digestion cycles across datacenter hardware supply chains.
- Multiple Compression and Widespread Analyst Target Cuts: Institutional desks have executed steep price-target reductions driven by broader multiple de-rating across AI optics and optical suppliers, compounded by persistent insider share liquidations that reinforce institutional selling pressure.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.