


SanDisk Corporation Stock (SNDK) Moved Down by 8.23% on Nov 13: A Full Analysis


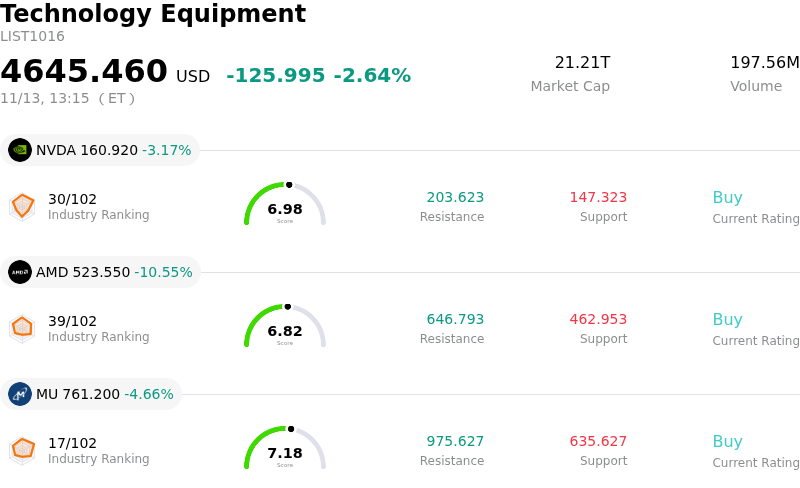
SanDisk Corporation (SNDK) moved down by 8.23%. The Technology Equipment sector is down by 2.64%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 3.22%; Advanced Micro Devices Inc (AMD) down 10.69%; Micron Technology Inc (MU) down 4.66%.
What is driving SanDisk Corporation (SNDK)’s stock price down today?
SanDisk Corporation is experiencing pronounced downward pressure during today's session as broad-based profit-taking across memory semiconductor equities combines with emergent concerns over NAND flash pricing trajectories. Following an extended expansion in enterprise storage valuations, market participants are demonstrating increased sensitivity to cyclical inflection risks, prompting institutional de-risking across high-beta storage names.
A primary fundamental catalyst weighing on sentiment is growing anxiety over pricing growth deceleration in the NAND flash and enterprise solid-state drive markets. While recent operating performance demonstrated robust capacity absorption supported by data center infrastructure buildouts, institutional models are beginning to price in a normalization of average selling prices. As channel inventory restocking moderates and supplier capital expenditures ramp back up, expectations for margin expansion face scrutiny, triggering preemptive position trimming by institutional asset managers.
Industry-wide sentiment has also been dampened by volatility across the broader artificial intelligence hardware complex. As investors reassess valuation multiples across the semiconductor supply chain in response to shifting macroeconomic signals and interest rate expectations, memory and storage providers have experienced heightened multiple compression. Elevated volatility metrics and momentum unwinds have amplified the intraday downside, particularly as systematic strategies reduce exposure to the segment.
Looking ahead, SanDisk's near-term recovery will rely heavily on sustained pricing power in high-density enterprise storage and discipline among leading NAND suppliers. Institutional investors will closely monitor upcoming industry supply-demand data points and hyperscaler procurement guidance to determine whether current weakness represents a temporary valuation reset or the early phase of a broader cyclical downshift.
Technical Analysis of SanDisk Corporation (SNDK)
Technically, SanDisk Corporation (SNDK) shows a MACD (12,26,9) value of -23.639, indicating a sell signal. The RSI at 33.107 suggests neutral condition and the Williams %R at 90.532 suggests oversold condition. Please monitor closely.
Media Coverage of SanDisk Corporation (SNDK)
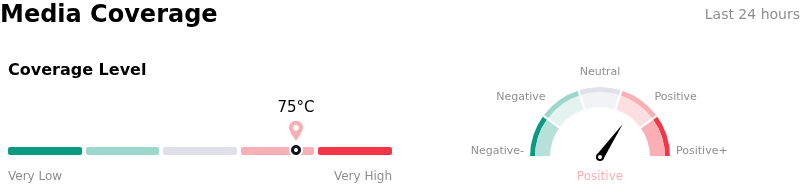
In terms of media coverage, SanDisk Corporation (SNDK) shows a coverage score of 75, indicating a high level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of SanDisk Corporation (SNDK)
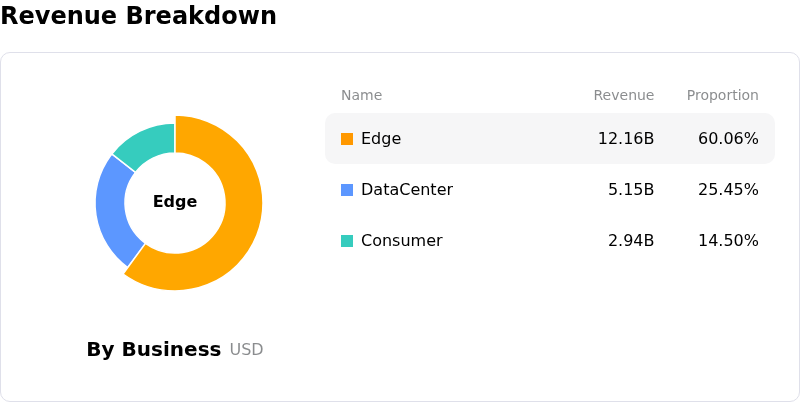
SanDisk Corporation (SNDK) is in the Technology Equipment industry. Its latest annual revenue is $20.25B, ranking 8 in the industry. The net profit is $11.43B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $2024.13, a high of $3000.00, and a low of $1020.00.
More details about SanDisk Corporation (SNDK)
Company Specific Risks:
- Gross Margin Plateau and Cyclical Peak Concerns: Institutional analysts are actively trimming price targets (including RBC and Wells Fargo lowering targets toward $1,300–$1,400) due to growing conviction that Sandisk’s extraordinary 85.1% gross margin represents a cyclical peak; forward guidance of 84.5%–85.5% indicates plateauing average selling prices (ASPs), leaving the business acutely exposed to sudden margin compression if industry supply normalizes.
- Downstream Exposure to AI Infrastructure Contagion: Because enterprise solid-state drive (SSD) demand tied directly to hyperscale artificial intelligence buildouts drove approximately 88% of recent quarterly revenue growth, Sandisk suffers from high systemic beta to data center partners; abrupt leadership upheaval and CEO resignation at primary ecosystem partner NVIDIA triggered heavy sympathy selling and concerns over potential delays or re-evaluations of high-density storage capex.
- Accelerating Market Share Erosion from Low-Cost Competitors: Counterpoint Research data shows Sandisk's global NAND flash revenue share slipped to 11% (falling to sixth place globally), while domestic Chinese rival YMTC advanced to 14%; accelerating wafer expansion and node transitions from YMTC and CXMT heighten competitive threats to Sandisk’s multi-year contract pricing and enterprise market share retention.
- Extreme Segment Concentration and Consumer/Edge Weakness: Intraday volatility underscores Sandisk’s lopsided reliance on enterprise data center demand to offset lingering stagnation in edge and consumer storage markets; client-side pushback regarding high memory procurement costs poses an execution risk to the enforcement of minimum price floors under the company’s new long-term agreements.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.