


Seagate Technology Holdings PLC Stock (STX) Moved Down by 4.62% on Nov 13: Facts Behind the Movement


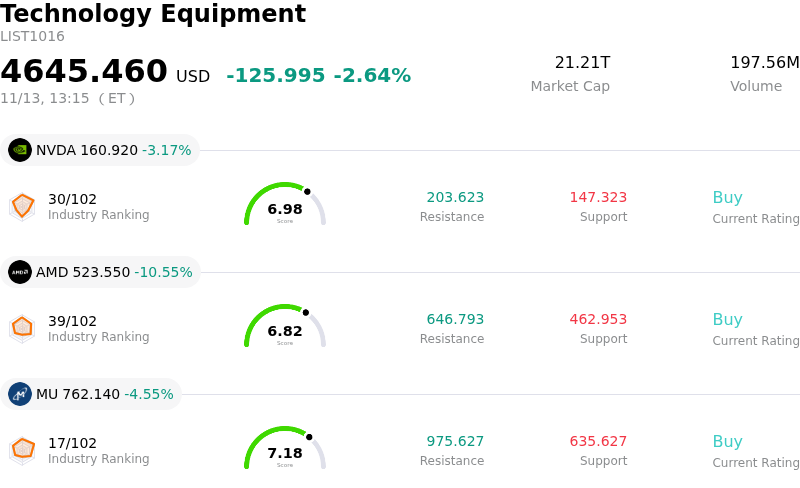
Seagate Technology Holdings PLC (STX) moved down by 4.62%. The Technology Equipment sector is down by 2.64%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 3.22%; Advanced Micro Devices Inc (AMD) down 10.69%; Micron Technology Inc (MU) down 4.66%.
What is driving Seagate Technology Holdings PLC (STX)’s stock price down today?
Seagate Technology experienced notable downward pressure during the session, driven by a confluence of tech-sector risk aversion, macroeconomic yield volatility, and emerging caution surrounding near-term enterprise storage spending. As broader semiconductor and hardware benchmarks faced systematic selling, high-beta cyclical hardware names were disproportionately affected, with institutional investors reducing exposure to capital-intensive technology suppliers following extended valuation multiple expansions.
A primary fundamental catalyst weighing on sentiment is growing investor scrutiny over the trajectory of hyperscaler capital expenditure. While structural demand for artificial intelligence infrastructure remains robust, enterprise data storage procurement often experiences periodic digestion phases. Market participants are increasingly wary of sequential moderation in mass-capacity hard disk drive ordering as cloud service providers optimize existing inventories and reassess nearline capacity allocations. Any perceived pause in bit shipment momentum across tier-one data center customers creates immediate headwind for Seagate, where revenue visibility is tightly coupled to cloud infrastructure deployment schedules.
Operational and technological execution risks also contributed to today's pullback. The industry continues to navigate a critical architectural transition toward advanced areal density technologies, particularly Heat-Assisted Magnetic Recording. While these high-capacity drives promise substantial margin expansion and total cost of ownership benefits for cloud operators, high-density platform transitions carry inherent qualification timelines and yield ramping challenges. Unfavorable shifts in enterprise IT spending or prolonged customer qualification cycles can temporarily compress product mix advantages and defer projected margin gains.
From an institutional positioning perspective, profit-taking played a visible role. Given Seagate's strong historical beta and previous appreciation tied to AI storage tailwinds, funds frequently rotate capital away from traditional storage hardware into defensive assets during periods of broader market uncertainty. In the near term, institutional sentiment is likely to remain cautious until clearer data emerges confirming steady nearline cloud demand, resilient average selling prices, and sustained gross margin expansion through the next product cycle.
Technical Analysis of Seagate Technology Holdings PLC (STX)
Technically, Seagate Technology Holdings PLC (STX) shows a MACD (12,26,9) value of -0.390, indicating a sell signal. The RSI at 36.409 suggests neutral condition and the Williams %R at 73.401 suggests sell condition. Please monitor closely.
Media Coverage of Seagate Technology Holdings PLC (STX)
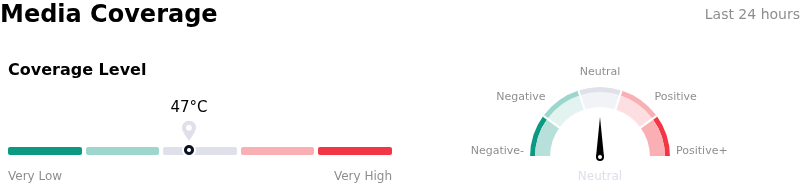
In terms of media coverage, Seagate Technology Holdings PLC (STX) shows a coverage score of 47, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Seagate Technology Holdings PLC (STX)
Seagate Technology Holdings PLC (STX) is in the Technology Equipment industry. Its latest annual revenue is $12.20B, ranking 10 in the industry. The net profit is $3.18B, ranking 5 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $1045.19, a high of $1588.00, and a low of $708.21.
More details about Seagate Technology Holdings PLC (STX)
Company Specific Risks:
- Post-Earnings Analyst Downgrades and Target Cuts: Institutional research desks have initiated rating downgrades and lowered price targets, expressing concerns over sluggish sequential exabyte capacity growth (+1% quarter-over-quarter) and pushing out milestone timeline projections for run-rate conversion into 2028.
- Emerging Nearline Supply Glut and Competitive Threats: Market worries have intensified around cloud storage pricing power as competitors Western Digital and Toshiba aggressively accelerate hard drive capacity and heat-assisted magnetic recording (HAMR) expansion, heightening the risk of medium-term industry oversupply and ASP erosion.
- Margin Compression from Rising Input Costs: Lingering external component cost pressures, coupled with moderating forward gross margin guidance, are raising institutional skepticism over whether current record profitability levels can withstand potential pauses in hyperscaler AI infrastructure capex.
- Persistent Executive Insider Selling: Recent Form 4 filings disclosing substantial equity liquidations by senior executives—including significant share disposals by the CEO and CFO—have shaken investor confidence regarding valuation sustainability following the stock's recent trading volatility.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.