


Qualcomm Inc Stock (QCOM) Moved Down by 3.85% on Nov 13: A Full Analysis


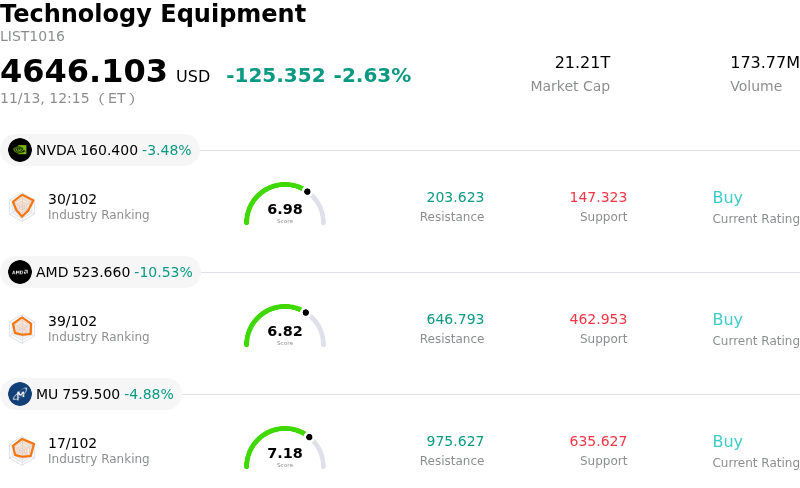
Qualcomm Inc (QCOM) moved down by 3.85%. The Technology Equipment sector is down by 2.63%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 3.45%; Advanced Micro Devices Inc (AMD) down 10.53%; Micron Technology Inc (MU) down 4.88%.
What is driving Qualcomm Inc (QCOM)’s stock price down today?
Qualcomm experienced pronounced downward pressure during the trading session, driven by a broader retreat across semiconductor equities alongside persistent fundamental questions surrounding consumer hardware demand. Risk sentiment deteriorated across high-beta technology names as broader macroeconomic crosscurrents and recalibrated interest rate expectations prompted institutional desks to pare back exposure to cyclical chipmakers. In addition, cautious commentary surrounding global smartphone replacement cycles, particularly in international retail channels, weighed heavily on investor sentiment toward handset-dependent component suppliers.
Compounding this macro headwind are ongoing concerns regarding competitive dynamics and medium-term customer concentration. Market participants continue to discount the potential revenue erosion tied to Apple's progressive transition toward proprietary cellular modems, which threatens to diminish a historically lucrative baseband licensing and component channel. Concurrently, aggressive competition from rivals like MediaTek in the upper-mid and premium mobile tiers, coupled with ongoing legal and architectural uncertainties within the broader Arm computing ecosystem, has placed downward pressure on Qualcomm's valuation multiples.
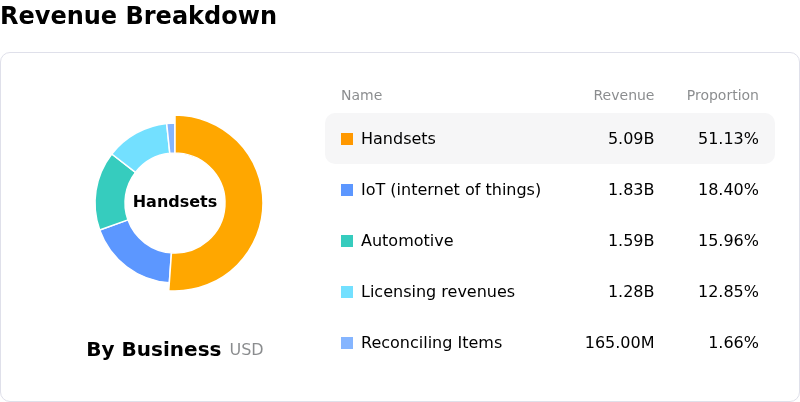
While the company continues to aggressively expand its footprint beyond mobile into automotive digital chassis systems, enterprise IoT, and AI-capable PC processors, these diversification initiatives have not yet achieved sufficient scale to entirely neutralize cyclical softness in core smartphone shipments. Institutional flow data suggests that hedge funds and asset managers trimmed positions amid recent cautious revisions to forward semiconductor demand forecasts. Until clearer evidence of an accelerated consumer device upgrade cycle emerges or non-handset revenues scale rapidly enough to offset legacy client transitions, Qualcomm shares are likely to face heightened volatility and constrained upside momentum.
Technical Analysis of Qualcomm Inc (QCOM)
Technically, Qualcomm Inc (QCOM) shows a MACD (12,26,9) value of 1.023, indicating a neutral signal. The RSI at 47.342 suggests neutral condition and the Williams %R at 40.894 suggests buy condition. Please monitor closely.
Media Coverage of Qualcomm Inc (QCOM)
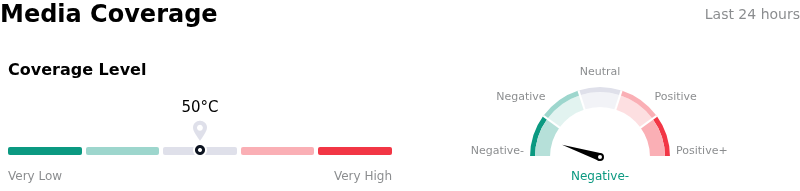
In terms of media coverage, Qualcomm Inc (QCOM) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bearish zone.
Fundamental Analysis of Qualcomm Inc (QCOM)
Qualcomm Inc (QCOM) is in the Technology Equipment industry. Its latest annual revenue is $43.12B, ranking 7 in the industry. The net profit is $13.63B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Qualcomm Inc (QCOM)
Company Specific Risks:
- Handset Revenue Contraction and Apple In-Sourcing: Core mobile handset revenue plunged 26% year-over-year to $5.14 billion with further sequential declines guided into Q1 FY2027, driven by broader smartphone market softness and Apple accelerating the transition to proprietary in-house modems.
- Data Center Ramp Margin Dilution: Operating margins are facing sharp compression, with QCT EBT margin guided down to 20%–22% due to an immediate 3-percentage-point dilution from custom AI data-center ramp costs, compounded by input-cost inflation outpacing product price increases.
- Restructuring Friction and Global Workforce Cuts: Annual operating cash flow dropped to $11.1 billion from $14.0 billion, forcing the rollout of unquantified global employee layoffs that create execution risk, potential restructuring charges, and regulatory labor scrutiny in key engineering hubs.
- Institutional Downgrades and FY2027 Earnings Compression: Persistent margin squeeze and lack of near-term visibility have prompted analyst downgrades and a downward revision of consensus fiscal 2027 EPS estimates from $10.54 to $9.71, capping upside despite non-handset growth.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.