


Arista Networks Inc Stock (ANET) Moved Down by 4.90% on Nov 13: What Investors Need To Know


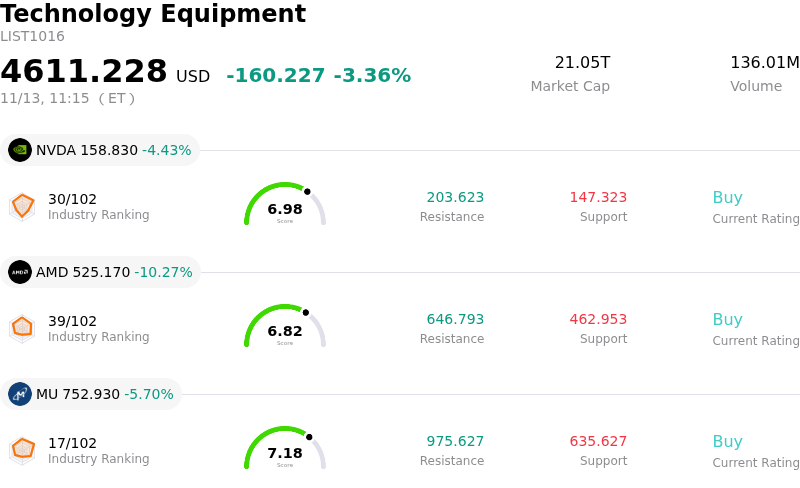
Arista Networks Inc (ANET) moved down by 4.90%. The Technology Equipment sector is down by 3.36%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 4.33%; Advanced Micro Devices Inc (AMD) down 10.27%; Micron Technology Inc (MU) down 5.70%.
What is driving Arista Networks Inc (ANET)’s stock price down today?
Arista Networks faced notable downward pressure as broader market risk aversion and profit-taking hit artificial intelligence infrastructure and networking equipment providers. Following an extended run-up driven by the buildout of next-generation data centers, investors have grown increasingly sensitive to the capital expenditure trajectory of major hyperscalers. Heightened scrutiny over the timing, financing, and return on investment of massive cloud infrastructure projects has triggered a defensive rotation across the semiconductor and networking supply chain, leaving high-multiple market leaders vulnerable to institutional de-risking.
The pullback also reflects ongoing market digestion of the company's financial outlook, particularly regarding profitability and order cadence. While overall demand for cloud switching remains robust, investor attention has zeroed in on product mix dynamics and gross margin expectations. Higher exposure to dense, rack-scale AI clusters and associated component costs has stoked concerns over near-term margin compression relative to past peak levels. Furthermore, the lumpy nature of cloud titan procurement cycles and potential moderation in sequential expansion rates have prompted market participants to reassess the near-term earnings trajectory.
Competitive developments in the high-performance networking landscape continue to generate headline sensitivity. Although Arista maintains a leadership position in open Ethernet switching architectures, persistent competition from proprietary fabrics and deeply integrated hardware solutions from major chipmakers creates ongoing uncertainty regarding long-term wallet share within primary customer accounts. With the equity trading at a premium valuation multiple, fund managers have demonstrated lower tolerance for minor guidance nuances or broader technology sector drawdowns. In the near term, price stabilization will depend on continued evidence of Ethernet market share gains in backend AI fabrics and sustained capital commitment from key hyperscale clients.
Technical Analysis of Arista Networks Inc (ANET)
Technically, Arista Networks Inc (ANET) shows a MACD (12,26,9) value of 7.548, indicating a neutral signal. The RSI at 54.449 suggests neutral condition and the Williams %R at 30.411 suggests buy condition. Please monitor closely.
Media Coverage of Arista Networks Inc (ANET)
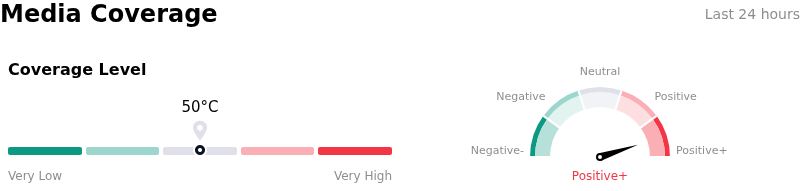
In terms of media coverage, Arista Networks Inc (ANET) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Arista Networks Inc (ANET)
Arista Networks Inc (ANET) is in the Technology Equipment industry. Its latest annual revenue is $9.01B, ranking 5 in the industry. The net profit is $3.51B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $242.44, a high of $291.00, and a low of $140.00.
More details about Arista Networks Inc (ANET)
Company Specific Risks:
- Projected Gross Margin Compression: Forward guidance highlights non-GAAP gross margins narrowing toward the 62% to 64% range, pressured by product mix shifts toward high-density scale-up AI hardware and rising component purchase commitments.
- Extreme Cloud Titan Concentration: Heavy top-line reliance on a small cluster of hyperscalers—predominantly Meta and Microsoft—leaves the business acutely vulnerable to any capex deceleration, deployment pauses, or custom silicon networking shifts across tier-one data centers.
- Sequential Growth Deceleration and Backlog Contraction: Financial disclosures revealed the first decline in deferred revenue since 2023 alongside fourth-quarter guidance indicating a sharp sequential slowdown in growth rates following front-loaded AI infrastructure deployments.
- Valuation Sensitivity and Insider Liquidation Overhang: Sustaining a premium valuation multiple near 45 times forward earnings leaves shares susceptible to sharp pullbacks on any execution slip, exacerbated by ongoing systematic executive and co-founder share liquidations under Rule 10b5-1 plans.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.