


Micron Technology Inc Stock (MU) Moved Down by 4.69% on Nov 13: What Signal Does It Send?


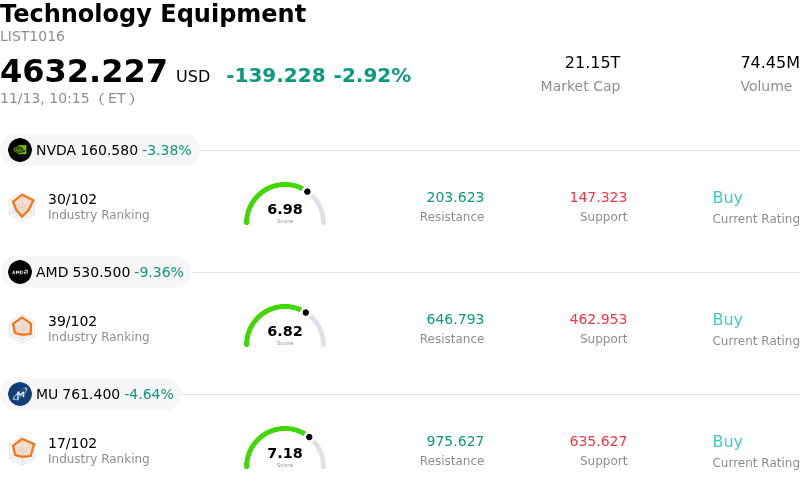
Micron Technology Inc (MU) moved down by 4.69%. The Technology Equipment sector is down by 2.92%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 3.56%; Advanced Micro Devices Inc (AMD) down 9.21%; Micron Technology Inc (MU) down 4.91%.
What is driving Micron Technology Inc (MU)’s stock price down today?
Micron Technology experienced notable downward pressure during the session, driven by a confluence of semiconductor sector profit-taking, shifting memory market dynamics, and broader macroeconomic caution impacting high-beta technology equities. Institutional investors appeared to re-evaluate near-term risk-reward profiles across hardware and memory suppliers following extended runs across the artificial intelligence infrastructure trade.
A primary catalyst weighing on sentiment is concern surrounding spot and contract pricing dynamics within conventional DRAM and NAND flash segments. While demand for high-bandwidth memory dedicated to artificial intelligence accelerators remains structurally sound, traditional client segments, particularly personal computers and mainstream smartphones, continue to demonstrate uneven recovery patterns. Industry channel checks pointing to inventory normalization and modest pricing fatigue among enterprise buyers have reignited fears that cyclical peaks in standard memory margins could arrive sooner than anticipated, prompting institutional desks to trim exposure.
Competitive dynamics within the advanced memory ecosystem also contributed to intraday weakness. Intensifying competition among major global memory fabricators to secure next-generation qualification and production allocation for high-bandwidth memory architectures has raised concerns regarding potential capacity expansion outpacing demand over the medium term. When capital expenditures across the sector ramp aggressively, markets often preemptively price in margin compression, particularly if hyperscale cloud providers signal any moderation or digestion in their hardware procurement schedules.
Broader macro conditions amplified the selloff, as elevated sovereign yields and cautious market sentiment prompted a rotation away from capital-intensive cyclical tech names into defensive assets. Technology hardware and semiconductor components bore the brunt of this positioning adjustment, with elevated implied volatility triggering systematic risk management unwinds and options-related selling.
Looking ahead, Micron remains anchored by long-term secular growth drivers in generative artificial intelligence and data center transformation, yet near-term performance will likely stay sensitive to gross margin trajectory, wafer fab equipment spending discipline, and downstream inventory digestion. Until clarity emerges regarding the resilience of enterprise contract pricing into upcoming quarters, the stock is likely to experience heightened volatility driven by headline sensitivity and institutional portfolio rebalancing.
Technical Analysis of Micron Technology Inc (MU)
Technically, Micron Technology Inc (MU) shows a MACD (12,26,9) value of -5.063, indicating a sell signal. The RSI at 41.134 suggests neutral condition and the Williams %R at 67.418 suggests sell condition. Please monitor closely.
Media Coverage of Micron Technology Inc (MU)
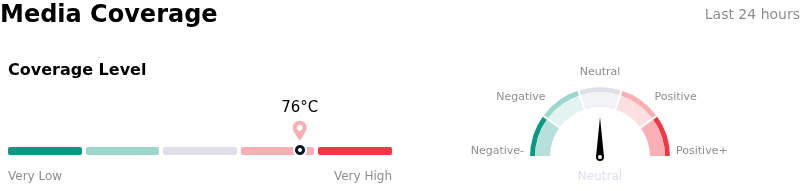
In terms of media coverage, Micron Technology Inc (MU) shows a coverage score of 76, indicating a high level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Micron Technology Inc (MU)
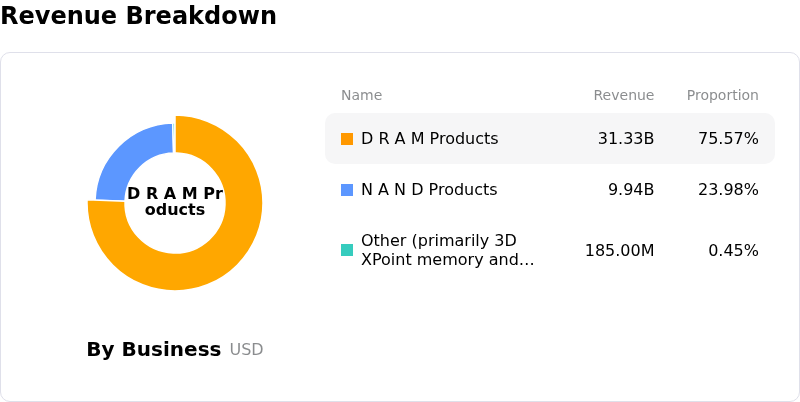
Micron Technology Inc (MU) is in the Technology Equipment industry. Its latest annual revenue is $133.19B, ranking 2 in the industry. The net profit is $84.97B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $1538.93, a high of $3000.00, and a low of $361.00.
More details about Micron Technology Inc (MU)
Company Specific Risks:
- Taiwan Fab Expansion Stoppage and Labor Impasse: An escalating profit-sharing dispute with Micron's Taoyuan labor union led to a breakdown in contract negotiations and a reported construction halt on the $4.5 billion Fab 11E expansion project; with Taiwan accounting for approximately 60% of the company's conventional DRAM fabrication, unresolved labor friction threatens near-term operational stability and future cleanroom capacity additions.
- Impending Cyclical Peak and Gross Margin Compression: Following recent warnings from industry forecasters and equity analysts that memory pricing momentum is decelerating, Micron faces heightened risk that its peak non-GAAP gross margins (guided near 86%) will erode as DRAM and NAND price increases moderate through upcoming quarters and customer resistance to high memory costs intensifies.
- AI Data-Center Capacity Delay Vulnerabilities: Recent institutional analyses warning that up to 30% of planned hyperscale data-center additions face permitting and infrastructure delays pose an immediate threat to Micron's Core Data Center revenue, leaving its high-margin server DRAM and HBM order pipeline vulnerable to sudden customer capex moderation and shipment pushouts.
- Capex Overhang Amid Aggressive Competitive Scaling: Micron's aggressive capital expenditure trajectory—projected at roughly $25 billion for the first half of fiscal 2027—creates acute operational and cash flow leverage risk as rivals Samsung, SK Hynix, and domestic Chinese producer CXMT aggressively ramp competitive memory capacity, increasing the likelihood of structural industry oversupply.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.