


Cisco Systems Inc Stock (CSCO) Opened Down by 3.81% on Nov 13: Key Drivers Unveiled


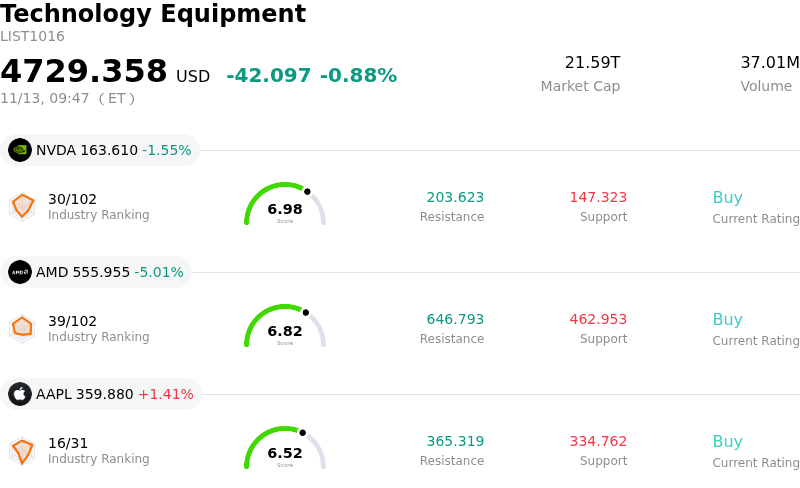
Cisco Systems Inc (CSCO) opened down by 3.81%. The Technology Equipment sector is down by 0.88%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 1.64%; Advanced Micro Devices Inc (AMD) down 5.37%; Apple Inc (AAPL) up 1.47%.
What is driving Cisco Systems Inc (CSCO)’s stock price down today?
Cisco Systems shares encountered notable downward pressure as institutional investors digested concerns regarding the company's near-term revenue trajectory and enterprise IT spending appetite. The pullback centers on persistent caution surrounding corporate networking expenditure, where enterprise clients continue to scrutinize capital outlays and extend hardware refresh cycles. With campus switching and traditional enterprise routing facing extended digestion periods, market participants have adopted a more defensive stance toward Cisco's immediate top-line expansion capabilities.
A key element weighing on sentiment is the balance between Cisco's legacy infrastructure business and its newer strategic growth engines. Although the company continues to aggressively target artificial intelligence networking and cloud hyperscaler infrastructure, these opportunities are scaling from a smaller initial revenue base. Meanwhile, elevated competition in high-performance data center switching has raised questions regarding pricing power and margin sustainability. The market appears reluctant to assign a premium multiple without clearer evidence that high-bandwidth AI Ethernet deployments can fully offset sluggish demand across broader enterprise networking segments.
Operational execution and margin dynamics have also influenced institutional positioning. The ongoing integration of major software and security assets, including Splunk, brings long-term recurring revenue benefits but carries short-term integration expenses and transition friction. These integration costs, combined with a product mix shift toward lower-margin hardware configurations in certain segments, have tempered near-term operating margin expectations. Against an uncertain macroeconomic backdrop marked by fluctuating bond yields and measured corporate spending, institutional portfolio managers have favored rebalancing away from mature tech hardware bellwethers toward areas with higher forward earnings visibility.
From an institutional research viewpoint, this downward movement reflects a valuation adjustment rather than a structural deterioration of Cisco's core franchise. The company preserves significant balance sheet strength, dependable free cash flow generation, and a resilient capital allocation framework anchored by steady share repurchases and dividends. Nevertheless, until management demonstrates an inflection in enterprise order intake and confirms accelerated monetization across its AI networking and cybersecurity portfolios, the stock is expected to face tactical headwinds as investors demand concrete proof of sustainable earnings acceleration.
Technical Analysis of Cisco Systems Inc (CSCO)
Technically, Cisco Systems Inc (CSCO) shows a MACD (12,26,9) value of -0.627, indicating a sell signal. The RSI at 40.494 suggests neutral condition and the Williams %R at 73.016 suggests sell condition. Please monitor closely.
Fundamental Analysis of Cisco Systems Inc (CSCO)
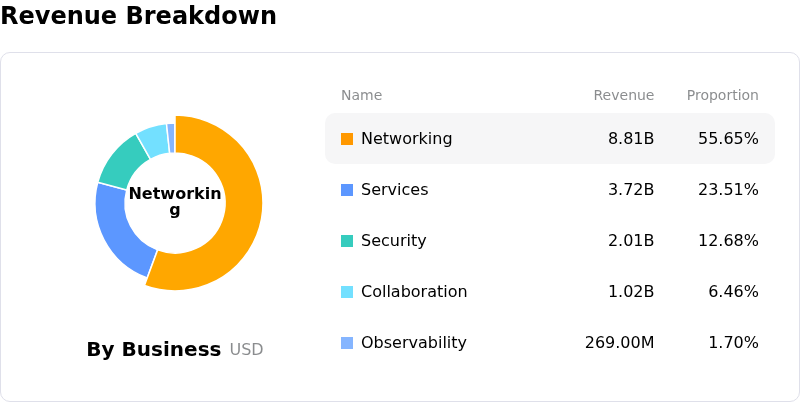
Cisco Systems Inc (CSCO) is in the Technology Equipment industry. Its latest annual revenue is $63.33B, ranking 1 in the industry. The net profit is $13.27B, ranking 1 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Cisco Systems Inc (CSCO)
Company Specific Risks:
- Gross Margin Dilution from Hyperscaler Hardware Mix: Non-GAAP gross margin contracted 250 basis points year-over-year to 65.6%—weighed down by product gross margin dropping 350 basis points to 63.7%—due to an increasing revenue mix of lower-margin hyperscaler AI infrastructure and elevated memory component costs, with forward Q2 guidance constrained to 65%–66%.
- Customer Concentration in AI Capital Expenditure: Projected fiscal 2027 AI hyperscale infrastructure revenue of $9 billion concentrates roughly 12% of total company revenue across a small group of mega-cap cloud providers, leaving top-line growth highly vulnerable to potential budget pullbacks or lumpy procurement cycles among hyperscalers.
- Stagnation in High-Margin Services and Software: While networking hardware surged 43%, higher-margin services revenue grew just 1% year-over-year while security and observability segments posted subdued single-digit growth, highlighting structural difficulties in scaling software-driven recurring revenue to counterbalance hardware-driven profitability compression.
- Optics Supply Chain Execution Bottlenecks: Management and analysts flagged operational delivery risks stemming from tight industry supply and component constraints in advanced networking hardware, particularly around high-performance optical transceivers and 1.6-terabit optical architecture required to fulfill accelerating hyperscaler design wins.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.