


Arm Holdings PLC Stock (ARM) Opened Down by 3.25% on Nov 13: Drivers Behind the Movement


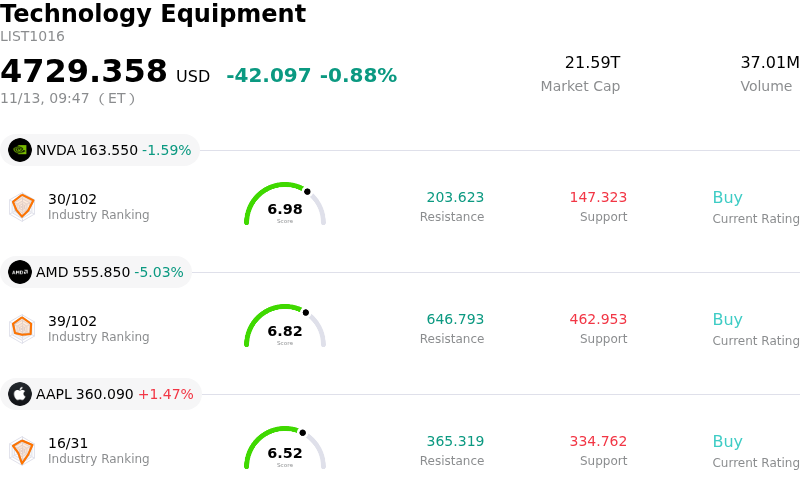
Arm Holdings PLC (ARM) opened down by 3.25%. The Technology Equipment sector is down by 0.88%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 1.58%; Advanced Micro Devices Inc (AMD) down 5.37%; Apple Inc (AAPL) up 1.47%.
What is driving Arm Holdings PLC (ARM)’s stock price down today?
Arm Holdings experienced downward pressure during the trading session, reflecting a confluence of broader semiconductor sector weakness, valuation sensitivity, and ongoing scrutiny regarding the timing of its royalty and licensing revenue growth. As high-beta technology equities faced targeted selling, Arm’s rich valuation multiple relative to the broader semiconductor complex made it an immediate candidate for institutional profit-taking and portfolio de-risking.
A primary fundamental headwind centers on the cyclical and lumpy nature of intellectual property licensing deals. While Arm continues to demonstrate structural traction with its latest architecture, institutional investors remain cautious about quarterly variance in licensing contracts and the pace of royalty monetization. Although the migration toward advanced node architectures commands higher royalty rates per chip, lingering maturity in global smartphone shipment volumes continues to temper near-term top-line reacceleration, offsetting some of the enthusiasm surrounding edge artificial intelligence integration.
Sector-level rotation also contributed to the decline. The broader semiconductor complex witnessed risk-off sentiment driven by macroeconomic uncertainties and fluctuations in benchmark sovereign yields, which disproportionately compress valuation multiples for long-duration growth assets. With market participants rotating liquidity toward cyclical hardware names trading at lower multiples or more defensive market segments, premium-valued intellectual property providers faced heightened multiple contraction.
Additionally, competitive dynamics and ecosystem developments remain a source of long-term debate among institutional allocators. Ongoing industry investments into alternative open-source architectures, such as RISC-V, coupled with legal and contractual friction across key ecosystem partners, continue to create periodic sentiment overhangs. While Arm maintains an entrenched moat across mobile and a growing footprint in hyperscale data center compute, any perceived friction in partner relationships or adoption timelines tends to trigger immediate de-risking by algorithmic and fundamental desks alike.
Looking ahead, institutional focus remains anchored on the trajectory of data center market share gains, the rate of architectural transitions across consumer devices, and the stability of forward revenue visibility. Until broader technology sentiment stabilizes and clear catalysts emerge to justify current premium multiples, Arm is likely to remain sensitive to macroeconomic volatility and sector-wide liquidity shifts.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of 2.835, indicating a neutral signal. The RSI at 41.252 suggests neutral condition and the Williams %R at 60.174 suggests sell condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
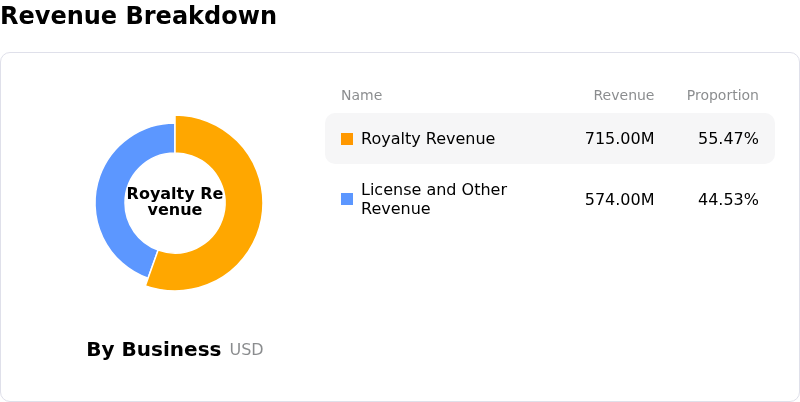
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 17 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Deceleration in Core Royalty Revenue: Despite chip shipment volumes topping 10 billion units, recurring royalty revenue growth slowed sharply to 8%, as stagnation in the broader smartphone market and elevated component pricing continue to constrain mobile royalty expansion.
- Lumpy Licensing Reliance and Analyst Target Cuts: Quarterly revenue strength was disproportionately fueled by volatile, one-off licensing agreements rather than sustainable recurring royalties, triggering a round of price target reductions from major brokerages including JPMorgan, UBS, and TD Cowen amid conservative forward guidance.
- Extreme Multiple Contraction and Options Hedging Skew: Carrying an elevated forward valuation multiple near 90 times earnings, the stock remains highly susceptible to severe intraday drawdowns, with implied volatility climbing above 74% and a steepening put skew signaling heightened institutional hedging against further multiple compression.
- Operating Margin Compression from In-House Silicon R&D: Arm's strategic pivot into designing proprietary data-center processors and escalating research and development expenditures—compounded by high stock-based compensation costs—is exerting significant pressure on reported operating margins and introducing unproven commercial execution risks.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.