


Arm Holdings PLC Stock (ARM) Moved Up by 13.03% on Nov 11: A Full Analysis


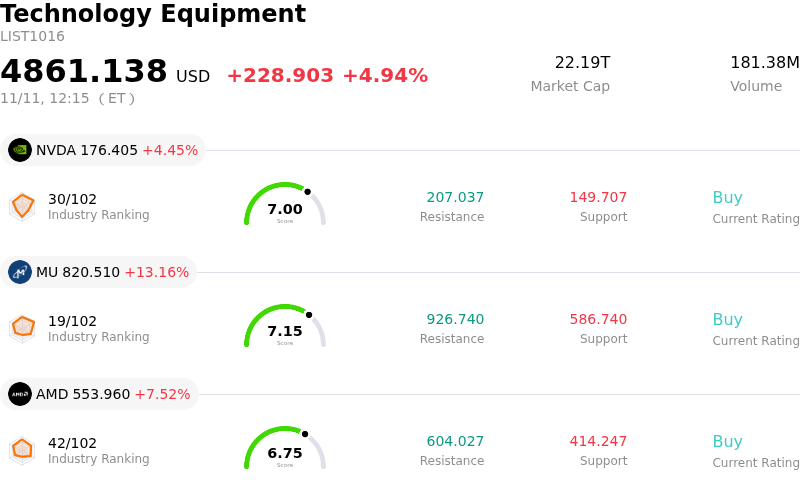
Arm Holdings PLC (ARM) moved up by 13.03%. The Technology Equipment sector is up by 4.94%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 4.56%; Micron Technology Inc (MU) up 13.19%; Advanced Micro Devices Inc (AMD) up 7.64%.
What is driving Arm Holdings PLC (ARM)’s stock price up today?
Arm Holdings experienced a sharp upward surge as institutional sentiment rebounded strongly following the digestion of its latest quarterly financial results. After an initial post-earnings pullback driven by near-term guidance caution, investors refocused on the structural strength of Arm's underlying fundamentals. High-margin licensing revenue significantly outperformed expectations, buoyed by long-term customer commitments and expanded Arm Total Access and Compute Subsystem agreements. The market recognized that near-term licensing lumpiness masked broader secular expansion, triggering an aggressive wave of institutional dip-buying and short covering.
A key driver fueling investor enthusiasm is Arm's accelerating dominance across cloud hyperscalers and generative artificial intelligence infrastructure. Royalties tied to data centers and high-performance computing continue to expand rapidly, driven by the broad adoption of custom server silicon by tier-one cloud providers, including platforms from Amazon, Google, Microsoft, and Nvidia. Confidence was further bolstered by management reaffirming supply commitments and commercial milestones for its proprietary AI and data center central processing unit initiatives, reinforcing expectations that Arm will capture a meaningful share of the booming accelerated computing market.
Broader semiconductor sector momentum and an improving macroeconomic backdrop for high-valuation growth assets provided additional support. The rotation back into mission-critical semiconductor architecture names underscored the irreplaceable nature of Arm's power-efficient compute platforms across data centers, edge AI, and mobile devices. However, investors should remain attentive to persistent risks, including consumer hardware weakness, geopolitical headwinds surrounding cross-border intellectual property compliance, and execution risks tied to scaling custom silicon delivery amid industry-wide fab capacity constraints. Overall, the powerful intraday advance reflects restored market confidence in Arm's long-term margin profile and foundational role in artificial intelligence compute.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of -0.599, indicating a sell signal. The RSI at 45.045 suggests neutral condition and the Williams %R at 43.773 suggests buy condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
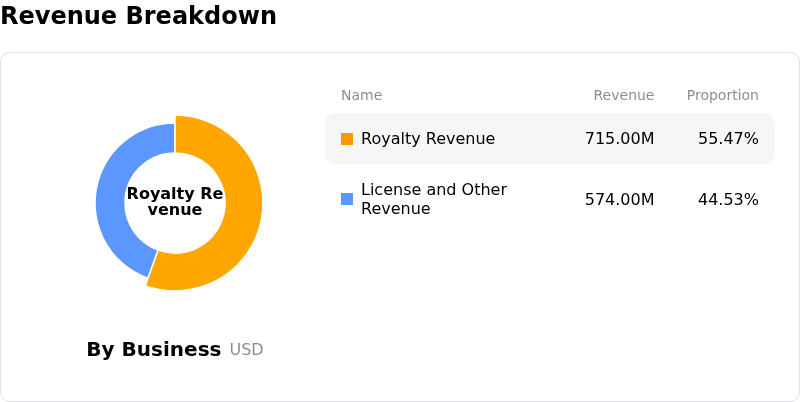
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Royalty Revenue Deceleration: Fiscal Q2 royalty revenue grew just 8% year-over-year to $670 million—missing internal and market expectations—as elevated memory pricing and prolonged smartphone weakness dampened unit volumes, exposing vulnerability to lumpiness in upfront licensing over predictable, high-margin royalties.
- Gross Margin Dilution from In-House Hardware Pivot: Transitioning toward manufacturing and directly selling proprietary Arm AGI CPUs introduces direct silicon inventory, supply, and yield liabilities that threaten to dilute Arm's ~98% pure-play IP gross margin down toward 87%, given first-generation hardware margins are projected at only 30% to 40%.
- Advanced Foundry and Packaging Execution Bottlenecks: Scaling first-party AGI CPU production to meet multi-billion-dollar delivery commitments across fiscal 2027 and 2028 subjects the company to acute supply bottlenecks in leading-edge foundry allocation and advanced packaging, risking delivery delays.
- Multiple Compression and Wall Street Target Revisions: Brokerages including JPMorgan, Barclays, UBS, and Piper Sandler reduced price targets following conservative fiscal Q3 revenue guidance, while Goldman Sachs maintained a Sell rating, warning that Arm's extreme valuation multiples are fragile in the face of decelerating royalty monetization and elevated R&D expenses.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.