


Western Digital Corp Stock (WDC) Moved Down by 3.97% on Sep 28: What Signal Does It Send?



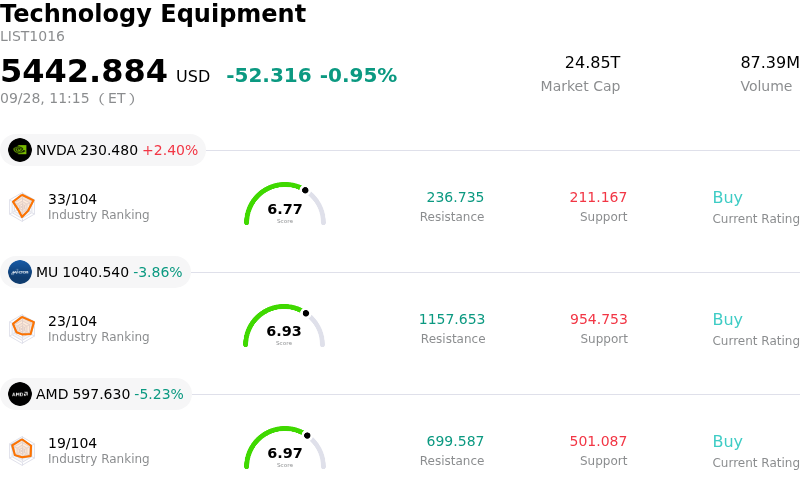
Western Digital Corp (WDC) moved down by 3.97%. The Technology Equipment sector is down by 0.95%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 2.39%; Micron Technology Inc (MU) down 3.77%; Advanced Micro Devices Inc (AMD) down 5.12%.
What is driving Western Digital Corp (WDC)’s stock price down today?
Western Digital Corporation experienced downward pressure as short-term profit-taking and sector-wide risk-off sentiment outweighed positive credit outlook developments. Following recent momentum driven by robust enterprise demand for high-capacity hard disk drives in artificial intelligence data center deployments, investors took profits to de-risk ahead of upcoming industry catalysts. The broader semiconductor and data storage complex faced tactical selling as market participants reassessed short-term valuation multiples following elevated price volatility in previous trading sessions.
From a fundamental perspective, Western Digital continues to benefit from secular tailwinds in enterprise cloud storage, backed by long-term customer commitments and an improving balance sheet profile. Credit rating agencies recently highlighted the company's solid cash flow generation and deleveraging progress, supporting its capital return initiatives. However, market focus has increasingly turned toward potential gross margin normalization and operational execution risks associated with the ongoing transition to next-generation Heat-Assisted Magnetic Recording technology. Elevated capital expenditures required to ramp next-generation manufacturing, combined with revenue concentration among major cloud providers, have contributed to investor caution regarding mid-term profitability targets.
Institutional portfolio adjustments have further amplified daily trading volatility. As fund managers rebalance hardware allocations, short-term liquidity shifts can produce pronounced price pullbacks even amidst favorable long-term demand fundamentals. Despite near-term volatility, Western Digital's positioning as a dominant supplier in the consolidated hard drive market, paired with tight industry supply discipline, continues to underpin its strategic standing within AI infrastructure portfolios.
Technical Analysis of Western Digital Corp (WDC)
Technically, Western Digital Corp (WDC) shows a MACD (12,26,9) value of 5.819, indicating a neutral signal. The RSI at 45.117 suggests neutral condition and the Williams %R at 64.852 suggests sell condition. Please monitor closely.
Fundamental Analysis of Western Digital Corp (WDC)
Western Digital Corp (WDC) is in the Technology Equipment industry. Its latest annual revenue is $12.92B, ranking 9 in the industry. The net profit is $9.29B, ranking 3 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $650.78, a high of $900.00, and a low of $428.40.
More details about Western Digital Corp (WDC)
Company Specific Risks:
- Equity Dilution and Note Redemption Overhang: Recent SEC Form 8-K filings detailing Western Digital's notice to redeem its 3.00% Convertible Senior Notes due 2028 have established active conversion rights into common stock, creating prospective share dilution and supply-side equity overhang for existing shareholders.
- HAMR Technology Transition and Margin Execution Risk: The company's ongoing transition to Heat-Assisted Magnetic Recording (HAMR) requires elevated capital spending on recording heads and media automation, exposing profitability to gross margin compression if operational costs remain elevated or if direct industry rivals scale next-generation drives faster.
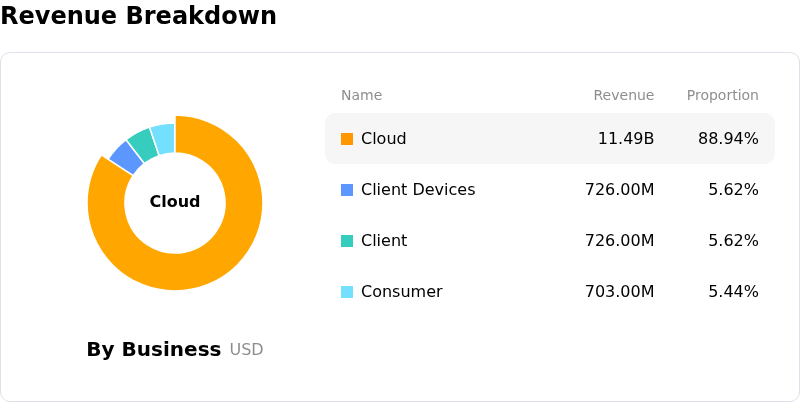
- High Customer Concentration and AI Capex Digestion: With data center storage generating nearly 89% of total revenue and its top three customers representing over 40% of sales, Western Digital remains acutely vulnerable to sharp revenue pullbacks if enterprise hyperscalers enter an AI infrastructure capex digestion period.
- Substantial Insider Selling Activity: Institutional reports highlighting over $74 million in executive insider share sales over recent months have amplified market caution, signaling potential internal skepticism around sustaining elevated valuation multiples.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.