


Micron Q4 Earnings Preview: Can Revenue Top $50 Billion, and Will MU Stock Keep Rising?



AI Podcast


Micron Technology will report fourth-quarter fiscal 2026 financial results after the market close on September 30, US Eastern Time. Driven by surging HBM and server DRAM demand, consensus estimates sit near the upper end of company guidance, projecting significant year-over-year growth. Key focus areas include fiscal 2027 first-quarter guidance, HBM4 customer qualification progress, and the sustainability of tight DRAM supply. While Wall Street maintains a bullish average price target of $1,515, short-term stock movement will depend heavily on next-quarter guidance beating market forecasts and upcoming technical resistance levels near $1,120.

TradingKey - Micron Technology (MU) will report its fourth-quarter fiscal 2026 financial results after the market close on September 30, US Eastern Time, and host an earnings call at 16:30 on the same day.
As of the close on September 23, Micron's stock price stood at $1,071.88, representing a cumulative gain of over 500% over the past 12 months. Growing demand for HBM and high-capacity server DRAM, coupled with rising memory chip prices, has driven the market to raise its expectations for Micron's revenue and profit margins.
As analyst expectations rise to the upper-middle range of company guidance, the focus of this earnings report will shift to the outlook for the first quarter of fiscal 2027, as well as whether tight DRAM supply, rising prices, and HBM demand can be sustained.
Market Expectations Sit in Mid-to-Upper Range of Company Guidance
Micron expects revenue for the fourth fiscal quarter to be $50 billion, plus or minus $1 billion; non-GAAP EPS to be $31, plus or minus $1; and non-GAAP gross margin to be approximately 86%.
According to market consensus compiled by IBD, expected revenue of $50.82 billion and adjusted EPS of $31.43 are both higher than the midpoint of the company's guidance and close to the upper end of the range. Based on these forecasts, revenue and adjusted EPS will increase by approximately 349% and 937% year-over-year, respectively.
In the third fiscal quarter, Micron's revenue was $41.456 billion, up 73.7% quarter-over-quarter; non-GAAP EPS was $25.11, and non-GAAP gross margin rose to 84.9%.
Among this, combined revenue from the cloud memory business and core data center business reached $25.293 billion, accounting for approximately 61% of total revenue, indicating that data center products have become the primary source of revenue.
HBM4 Customer Expansion and DRAM Prices Are Key Variables
Micron's HBM4 utilizing the 1β DRAM process node has begun high-volume shipments to major customer platforms, while qualification samples have been delivered to multiple end customers. Qualification and procurement schedules for other customers will impact HBM revenue growth in fiscal 2027.
HBM4E utilizing the 1γ process node remains under development, with Micron planning for mass production in 2027. Key focus areas for this earnings report include HBM4 production capacity, customer qualification progress, and shipment schedules for 2027.
Conventional DRAM pricing is also critical to performance. Visible Alpha projects Micron's fourth-quarter DRAM revenue at $38.3 billion, up 22% quarter-over-quarter, with potential to reach $42.8 billion in the first quarter of fiscal 2027, representing a 12% sequential increase.
Micron management stated that demand fulfillment rates for certain data center customers remain less than half, and tight industry supply could persist beyond 2027.
Micron has also signed 16 strategic customer agreements involving over $22 billion in cash and cash-equivalent commitments, including $18 billion in cash. Most of these agreements have a five-year term extending through 2030 and contain minimum purchase requirements, pricing mechanisms, and take-or-pay provisions. While these agreements enhance visibility into sales volumes and pricing, the commitments do not constitute current revenue.
Wall Street Average Price Target at $1,515, Labor Risks Yet to Affect Production
 [Source: StockAnalysis]
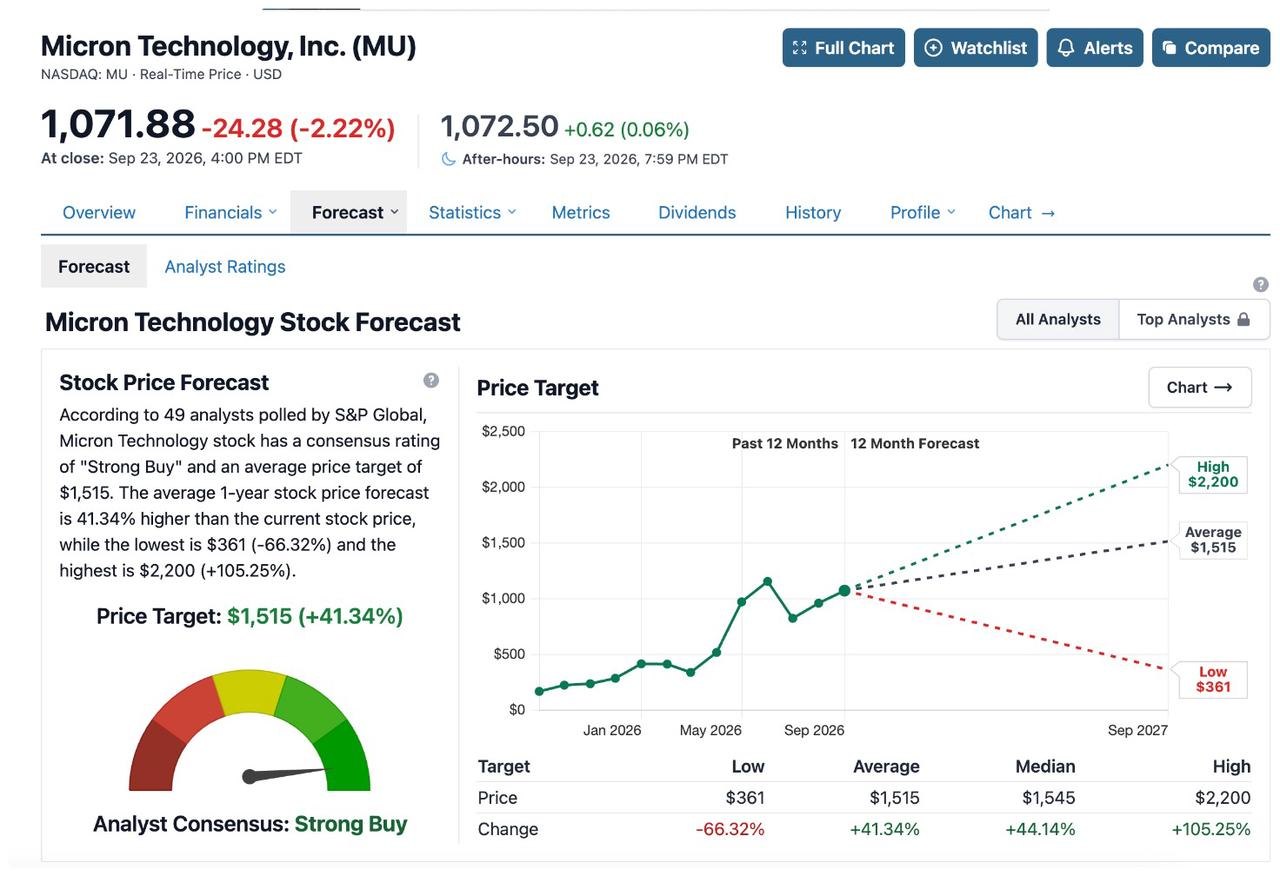
As of September 23, data from StockAnalysis shows that 49 analysts have given Micron an average price target of $1,515, implying a 41.34% upside from its current share price. Stifel maintains a price target of $1,500, while TD Cowen has a target of $1,600. The higher price targets reflect that institutions remain bullish on memory prices and profit margins. However, following the sharp rise in the stock price, earnings performance will depend more heavily on the next quarter's guidance.
Notably, the union at the Taoyuan plant in Taiwan is demanding that 15% of operating profits be allocated for employee bonuses. A second round of labor-management mediation on September 21 failed to reach an agreement, and the union plans to hold a strike vote in early October. An official strike still requires approval from more than half of all union members. As of September 24, there are no public reports indicating that plant production has been impacted.
Key focus areas of this earnings report include revenue and gross margin guidance for the first quarter of fiscal 2027, the progress of HBM4 customer qualification, and the duration of DRAM supply tightness. Meeting market expectations for the fourth fiscal quarter is merely a baseline; whether guidance for the next quarter can beat market forecasts will be the primary factor driving Micron's short-term stock price movement.
MU Stock Technical Analysis: $1,100 Becomes Key Resistance Level Ahead of Earnings
 [Source: TradingView]
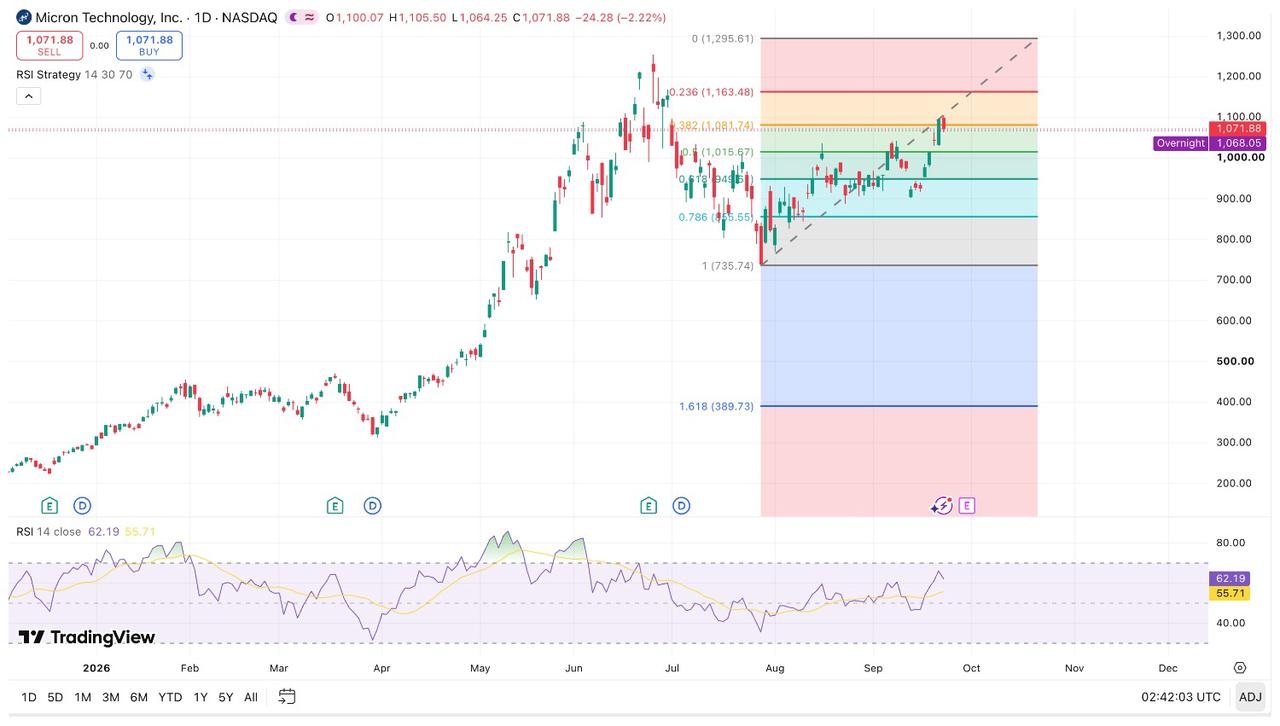
As of the close on September 23, Micron's stock price stood at $1,071.88, remaining above its 10-day, 20-day, and 50-day moving averages, which were at approximately $994, $975, and $933, respectively. The 14-day RSI was around 62, which has not yet entered traditional overbought territory, but the earnings report could amplify short-term volatility.
On the upside, $1,100–$1,120 is the primary resistance zone, with $1,105 corresponding to the intraday high on September 23. If earnings results and next-quarter guidance exceed expectations and push the stock to close firmly above $1,120, the next level to watch will be $1,200. A further breakout could see the stock retest its all-time high of $1,255.
On the downside, $1,040–$1,050 is the primary support zone. If the stock closes below this area, the next support lies at $1,000–$1,010, followed by $970–$980 near the 20-day moving average. A further breakdown below the $930–$940 area would significantly weaken the short-term bullish structure.
Micron's stock price remains in an uptrend. Holding firmly above $1,120 is expected to open up room for a move toward $1,200–$1,255, while a drop below $1,040 could lead to consolidation near $1,000.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.