


Constellation Energy Stock Forecast: Monday Earnings Put $245.52 Reclaim in Focus



AI Podcast


Constellation Energy’s upcoming earnings update will test whether long-term electricity contracts and nuclear expansion can deliver attractive returns without overburdening financing. Investors will scrutinize cash conversion, capital expenditure for Google-backed upgrades, conditional federal loan terms, and portfolio adjustments from Calpine asset disposals. Plant availability and data-centre policy risks remain critical operational watchpoints. Technically, the daily chart maintains a bearish bias while capped below the $245.52 resistance and broken rising trendline, with immediate support watched at $231.24. Monday's guidance and opening price action will determine whether the recovery target of $267.93 or downside exposure to $219.23 comes into play.
TradingKey - Constellation Energy’s (NASDAQ: CEG) Sunday outlook centres on Monday’s earnings update: can long-term electricity contracts produce attractive returns without putting excessive pressure on financing? Its nuclear expansion has customer support, but the daily chart still points to caution beneath $245.52.
Historical market data puts the latest verified completed close at $239.65 at the research cutoff, before Friday’s session finished. That is the price reference for this preview, not a confirmed weekly close. When markets reopen, guidance and project funding will be immediate tests of confidence.
Monday’s Earnings Will Test Cash Conversion
Constellation’s official calendar confirms its third-quarter earnings call for Monday, November 9, at 9 a.m. Eastern, before regular trading opens. Results remained unreleased at the research cutoff.
Second-quarter results showed adjusted operating earnings of $2.55 per share, up from $1.91, while GAAP earnings fell to $1.42 from $2.67. Full-year adjusted guidance was raised to $11.50 to $12.50 per share.
The reconciliation includes unrealised valuation movements, acquired-contract amortisation and Calpine integration costs. Adjusted earnings are therefore not interchangeable with reported profit or cash flow. I would want Monday’s update to connect earnings growth with operating cash generation after the costs of expansion.
Google Supports New Capacity, Not Immediate Revenue
The Google agreement supports 890 megawatts of additional nuclear capacity through upgrades to existing plants and a 20-year power purchase agreement. It entails more than $4.3 billion of investment, with the first upgraded capacity expected by 2028.
A separate 15-year arrangement covers 2,700 MW of supply from existing assets. The combined 3,590 MW relationship should not be described as entirely new nuclear capacity.
Long contracts make future demand easier to plan around, but construction spending comes before the additional electricity sales. The investment case depends on delivering the upgrades within budget and preserving the economics agreed with the customer.
The $5 Billion Commitment Still Has Conditions
The Department of Energy announced a conditional loan commitment of up to $5 billion on October 27 for nuclear upgrades and modernisation. Technical, legal, environmental and financial conditions must be satisfied before definitive financing documents and funding.
Constellation’s financing announcement also states that the commitment does not represent a final decision to proceed with every proposed upgrade. The programme extends beyond the Google agreement, so the entire potential loan should not be assigned to that contract.
Lower borrowing costs could improve returns, but the final rate, repayment schedule and project spending still matter. Federal financing provides another funding route; it does not remove construction risk or the obligation to repay debt.
Calpine Disposals Change Both Debt Capacity and Earnings
Constellation completed the Calpine acquisition on January 7, expanding its generation and commercial operations.
The October 14 disposal announcement confirmed the sale of the 606 MW Brazos Valley Energy Center to LS Power. Approximately 4.4 gigawatts of separate, predominantly gas-fired assets were still expected to be sold by year-end, subject to closing conditions.
Disposal proceeds can support financing flexibility, but the earnings attached to those plants also leave the group. Monday’s outlook should be assessed on the retained portfolio, with completed sales distinguished from pending transactions.
Plant Availability Determines Near-Term Output
The company’s operating update showed second-quarter nuclear generation falling to 44,160 gigawatt-hours from 45,170. Capacity factor, which measures output against potential production, declined to 93.0% from 94.8%, excluding Salem and South Texas Project. Planned refuelling outage days rose to 86 from 41.
Scheduled maintenance is necessary, so those figures do not by themselves establish deteriorating plant reliability. The next test is whether units return on schedule and avoid extended outages. More available generation helps spread fixed costs while the expansion programme absorbs capital.
Data-Centre Policy Could Delay Demand
Reuters reported that analysts identified Constellation among generators exposed to possible data-centre project delays following the US election results. That is a risk assessment, not confirmation that signed power contracts have been cancelled.
Slower customer construction could complicate the timing of new electricity demand. For the week ahead, management’s comments on delivery schedules and contractual protections may be more useful than another large headline capacity figure.
Constellation Energy Technical Analysis: $245.52 Caps the Recovery
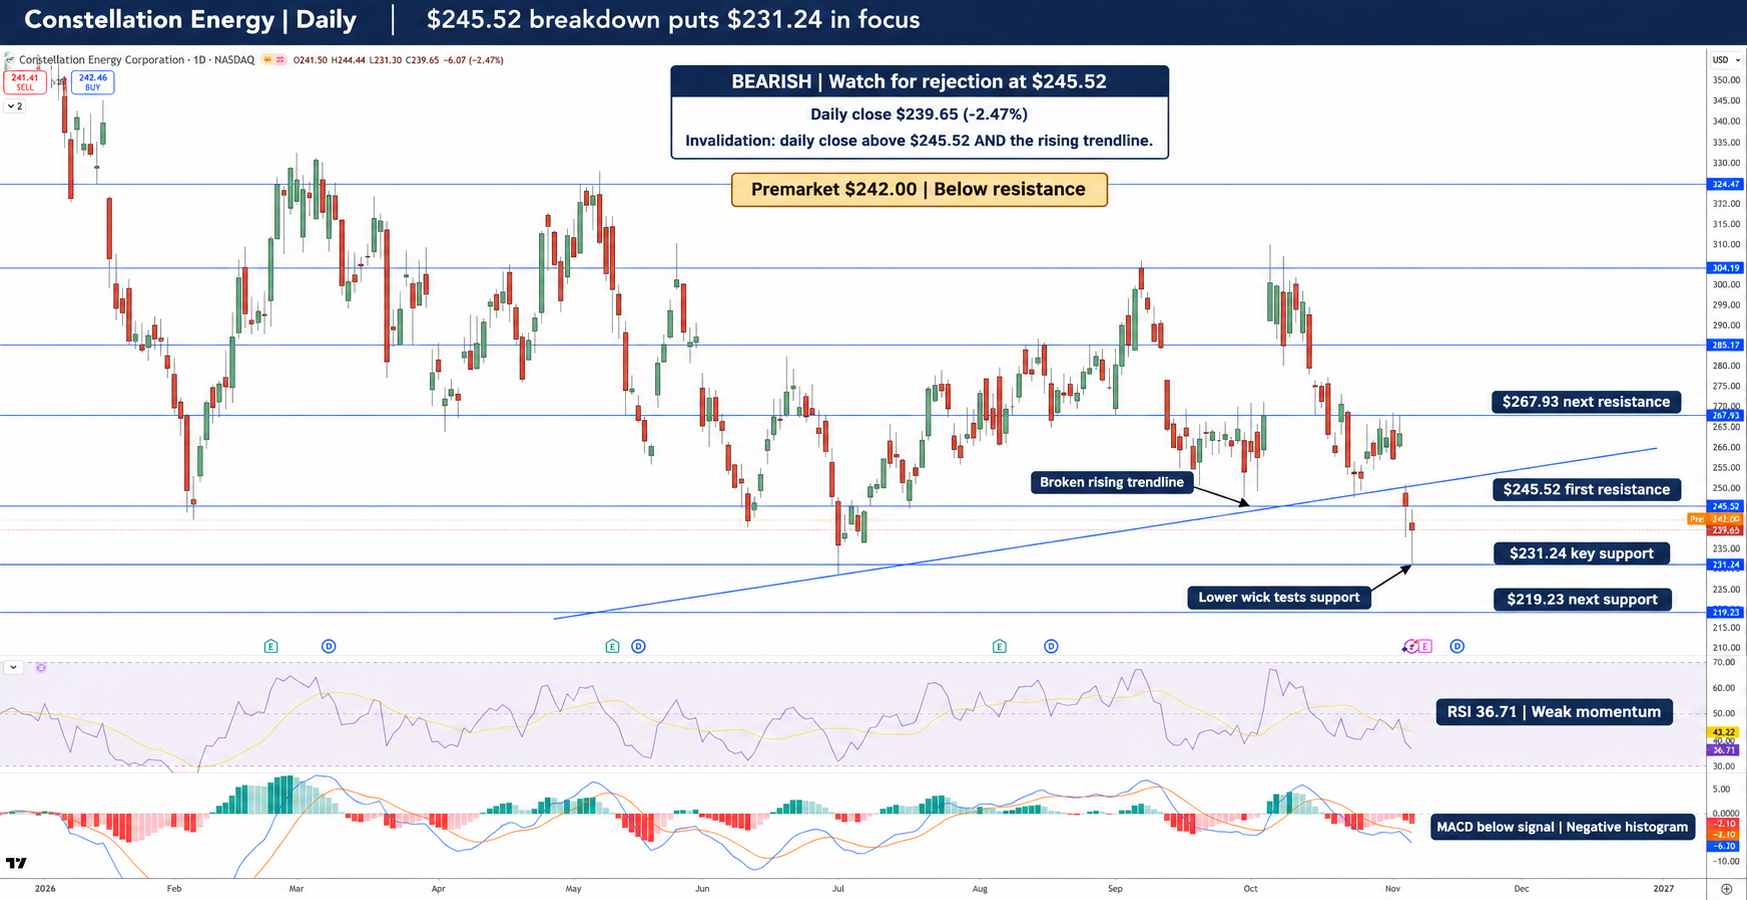
The supplied daily chart shows a break below the rising trendline and $245.52 support, followed by a rebound to the $239.65 reference close. The long lower wick shows buying near $231.24, but buyers have yet to reclaim the broken level.
I remain bearish while $245.52 caps rebounds. A failed retest would favour another move towards $231.24. A daily close below that support would strengthen the downside case and expose $219.23, rather than treating an intraday dip alone as confirmation.
RSI, a momentum gauge, stands at 36.71 and signals weakness without being oversold. MACD remains below its signal line with a widening negative histogram, consistent with continued selling pressure.
CEG Price Chart - Source: Tradingview
A daily close above $245.52 and the rising trendline would invalidate the immediate breakdown view and bring $267.93 into focus. Because earnings can cause an opening gap, Monday’s price action must confirm whether these earlier chart levels still define the trade.
Key Levels
- Latest verified completed close: $239.65 at the pre-weekend research cutoff
- Immediate resistance: $245.52, then the broken rising trendline
- Upside recovery target: $267.93
- Immediate support: $231.24
- Downside target: $219.23
- RSI: 36.71, weak but not oversold
FAQ
Why is Constellation Energy in focus on Monday?
Its earnings call will test guidance, nuclear availability and the funding outlook for contracted expansion.
Has Constellation received the $5 billion federal loan?
The announced commitment is conditional. It should not be treated as completed funding or approval of every project.
Bottom Line
Long-term contracts support growth, but financing and plant execution determine returns. The immediate chart bias remains bearish until CEG closes above $245.52 and the trendline. Losing $231.24 would expose $219.23.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.