


Berkshire Hathaway Q3 Earnings Preview: Insurance Profits and Cash Deployment in Focus as UBS Raises Class B Price Target to $628



AI Podcast


Berkshire Hathaway will report Q3 2026 earnings on the morning of November 7, Eastern Time, marking a pivotal period under new CEO Greg Abel. Analysts project revenue of $97.3 billion, up 2.5% year over year, with EPS declining 5.6% to $5.91. Key investor focuses include insurance underwriting performance, capital allocation strategies regarding massive cash reserves, and the growth trajectory of non-insurance segments like rail and energy. Wall Street maintains a mixed outlook, with average price targets around $555.67 alongside a high target of $628.

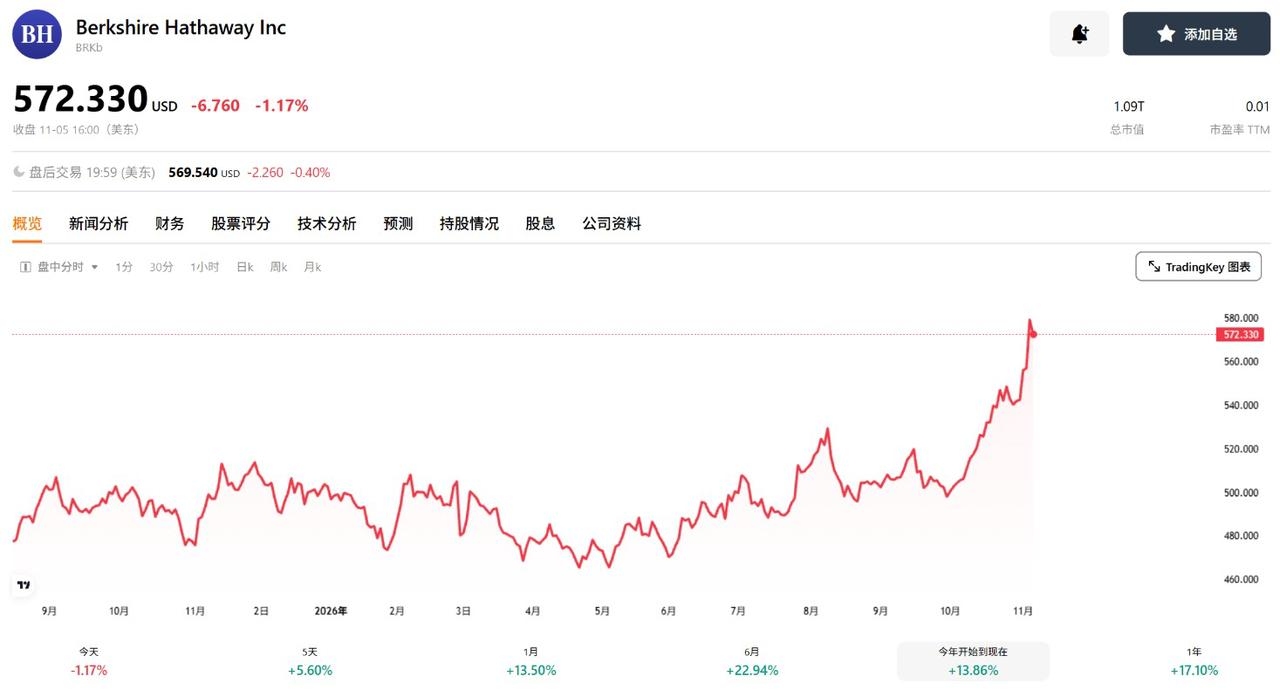
TradingKey - Berkshire Hathaway (BRK.A, BRK.B) will report its third-quarter 2026 earnings on the morning of November 7, Eastern Time. As of the close on November 5, Class B shares stood at $572.33.
[Source: TradingKey]
Berkshire is a major U.S. conglomerate holding company whose businesses span insurance, rail transportation, energy, utilities, manufacturing, services, and retail, while also holding a substantial portfolio of publicly traded equities. Its diversified business portfolio and massive investment assets mean that its financial results are not only influenced by the operating performance of each business, but also closely tied to capital markets and investment allocations.
On January 1, 2026, Greg Abel officially took over as CEO, while Warren Buffett stepped down as chairman of the board in September. The market will focus on Abel's operating performance and capital allocation strategy following his appointment.
Key focuses of this earnings report include insurance underwriting profit, the performance of the rail and energy businesses, and cash deployment. As of the end of the second quarter of 2026, Berkshire held approximately $364.7 billion in cash and U.S. Treasury bills, and was a net buyer of approximately $20 billion in equities in the second quarter.
Investors will focus on changes in cash reserves during the third quarter, as well as whether the company continues to add to stock holdings, repurchase shares, or pursue major acquisitions.
Market Expectations and Previous Quarter Review
According to Zacks data, analysts expect Berkshire Hathaway's third-quarter revenue to be approximately $97.3 billion, up 2.5% year over year, with earnings per share projected at $5.91, down 5.6% year over year. This indicates that the market expects modest revenue growth, but earnings per share could decline.
Looking back at the second quarter, Berkshire's operating profit rose 16.3% year over year to $12.983 billion. Among these, after-tax profits for railroad, energy, and manufacturing, service, and retailing businesses grew by 6.3%, 26.9%, and 24.1%, respectively.
In contrast, insurance underwriting profit fell 13.1% year over year to $1.731 billion, while insurance investment income dropped 9.1% to $3.059 billion. In addition, the company repurchased approximately $4.5 billion of stock in the second quarter.
Insurance Profit and Cash Allocation Are Key Highlights
The insurance business is a vital source of Berkshire's operating profit, and changes in third-quarter underwriting profit and investment income warrant close attention.
In the second quarter, insurance underwriting profit fell 13.1% year-over-year to $1.731 billion, while insurance investment income dropped 9.1% to $3.059 billion. Among these, a decline in GEICO's underwriting profit partially offset growth across other insurance businesses, while investment income was weighed down by lower interest rates.
Looking ahead to the third quarter, Morningstar expects insurance underwriting performance could remain weak due to intensifying competition in the insurance market and slowing premium growth. However, non-insurance businesses such as railroad, energy, and manufacturing are expected to partially offset pressure on the insurance segment. Investors should watch whether underwriting profit improves and whether investment income stabilizes.
Cash allocation is also a key focus of this earnings report. As of the end of June, net cash, cash equivalents, and short-term U.S. Treasury bills held by Berkshire's insurance and other businesses totaled approximately $359.2 billion.
On July 24, the company completed its acquisition of homebuilder Taylor Morrison (TMHC) for a cash consideration of approximately $6.8 billion. Cash reserves and the scale of share repurchases at the end of the third quarter will reflect capital allocation since Abel took over.
Alphabet (GOOGL) is also an investment worth watching. As of the end of June, Berkshire held approximately 106 million shares of Alphabet with a market value of about $37.8 billion, making it its third-largest equity holding.
Compared with the first quarter, the number of shares held increased by about 83%. Whether the position was further increased or trimmed in the third quarter will await disclosure in subsequent 13F filings.
Wall Street's Highest Price Target for BRK.B Reaches $628
[Source: StockanAlysis]
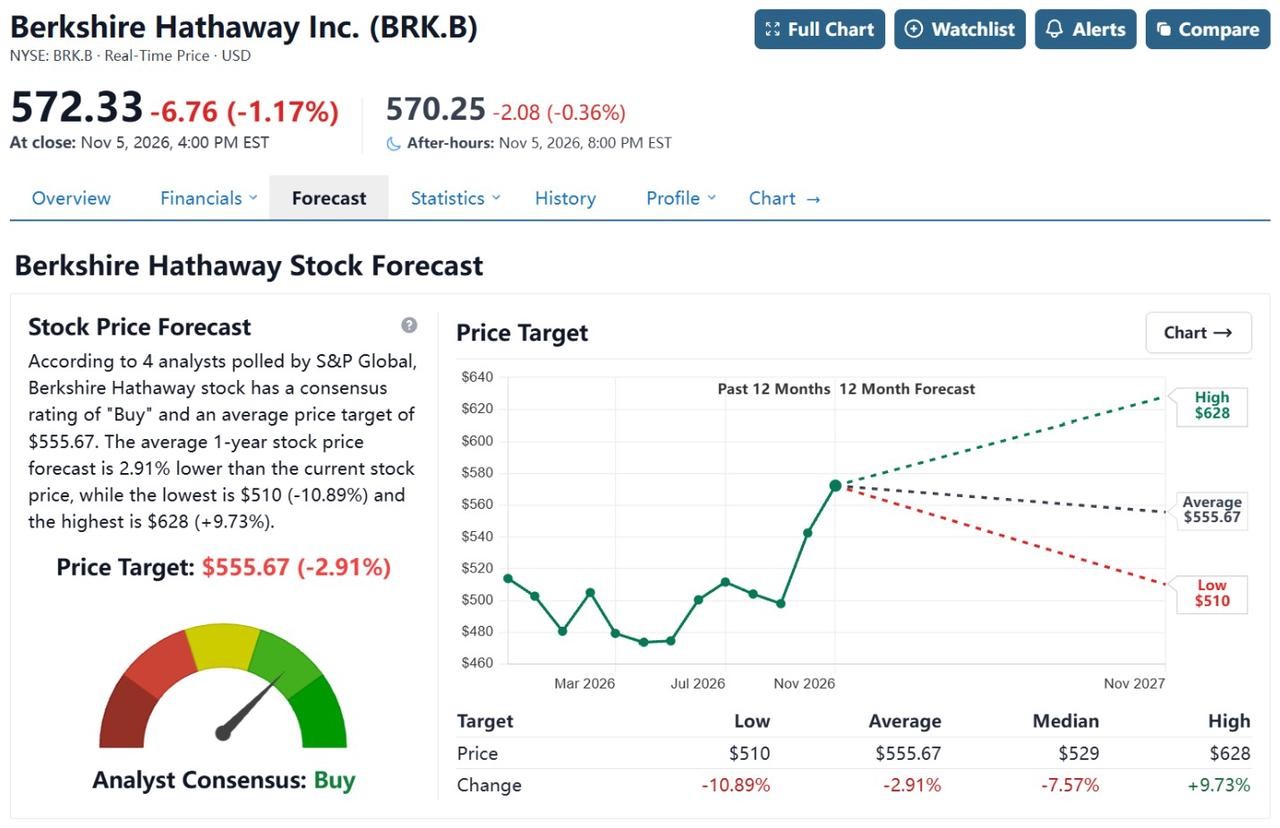
As of November 6, according to StockanAlysis, analysts' average price target for Berkshire Hathaway Class B shares was $555.67, implying a 2.91% downside from the current stock price; the highest target was $628, and the lowest was $510.
On October 22, UBS analyst Brian Meredith raised his price target for Berkshire Class B shares from $604 to $628 and maintained a Buy rating. Morningstar expects that third-quarter insurance underwriting profits may decline, but non-insurance businesses such as railroads and energy are poised to drive mid-to-high single-digit growth in operating earnings.
In the third quarter, whether insurance underwriting profits improve and whether railroad and energy businesses sustain their growth will directly affect overall operating performance. If the insurance business remains under pressure, whether other segments can offset the profit shortfall and how Abel allocates the massive cash pile will also be key areas of focus for investors.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles











Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.