


Airbnb Stock Price Forecast: Surges Nearly 6% Ahead of Earnings Nearing $180 Mark; Earnings Beat Could Drive ABNB Up Another 10%



AI Podcast


Airbnb will report its third-quarter 2026 financial results after the U.S. market close on November 5, with analysts expecting revenue of approximately $4.75 billion and EPS of $2.85 to $2.89. Investor focus centers on global travel demand, platform bookings, and margin performance, as rising operational expenses in technology and AI could pressure profitability. Technically, the stock faces immediate resistance at $180, supported by an RSI of 58.87 indicating strengthening bullish momentum. A breakout above $180 could target $183.71 and $193.32, while primary downside support is anchored at $176.
TradingKey - Airbnb (ABNB) will report its third-quarter 2026 financial results after the U.S. market close on November 5. Ahead of the earnings release, capital placed early bets on resilient travel demand and platform bookings, driving the company's stock up 5.64% to $176.37.
The market expects Airbnb's third-quarter revenue to be approximately $4.75 billion, with earnings per share of around $2.85 to $2.89. The company previously guided for revenue between $4.69 billion and $4.77 billion; therefore, whether actual revenue can exceed the top end of the guidance range and whether fourth-quarter booking trends remain stable will be the core factors determining the stock's direction.
The quarter's performance largely depends on whether global travel spending continues to remain active. Airbnb expects third-quarter nights and experiences booked to achieve low double-digit growth, with average daily rates also expected to rise moderately. If bookings and daily rates improve in tandem, the platform's gross booking value will be supported, further translating into revenue growth. Demand trends across North America, Europe, Latin America, and the Asia-Pacific region are particularly worth watching, while user growth in expansion markets such as India and Brazil could also provide new booking sources for the platform.
Unlike traditional hotel operators, Airbnb primarily relies on its platform to connect hosts with travelers, and its business expansion does not entirely depend on capital investments in owned properties. As the platform's reach expands, a mutually reinforcing relationship can develop among listing supply, user activity, and booking conversion rates. However, growth in travel demand does not necessarily mean a corresponding improvement in profitability. The company's ongoing investments in technology, marketing, and artificial intelligence could increase operating expenses; if incremental revenue fails to offset rising costs, margin performance may fall short of market expectations.
Profit margin is another metric in this earnings report that could readily influence the stock price. The third quarter is typically one of Airbnb's more profitable quarters of the year, so the market will closely compare this quarter's margin performance with that of the prior-year period. The company previously noted that the timing of investment spending could leave its third-quarter adjusted EBITDA margin slightly below the year-ago period. Even if revenue and booking metrics perform well, if margins decline more than anticipated, investors may still reassess the quality of the company's earnings.
Meanwhile, Airbnb is trying to leverage artificial intelligence to improve platform experiences and explore growth opportunities beyond its core accommodation business. AI is expected to be applied across search, itinerary planning, customer service, and dynamic pricing, helping consumers find suitable listings faster while enabling hosts to manage pricing and inventory more effectively.
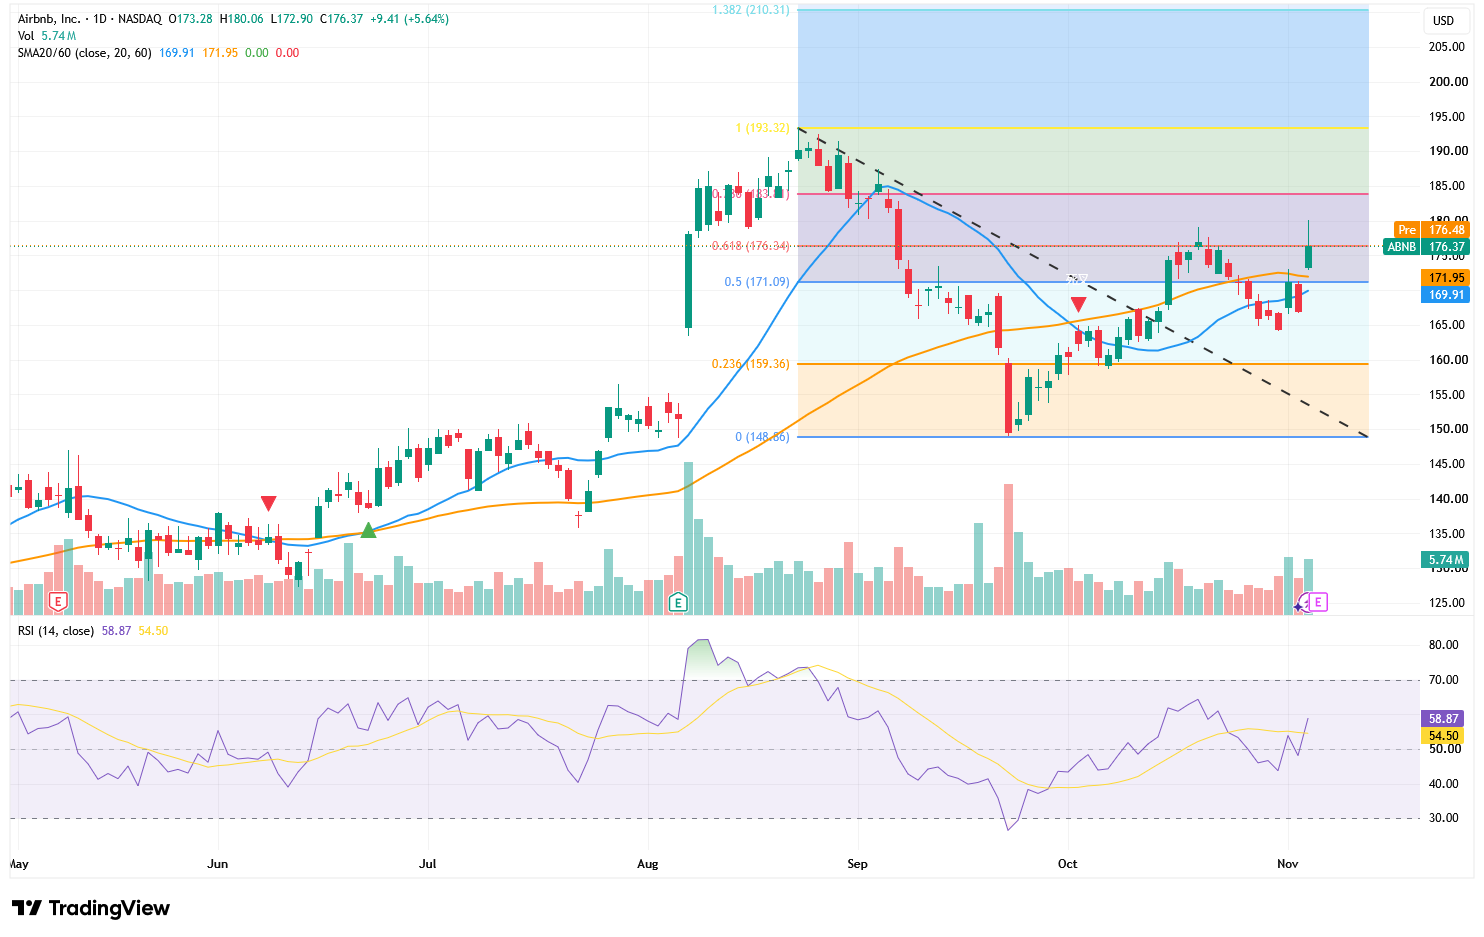
Source: TradingView
From a technical perspective, $180 represents Airbnb's most immediate resistance level. If the stock can hold $176 following the earnings release and break out above $180 on heavy volume, the first upside level to watch is the 0.786 retracement level at $183.71, followed by a test of the prior high of $193.32, offering potential upside of nearly 10%.
The RSI currently stands at 58.87, having risen back above its signal line of 54.50 while remaining below the overbought territory, indicating that bullish momentum is strengthening with further room to run. Primary support on the downside is located at $176; if earnings miss expectations and the stock breaks below this level, shares could pull back to test the $171–$172 dual moving average zone, with further support at $169 and $159.36.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.