


Arista Networks Stock Forecast: $7 Billion AI Target Meets Resistance at $188.47



AI Podcast


Arista Networks reported strong third-quarter results, driven by surging AI demand, prompting management to double its 2027 AI networking revenue target to $7 billion. Despite robust Q3 revenue and cash reserves, rising inventories and supplier commitments indicate execution risks tied to component availability and deployment timing. Technically, the stock remains vulnerable. While near-term financials are constructive, the shares struggle below key moving averages, with immediate resistance at $183.60. A failure to reclaim this level risks a pullback toward support at $164.06, leaving the broader technical outlook cautious until a decisive breakout above $190.62 occurs.
TradingKey - Arista Networks (NYSE: ANET) closed November 4 at $178.48, up 5.04% in the first full session after earnings. Buyers pushed the stock to $188.53, then surrendered most of the intraday advance. The high cleared the 50-day moving average by just six cents, according to Arista’s stock data and the daily chart.
Management aims to double its AI networking revenue target to $7 billion in 2027. Arista has already committed $11.4 billion to suppliers across its business. How quickly components become shipments will say more about that forecast than another design announcement.
AI Networks Would Account for Nearly Two-Fifths of Sales
Arista expects 2027 revenue to grow 38% to 40%, reaching roughly $18.5 billion at the midpoint. Its $7 billion target for AI fabrics, the networks that let clusters of AI processors exchange data, compares with a $3.5 billion target for 2026. Management also expects campus networking revenue to reach about $2 billion, according to the earnings call.
At those targets, AI fabrics would account for about 38 cents of every sales dollar. Campus networks, which connect devices across offices and other facilities, give Arista a second source of growth. Even so, a large data-center customer pushing a deployment into the following quarter could move the reported sales figure considerably.
A $134.5 Million Investment Gain Lifted Reported Earnings
Third-quarter revenue reached $3.66 billion, up 58.5% from a year earlier and 20.5% from the previous quarter. GAAP diluted earnings rose to $1.22 per share from $0.67. That figure includes a $134.5 million pretax gain on strategic investments. Arista excludes that gain alongside other adjustments when calculating adjusted EPS, which rose to $1.20 from $0.77, according to its earnings reconciliation.
The operating margins give a clearer view of the networking business. Adjusted gross margin fell from 65.2% to 64.0%, yet adjusted operating margin rose from 48.6% to 49.1%. Arista kept less gross profit per dollar of sales, but spread operating expenses over enough additional revenue to more than offset that pressure.
The $11.4 Billion Commitment Runs From Arista to Its Suppliers
Inventory rose from roughly $2.5 billion to $3.2 billion in one quarter. Over the same period, purchase commitments climbed from $9.7 billion to $11.4 billion as Arista secured components for future deliveries. Those figures measure two different stages of procurement. Inventory is already on hand, while purchase commitments cover orders placed with suppliers.
Securing scarce parts early can help Arista deliver when a customer is ready. If that customer delays a project, Arista can end up holding the parts longer before it ships and collects payment. I would watch whether inventory growth eases as sales rise. The company generated about $1.2 billion in operating cash flow and ended September with roughly $14.4 billion in cash and marketable securities, giving it room to finance that lead time.
The New Rack Design Has a Longer Timetable
Arista’s Etherlink SU-144 design connects up to 144 accelerators inside one rack. Its use of open Ethernet standards gives customers a way to connect processors from different suppliers. AMD, Broadcom, Meta and Microsoft were among the partners named in the architecture announcement.
Management expects trials for this scale-up technology in 2027 and production in 2028. That timetable matters when assessing next year’s $7 billion target. The nearer-term sales opportunity is connecting systems across racks and data centers. A successful trial within a rack would support the longer-term case, but investors would still need evidence of production orders.
Fourth-Quarter Deliveries Are the First Check
Arista’s fourth-quarter guidance calls for revenue of $3.9 billion to $4.0 billion, an adjusted operating margin of 48% to 49% and adjusted EPS of $1.26 to $1.30. At the revenue midpoint, sales would grow about 8% sequentially. Meeting that target while holding margins would show that higher component commitments are supporting profitable shipments.
CFO Chantelle Breithaupt is scheduled to speak at the UBS Global AI and Tech Conference on December 1. Component availability and the timing of customer deployments are the two questions worth listening for at that investor event.
Arista Technical Analysis: $183.60 Is the First Recovery Test
ANET finished the earnings session just $1.82 above its $176.66 low despite gaining 5.04% on the day. The advance briefly cleared the 50-day exponential moving average at $188.47, but buyers lost that level and the 100-day average at $183.60 before the close. That retreat leaves $183.60 as the first test of whether demand can hold beyond an intraday bounce.
I lean slightly bearish while the stock struggles to reclaim those averages. The daily relative strength index recovered to 45.08, still below its midpoint. MACD, another measure of momentum, remains below its signal line. Together they leave room for a bounce but offer little confirmation that buyers have regained control.
Another rejection at $183.60 would put the $176.66 session low back in view, followed by $164.06 support. A daily close below $164.06 would expose $149.38. On the upside, a daily close above $190.62 would clear both averages and invalidate the near-term bearish call.
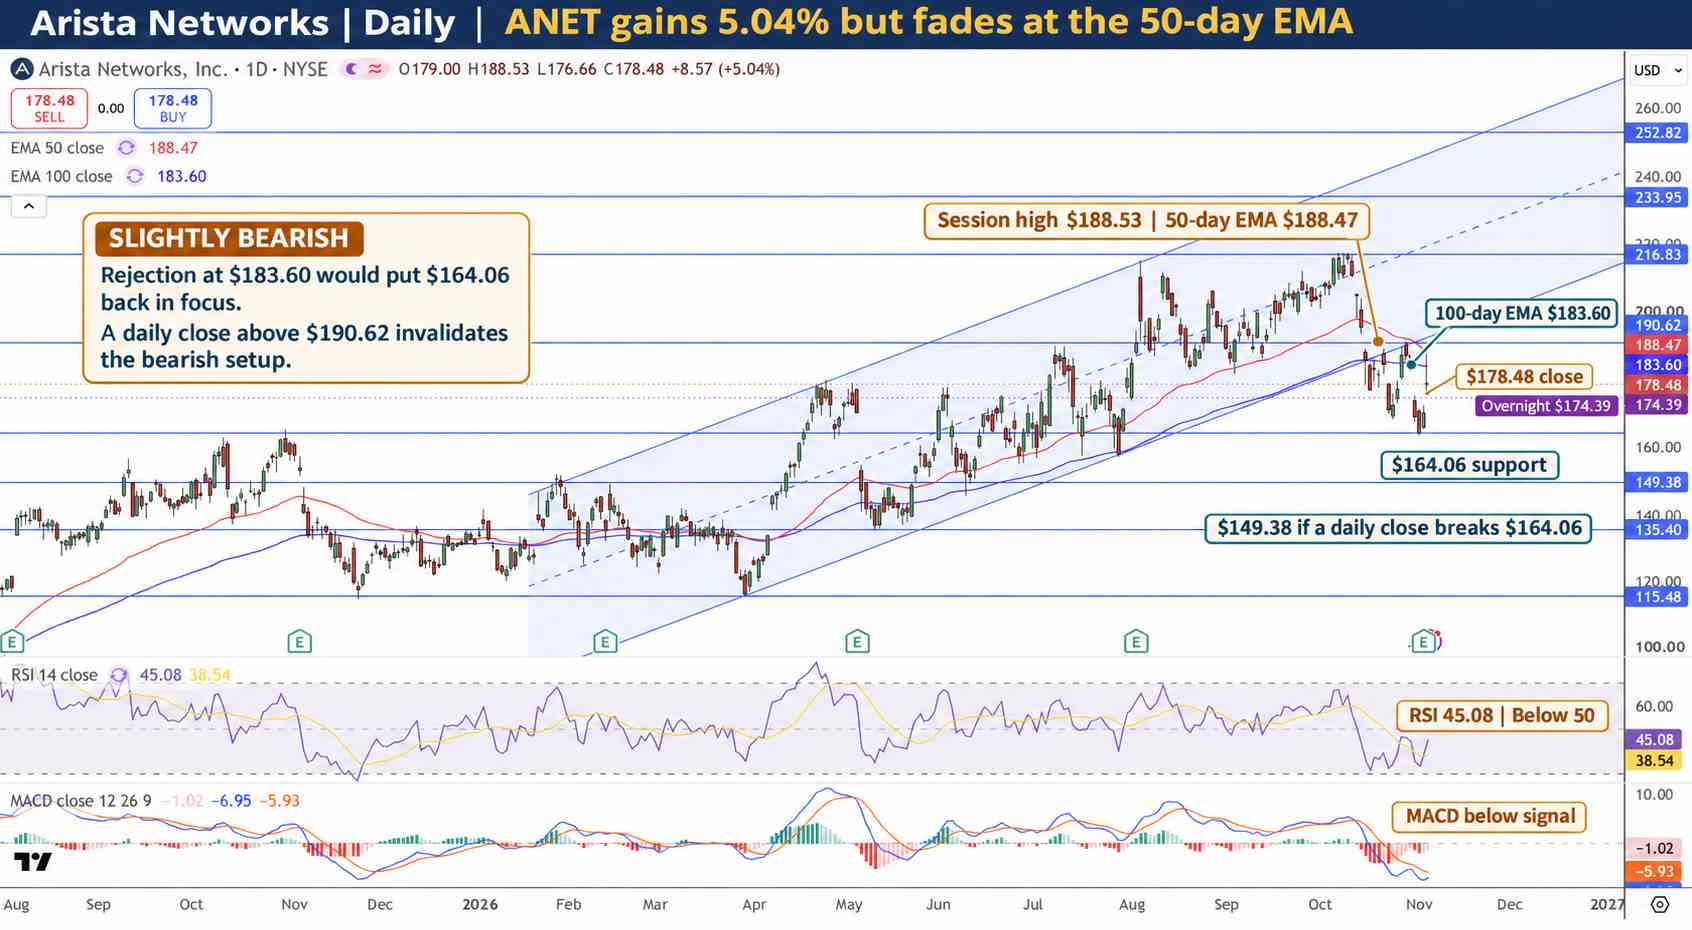
ANET Price Chart - Source: Tradingview
Key Levels
- Latest completed close: $178.48 on November 4
- Immediate resistance: $183.60
- Upside tests: $188.47, then $190.62
- Immediate support: $176.66
- Downside targets: $164.06, then $149.38
- Daily RSI: 45.08, below neutral
FAQ
Is Arista’s $7 billion AI target already under contract?
Management gave a 2027 revenue target. The $11.4 billion commitment figure measures Arista’s own purchases from suppliers.
What would turn ANET’s chart more constructive?
Recovering $183.60 would be a first step. A daily close above $190.62 would clear both moving averages and invalidate the bearish setup.
Bottom Line
Arista’s outlook is constructive if shipments rise fast enough to absorb its inventory build without eroding margins. The chart is less convincing. Until buyers reclaim $190.62 on a daily close, a failed rebound at $183.60 leaves $164.06 in play.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.