


Qualcomm Q4 Handset Revenue Drops 26%, Dragging Down Overall Revenue and Earnings; Stock Falls 6% After Hours



AI Podcast


Qualcomm reported Q4 FY2026 revenue of $10.322 billion and adjusted EPS of $2.17, both slightly beating expectations despite year-over-year declines. Record automotive growth and renewed licensing agreements offered bright spots, though sustained weakness in the handset segment and rising input costs weighed on overall profitability. GAAP net income swung to $1.251 billion, largely driven by tax shifts. For Q1 FY2027, the company guided adjusted diluted EPS between $2.15 and $2.35. Looking ahead, Qualcomm projects non-handset revenue to surge over 60% year-over-year, targeting $5 billion in data center revenue as part of its strategic inflection.

TradingKey - Qualcomm (QCOM) reported its Q4 FY2026 financial results on November 4. Quarterly revenue and adjusted EPS slightly beat market expectations, but a decline in the handset business continued to weigh on overall revenue and earnings. The automotive segment set a quarterly revenue record, while the company reiterated its FY2027 data center revenue target of $5 billion.
Qualcomm's fourth-quarter GAAP revenue came in at $10.322 billion, down 8% year-over-year, beating the market expectation of $10.110 billion. Adjusted EPS reached $2.17, down 28% year-over-year, beating expectations of $2.16 by $0.01.
As of press time, its shares fell over 6% in extended trading to $161.97.
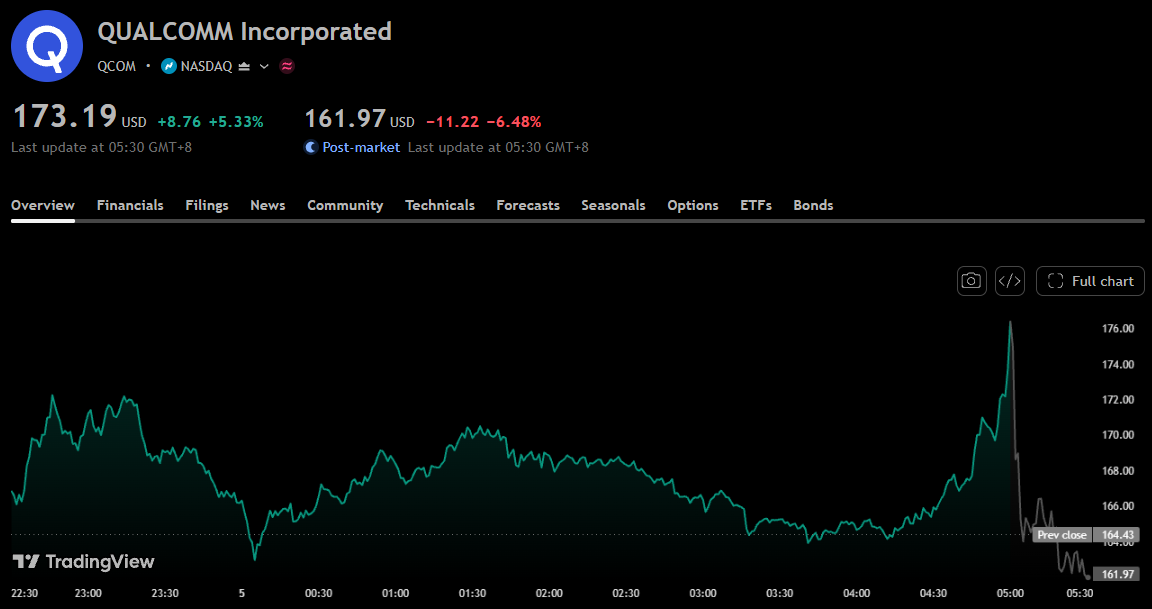
Qualcomm stock chart; Source: TradingView
By business segment, revenue for QCT (the chip business) was $9.015 billion, down 8% year-over-year. Within QCT, handset revenue fell 26% year-over-year to $5.137 billion; automotive revenue surged 89% year-over-year to a record $1.990 billion; and Internet of Things (IoT) revenue grew 4% year-over-year to $1.888 billion. Combined automotive and IoT revenue rose 36%, but failed to offset the contraction in the handset segment. QCT pre-tax profit fell 26% year-over-year to $2.142 billion, with the pre-tax margin narrowing from 29% to 24%.
QTL, the technology licensing segment, recorded revenue of $1.304 billion, down 7% year-over-year; pre-tax profit fell 10% year-over-year to $918 million, with the pre-tax margin slipping from 72% to 70%. The company disclosed that it has renewed long-term QTL licensing agreements with Apple, Huawei, and Transsion.
On profitability, GAAP operating profit decreased to $1.356 billion from $2.918 billion in the same period last year; net income was $1.251 billion, compared with a net loss of $3.117 billion in the year-ago period; diluted EPS was $1.17, compared with a loss per share of $2.89 a year earlier. Income tax benefit for the quarter was $78 million, compared with an income tax expense of $6.088 billion in the prior-year period; thus, the shift from loss to profit in GAAP results should be viewed in light of tax changes. Non-GAAP net income was $2.332 billion, down 28% year-over-year.
For the full year, GAAP revenue for FY2026 was $43.120 billion, down 3% year-over-year; GAAP EPS was $12.70, up 153% year-over-year, which included a $5.7 billion income tax benefit—or $5.32 per share—from the release of the valuation allowance on deferred tax assets in Q2. Full-year adjusted EPS was $10.54, down 12% year-over-year.
For Q1 FY2027, Qualcomm expects revenue between $10.4 billion and $11.2 billion, with a midpoint of $10.8 billion; GAAP diluted EPS is expected to be $1.03 to $1.23, and adjusted diluted EPS is projected at $2.15 to $2.35, with a midpoint of $2.25. QCT revenue guidance is $9.0 billion to $9.6 billion, and QTL is $1.3 billion to $1.5 billion; starting this quarter, QCT revenue guidance includes the data center business.
Costs remain a pressure point in the profitability outlook. The company stated that input costs, including wafer fabrication, packaging and testing, advanced packaging, memory, and other materials, are rising across the board. It is reflecting these cost changes through product pricing, with the full impact of these measures expected to materialize in QCT's gross margin in the second half of FY2027.
Qualcomm Chief Executive Officer Cristiano Amon stated that FY2027 will mark an inflection point for non-handset revenue growth, driven in part by the scaling of the data center business. The company expects non-handset revenue to grow by more than 60% year-over-year and reiterated its target of $5 billion in data center revenue.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.