


Oracle Stock Forecast: Tencent Report Tests AI Funding as Rebound Faces $131.56



AI Podcast


Oracle shares face headwinds amid an unconfirmed $7 billion Tencent contract cancellation and a $20 billion stock-and-bond offering closing on November 4, which introduces equity dilution and high-coupon interest obligations. Although cloud infrastructure revenue rose 121% to $7.4 billion, capital expenditures of $28.5 billion resulted in a $5.4 billion negative free cash flow. Management targets positive free cash flow by the second half of fiscal 2028. Technically, the stock remains vulnerable below $131.56 resistance, with momentum indicators signaling caution as investors await clarity on cash conversion and contract durability ahead of December earnings.

TradingKey - Oracle (NYSE: ORCL) closed November 3 at $126.19, up 5.85%, according to Stock Analysis. The rebound now faces a reported Tencent contract cancellation just as Oracle’s $20 billion stock-and-bond offerings reach their scheduled closing date. The contract’s financial impact remains unconfirmed.
Cloud demand remains strong, but funding that growth is expensive. With the daily chart still below $131.56 resistance, the next move depends on whether buyers can sustain the rebound while Oracle addresses contract and cash-flow concerns.
Tencent Report Puts Contract Durability in Focus
According to Reuters’ report, citing the Financial Times, Oracle canceled a chip-leasing agreement with Tencent estimated at $7 billion following pressure from the Trump administration. Reuters could not independently verify the report, and Oracle, Tencent and the White House had not responded to its requests for comment.
The reported value cannot simply be deducted from revenue or backlog without knowing the accounting treatment and cancellation terms. Can Oracle redeploy expensive computing capacity if a customer arrangement falls through?
New Capital Brings Dilution and Interest Costs
Oracle’s pricing announcement covers 86,206,897 shares at $116 each, roughly $10 billion gross, alongside $10 billion in senior notes. Expected net equity proceeds are approximately $9.9 billion. Both offerings are scheduled to close November 4, subject to conditions; pricing does not establish that settlement is complete.
The bonds carry annual coupons, their stated interest rates, from 7% to 8.65%, with maturities from 2029 to 2046. New shares dilute existing ownership, while bonds add interest obligations. Expansion must earn enough to justify both costs.
Cloud Growth Must Become Collected Revenue
The September 10 earnings release reported fiscal first-quarter revenue of $19.3 billion, up 30%, and cloud infrastructure revenue of $7.4 billion, up 121%. GAAP earnings per share were $1.56, compared with adjusted, non-GAAP EPS of $1.92. Remaining performance obligations, contracted revenue awaiting recognition, reached $664 billion.
Those numbers show capacity is generating sales, but backlog is not cash in the bank. Facilities must become operational and customers must pay as agreements require. I would become more constructive if collections improve without another increase in outside funding, particularly after the Tencent report.
Construction Spending Still Exceeds Operating Cash
Oracle’s cash-flow tables show approximately $23.1 billion in quarterly operating cash flow against $28.5 billion in capital expenditure, leaving negative free cash flow of $5.4 billion. Free cash flow measures operating cash remaining after those capital purchases.
Revenue growth has not closed the funding gap. Customer prepayments, vendor financing and customer-provided hardware form part of management’s funding strategy, according to its investor update. These arrangements reduce immediate cash needs, but investors still need to assess the obligations attached to them.
The Funding Limit Depends on Execution
At its October 28 investor presentation, Oracle targeted positive free cash flow in the second half of fiscal 2028 and at least $30 billion in fiscal 2029. It reaffirmed fiscal 2027 revenue of at least $90 billion and non-GAAP EPS of $8.10.
Management’s $20 billion additional capital-raising limit through fiscal 2030 excludes debt refinancing and sits on top of the $20 billion equity raise completed in fiscal Q1. The newly priced package matches that additional amount. The plan depends on stronger cash generation and moderating spending. Further dilution remains possible.
Settlement and December Earnings Are the Next Tests
Oracle’s investor FAQ lists December 14, 2026, for fiscal second-quarter earnings. Before then, financing completion and a company response to the Tencent report are the immediate developments to watch.
The earnings comparison also needs care: Oracle’s Q1 guidance notes that the prior-year second quarter included a one-time Ampere investment gain. Adjusted EPS growth excluding that gain should not be presented as unadjusted year-over-year growth. Revenue delivery and cash conversion offer a clearer test of progress.
Oracle Technical Analysis: $131.56 Rejection Would Keep Sellers in Control
Oracle’s latest completed close at $126.19 marks a bounce from rising trendline support on the daily chart. However, price remains below descending resistance and both moving averages, which smooth price movements to show the broader trend. The rebound has not yet repaired that weaker structure.
I lean slightly bearish while $131.56 caps the recovery, with a rejection there providing confirmation. A break above it would bring the 50-day exponential moving average at $137.96 into play. A daily close above $137.96 would invalidate the immediate bearish setup and favor a recovery toward $145.47 to $146.42.
RSI, a momentum gauge, stands at 44.29, below its neutral midpoint but not oversold. MACD, which compares moving averages to track momentum, remains below its signal line and zero. Both indicators leave buyers with more work to do. If rising trendline support fails, $114.58 is the next horizontal support. A daily close below $114.58 would open the way for $100.80. Until resistance breaks, the bounce remains vulnerable to renewed selling.
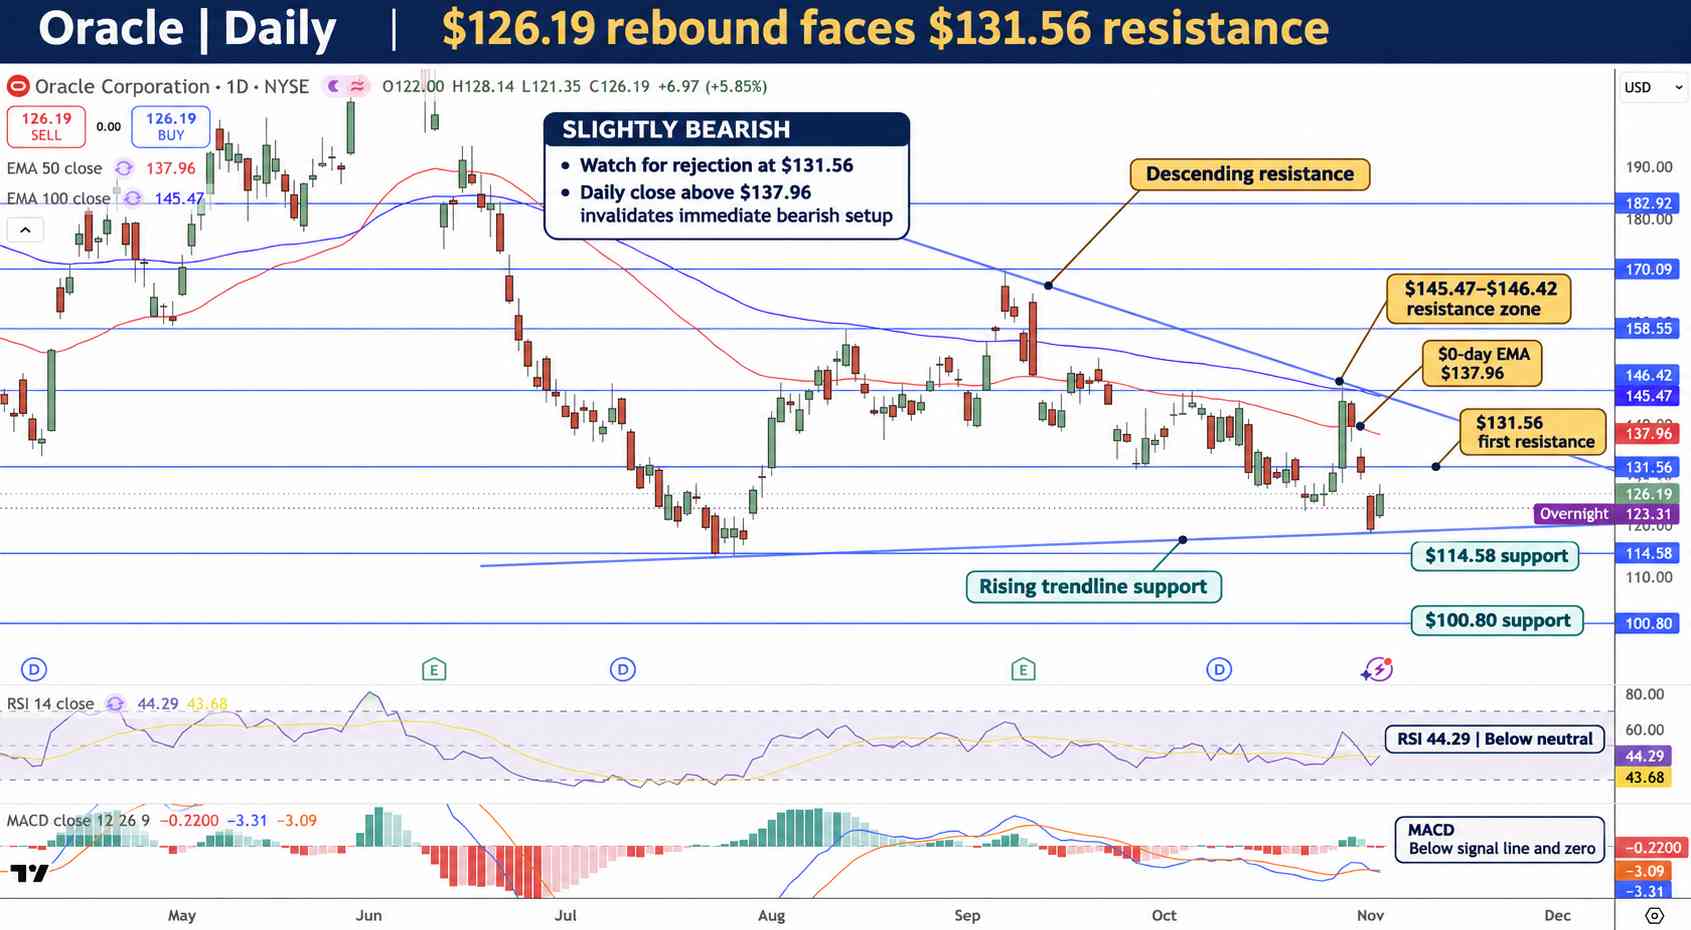
ORCL Price Chart - Source: Tradingview
Key Levels
- Latest completed close: $126.19 on November 3, 2026
- Immediate resistance: $131.56
- Upside tests: $137.96; then $145.47 to $146.42
- Support: rising trendline; next horizontal level $114.58
- Downside target: $100.80 after a daily close below $114.58
- RSI: 44.29, below neutral and not oversold
FAQ
Has Oracle confirmed the Tencent cancellation?
The cited Reuters report attributes the cancellation to the Financial Times and says Reuters could not independently verify it. A specific revenue or backlog impact remains unconfirmed.
What would improve Oracle’s technical outlook?
Clearing $131.56 would strengthen the rebound. A daily close above $137.96 would invalidate the immediate bearish setup and favor $145.47 to $146.42.
Bottom Line
I remain cautious while Oracle’s cash needs and contract uncertainty outweigh confidence in rapid cloud growth. A rejection at $131.56 would support the slight bearish bias. A daily close above $137.96 would change that near-term view.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.