


Boeing Earnings Preview: Cash Flow Expected to Turn Positive, Wall Street Sees Up to $305



AI Podcast


Boeing is scheduled to release its Q3 2026 financial results on Tuesday, October 27, 2026. Markets anticipate revenue of $23.95 billion to $24.95 billion, significantly narrowed losses of -$0.20 to -$0.26 per share, and free cash flow turning positive to $1.0 billion–$2.0 billion. Growth is driven by commercial delivery rebounds and reduced defense impairment charges. While Wall Street maintains bullish price targets up to $305, analysts warn that supply chain bottlenecks and heavy net debt pose downside risks. The stock eyes a breakout above $200 on positive cash flow confirmation, with key support around $172–$176.
TradingKey - Global aerospace giant Boeing (BA) is expected to release its third-quarter financial results for fiscal year 2026 before the U.S. market open on Tuesday, October 27, 2026. After several quarters of supply chain bottlenecks, regulatory scrutiny, and capacity constraints, market focus for this quarter's earnings report has shifted entirely from previous loss containment to the inflection point of turning free cash flow (FCF) positive.
Markets Focus on Free Cash Flow
Compared with the same period last year, market expectations for Boeing's Q3 earnings report have improved, with revenue expected to grow +3% to +7% year-over-year, losses narrowing significantly, and the biggest highlight being a notable improvement in operating cash flow. The specific financial forecasts and market consensus are as follows:
Key Metrics | Market Estimates (Q3 2026) | Prior-Year Period (Q3 2025) |
Revenue | $23.95 billion – $24.95 billion | $23.27 billion |
Earnings Per Share | -$0.20 to -$0.26 | -$7.47 |
Free Cash Flow | Turning slightly positive: $1.0 billion–$2.0 billion range | Negative outflow |
The market expects a recovery in Boeing's profitability structure, mainly due to optimism over a rebound in deliveries from its Commercial Airplanes (BCA) division and a reduction in large impairment charges at its Defense, Space & Security (BDS) division, which is expected to significantly narrow Q3 losses compared to last year. In addition, as deliveries hit their peak in the second half of the year and working capital is released, the market expects Q3 free cash flow to achieve a positive rebound.
Wall Street Most Bullish Target at $305
Based on Boeing's current stock price of around $188, Wall Street's average consensus price target ranges from $252 to $267, implying a potential upside of approximately +34% to +42%; the highest price target currently stands at $305, representing a potential gain of over +62%.
Investment Bank | Latest Rating | Latest Price Target | Core Rationale |
Barclays | Buy | $305 | Bullish on phased breakthroughs in 737-10 certification, with strong demand from global airlines replacing fleets driving full-speed production ramp-up. |
Bernstein | Buy | $298 | Believes the duopoly moat is extremely strong, with pushing monthly 737 series production to 47 units serving as the core catalyst for valuation recovery. |
Goldman Sachs | Buy | $253 | Fine-tuned the pace of supply chain recovery, but emphasized that a massive backlog provides exceptionally high revenue visibility. |
Morgan Stanley | Maintain | $225 | Remains cautious regarding supply chain bottlenecks such as CFM engine and seat delivery schedules, but the price target remains above the current price. |
Although price targets are generally above the current share price, institutions such as Morgan Stanley and TD Cowen still warn that delivery delays from engine suppliers, Spirit AeroSystems fuselage manufacturing, and interior seating could still slightly weigh on final delivery schedules for the 787 and 737. In addition, despite improvements in cash flow, the company's net debt load remains heavy, and interest expenses in a high-interest-rate environment are suppressing the efficiency of net profit conversion.
Boeing Stock Technical Analysis: Challenging the $200 Level
From an upside perspective, if Boeing's Q3 free cash flow turns positive as expected, and management confirms that 737 monthly production reaches 47 aircraft while the certification schedule for the 737-10/777X remains unchanged, the stock is expected to break through resistance at $198–$202 on strong volume, launching a rally to fill the ex-dividend gap and repair valuation toward $215+.
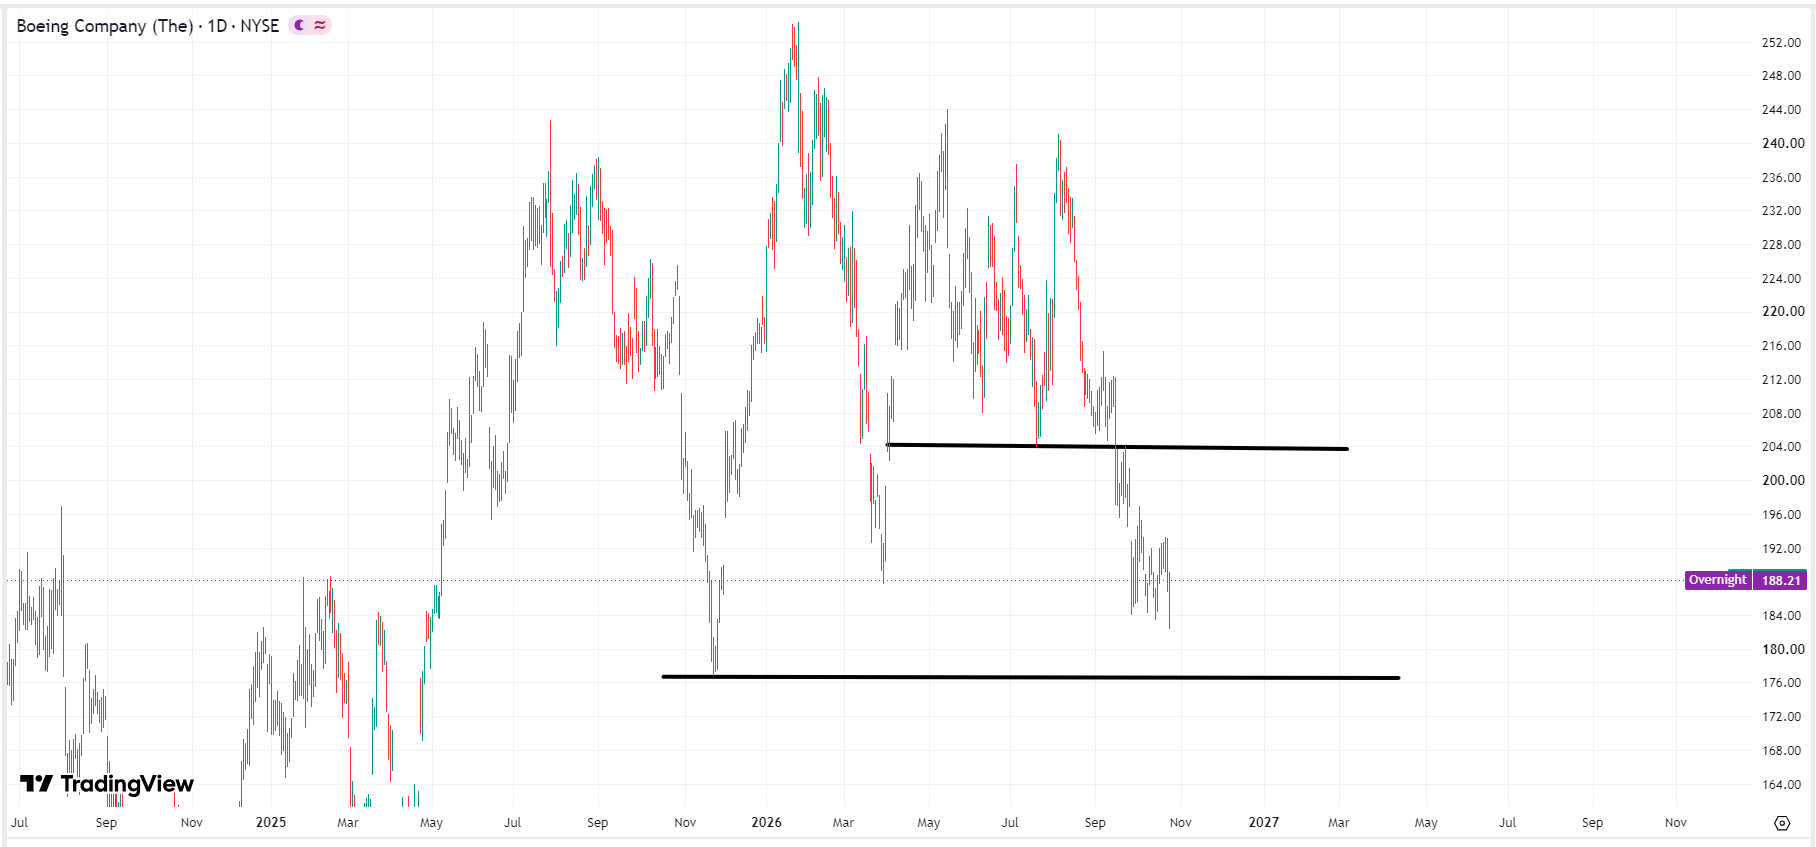 Boeing stock price chart, Source: TradingView
However, if supply chain lead times for CFM engines and Rolls-Royce seats once again drag down delivery guidance, the stock is more likely to seek support down at $172–$176, which was the pullback low from November last year. If this defense line fails to hold, a second bottoming process toward $160 cannot be ruled out.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.