


Chipotle Stock Forecast: Starbucks Takeover Talk Adds a New Catalyst Before Q3 Earnings



AI Podcast


Chipotle Mexican Grill’s recent stock rebound was driven by speculative reports of a Starbucks takeover rather than fundamental changes. Ahead of its Q3 earnings report, Chipotle’s underlying business shows positive customer traffic growth, expanding Chipotlane integration, and international scaling. However, profitability remains pressured by rising food and labor costs. Technistically, the stock is currently trading within a $30.44 to $34.03 range, with a daily close above $34.03 required to confirm a bullish recovery. Investors should prioritize upcoming margin improvements and transaction trends over unverified merger speculation.

TradingKey - Chipotle Mexican Grill (CMG) enters October 9 with an interesting takeover situation on top of an already significant earnings event. Chipotle will report Q3 results on Wednesday, October 28. Chipotle closed on Thursday, October 8, at $32.68, up 6.21% on volume of approximately 72.0 million shares after the news broke that Starbucks (NASDAQ:SBUX) had explored buying the burrito chain.
What’s interesting is that speculation of a potential takeover comes as Chipotle’s business is starting to look better on its own. Q2 showed positive traffic with comparable sales on the mend. Management was also bullish enough to increase their comparable sales outlook for the year. Chipotlanes are popping up everywhere with management focused on the margins.
Starbucks Reportedly Explored Buying Chipotle
The newest bit of news came on Oct. 8, when the Financial Times reported Starbucks had worked with advisers on a possible acquisition of Chipotle. Reuters later confirmed Starbucks would not comment on the FT report and that it would continue to focus on its own turnaround, and Chipotle declined to comment.
At the moment, there is no acquisition offer, transaction agreement, or formally announced process disclosed by either company. Therefore, I would consider speculative M&A activity the main rationale for the Oct. 8 moves, and not any material change in Chipotle’s underlying earnings.
There is some strategic interest with Starbucks, given Niccol is still fairly recent alumnae from Chipotle, and during his time there, enhanced the digital-order and fulfillment infrastructure as well as restaurant design. From an international growth perspective, a Starbucks/Chipotle deal could be strategic, given Starbucks has an established international presence, and Chipotle does not, but given Starbucks’s own ongoing restaurant remodel and turnaround efforts, deal execution would be complex.
Q2 Traffic Finally Turned Positive
Chipotle's Q2 results showed an operating backdrop that was more favorable before the takeover speculation. Revenue increased 9.3% over the previous year to reach $3.35 billion. Comparable restaurant sales increased by 2.2%. This comp consisted of a 1.0% increase in transactions and a 1.2% increase in average check.
For me the most important metric was transactions, or traffic, because restaurants can raise their comparable sales by simply raising their prices. Given positive transaction growth, it means that more customers were visiting Chipotle. This is a positive sign of underlying demand.
In the quarter, digital sales represented 38.3% of food and beverage sales, an increase from 35.5% in the same period last year. After the quarter, management raised their full year 2026 comparable restaurant sales guidance to low-single-digit growth, from the previous guidance of roughly flat.
Margins Remain the Main Fundamental Problem
A concern is stronger sales have not resulted in stronger profitability. Restaurant-level operating margin fell to 25.2% from 27.4% in the same period last year, and consolidated operating margin fell to 15.7% from 18.2%. Adjusted diluted EPS stayed flat at $0.33 for the period despite the 9.3% revenue growth.
Food and beverage and packaging costs rose to 29.7% of revenue from 28.9%, primarily because of inflation in beef, freight and a greater use of protein and produce. Lower dairy and avocado costs and price increases on the menu offset some of this increase.
Labor costs rose to 25.0% from 24.7% primarily because of wage and bonus inflation, and greater staffing to improve hospitality and restaurant execution. For October 28, the most important question is whether traffic will continue to be positive as these cost pressures start to improve.
Chipotlanes Remain Central to U.S. Expansion
Chipotle opened its 1,500th Chipotlane on Sept. 29 in Bradenton, FL. The company opened 500 Chipotlanes in the last 2 years and plans to continue this format for its North American growth.
According to Chipotle, restaurants with a Chipotlane outperform and generate higher volumes than traditional stores. In Q2, Chipotle opened 100 company-owned restaurants, 80 of which included a Chipotlane.
Company management expects opening 350-370 new stores in 2026, including 10-15 International stores operated by partners. Approximately 80% of new Company-operated stores are expected to include a Chipotlane.
With Chipotlanes, Chipotle improves pickup convenience without a traditional drive-thru. Maintaining the sameunit growth and improving ROIC is possible if new Chipotlane stores continue to outperform.
International Expansion Is Becoming More Meaningful
In July, Chipotle’s first Mexican location opened in Nuevo Leon as part of the company’s partnership with Alsea. According to the partnership, both companies will open more locations in the region, and Chipotle aims to open its first restaurants in Mexico City in 2027.
On September 2, Chipotle opened its first location in Asia in Seoul, through its joint venture with Sangmidang Holdings. Similar to its company-owned restaurants in North America, Chipotle plans to use South Korea as a reference market to evaluate and expand to other markets in Asia, and plans to open its first restaurants in Singapore in 2027.
Chipotle is currently using a partner-led model for international expansion, where the partner owns and operates the restaurants. This model takes the burden of capital and execution off of Chipotle for entering new markets. I see this as the more sensible strategy for international expansion. Chipotle can evaluate if its brand is accepted in new markets, before committing the same level of capital it uses to open its North American restaurants.
Management Is Building a Deeper Leadership Pipeline
Management is building a deeper bench for leadership, as the restaurant is expanding rapidly. As of September 15th, Chipotle stated it wanted an Apprentice manager in every restaurant by the end of 2027, which is in comparison to around three-quarters of restaurants today.
According to Chipotle, the Apprentice Manager Program helps build leadership and management skills for promoting from within to general managers.
This is less speculative than takeover rumors, but equally as important to consider. As Chipotle continues to expand and open hundreds of restaurants, management has to ensure staffing, throughput, and quality of service keep up with the pace.
Buybacks Provide Support After the Stock’s Decline
As for the second quarter, Chipotle reported it repurchased $630.7 million of stock at an average price of $32.55. As of June 30th, it had about $1.7 billion available under board authorized repurchase programs.
As mentioned above, the $32.55 average repurchase price is noteworthy, as Chipotle closed on October 8th at $32.68. Again, it doesn't necessarily mean the stock is undervalued, but it means management was comfortable buying shares at those levels.
Management buying back shares improves per share economics, and in combination with improving same store sales and operating profit, the case for the buybacks becomes stronger.
October 28 Earnings Matter More Than the Takeover Rumor
Chipotle will release Q3 2026 results on October 28. Management has confirmed an announcement at approximately 4:10 p.m. ET, followed by a conference call at 4:30 p.m. ET.
I will wait for the company’s announcement to give more details for the quarter, but I will focus on transaction growth, comparable sales, restaurant-level margin, beef and labor costs, and new-store productivity. I will also listen for an update from management on its 2026 comp outlook.
The takeover speculation may continue to impact near-term movement in the stock price, but a deal remains speculation and I would not build a fundamental case around it. I view the more sustainable case for the long-term story to be Chipotle’s ability to move from more than 4,200 restaurants globally toward its 7,000-restaurant goal in the U.S. and Canada and continue to improve traffic and margins.
At this time, I view Chipotle at roughly 30 times trailing and 26 times forward earnings to be fully valued, and another quarter of traffic improvement and margin expansion may not drive a meaningful rerating.
Chipotle Technical Analysis: CMG Rebounds 6.21% From $30.44 as Bulls Eye $33.77
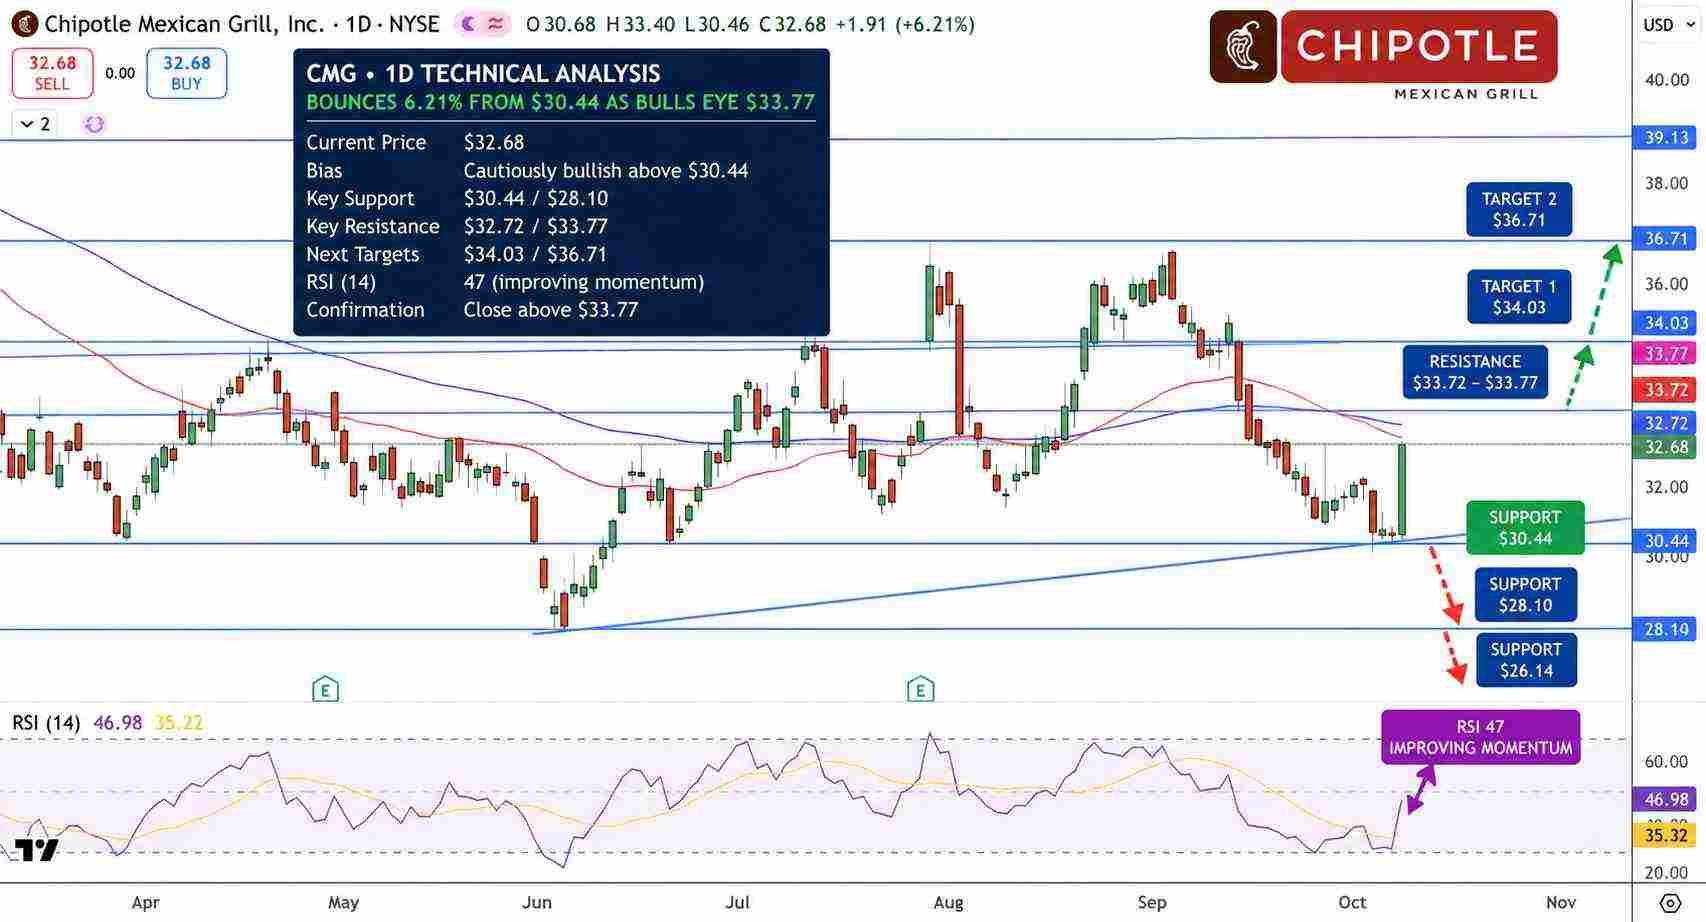
Chipotle rallied 6.21% and closed on October 8 at $32.68 after falling to the $30.44 support level. It is worth noting the emerging bullish candle off the rising trendline, indicating bulls are defending a key structural level. However, CMG is still below the two moving averages, and the overall trend remains bearish.
Chipotle Stock Price Chart - Source: Tradingview
RSI is at 47, above its signal line at 35. This shows some ebbing of the selling pressure, however for a more convincing argument for reversal, RSI needs to cross above 50.
The first major area of resistance lies at $32.72, and is then followed by a moving average cluster at $33.72 to $33.77. A close above $34.03 would bring the next major resistance at $36.71 into play.
Support remains at the key $30.44 level, where an uptrend line is in place. A break below $30.44 would bring $28.10 and $26.14 into play.
My base case scenario is a rebound in CMG as long as it holds above $30.44, with the major recovery resistance zone found at $33.72 to $34.03.
Key Levels
• Latest completed close: $32.68
• Major support levels: $30.44, $28.10 then $26.14
• Major resistance levels: $32.72, $33.72 to $34.03 then $36.71
• RSI: approx. 47, recovering
• Recovery trigger: a daily close above $34.03
• Breakdown Trigger: a daily close below $30.44.
Why is Chipotle stock in focus now?
A Starbucks takeover rumor has sent speculation flying with Chipotle stock up 6.21% on elevated volume in the few weeks prior to its Q3 report. Meanwhile, Q2 customer traffic was positive, management increased comparable sales, and the company opened more Chipotlanes and entered additional international markets.
What level confirms a stronger CMG recovery?
A daily closing price above $34.03 would strongly confirm the recovery and bring the next price target at $36.71 into play. A move below $30.44 would negate the current uptrend and bring the next downside price target at $28.10 into play.
Bottom Line
Chipotle is reporting earnings on October 28th with positive customer traffic, a large unit growth runway, and a recently lifted takeover rumor. While the Starbucks speculation is interesting given Niccol’s history with Chipotle, I would not base-case value the stock with takeover speculation.
More important is whether positive customer transactions can lead to improvements in margins. CMG is currently trading between $30.44 and $34.03 and, from a technical perspective, a strong close above $34.03 would support the bullish case. From a fundamental perspective, positive customer transactions with easing costs for food and labor would better support the bull case rather than takeover speculation.
Recommended Articles





Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.