


Netflix Stock Forecast: Disney Licensing Deal and $3 Billion Ad Push Put Q3 Earnings in Focus



AI Podcast


Netflix faces a critical test ahead of its October 20 Q3 earnings report, as slowing subscriber growth and soft guidance pressure its stock. Despite a 2026 share price decline, underlying fundamentals remain robust, supported by double-digit revenue growth, operating margins above 30%, and rising user engagement. Strategic initiatives, including expanding advertising nearing $3 billion, live programming, content licensing, and generative AI production efficiencies, are driving new revenue streams. However, intensifying competition from the newly formed Skydance requires balance sheet preservation. Technically, the stock remains in a bearish trend, with $66.98 serving as critical support and $74.42 acting as the key recovery trigger.
TradingKey - Netflix (NFLX) shares have really taken a beating in 2026, but the overall business has not. Industry analysts see double-digit growth and operating margins well above 30%. Shares closed trading on October 7th at $69.70, up 1.47% for the day, but well off their 52-week high of $124.86. The next big move in the shares is expected on October 20th after the market close with the release of Q3 results.
While the shares have not reflected it, I believe some good things are happening at the company. Revenues continue to be double-digit and continue to improve. Customer engagement is also on the improve. The advertising business continues to bring in revenue, and the company is improving its live programming. All of this is good, but because the subscriber base is maturing, investors want to see that management can continue to increase revenues through new lines of business at a faster pace to justify a higher multiple, and rightfully so.
Disney Opens More of Its Library to Netflix
On October 2, Disney agreed to license additional content to Netflix. The deal includes titles like the Ice Age movies, Percy Jackson and the Olympians, and Will Trent. The terms of the deal were not made public.
Strategically this deal is of interest because it indicates that, beyond its originals, Netflix can integrate content from major competitors. While Disney is competing with Netflix through its own service, Disney+, and Hulu, it is still willing to license selected titles from its vaults to Netflix.
I see this as further evidence of one of Netflix's core strengths. It does not need to own every studio to be able to put together an appealing catalog. Selectively licensing content can help deepen Netflix's catalog without forcing the company to undertake the capital intensity and integration risk of a major acquisition.
Paramount-Warner Creates a Stronger Rival
This week became much more competitive after Paramount finalized its purchase of Warner Bros Discovery on October 6 for approximately $110 billion. The combined company, now named Skydance, has Paramount and Warner Bros. film studios, the streaming services Paramount+ and HBO Max, and CBS and CNN.
Having an enormous library of content and a huge base of streaming subscribers across multiple platforms makes the new company extremely competitive. With big debt and integration costs, the new company is targeting about $6 billion in cost savings.
These costs are crucial to consider for Netflix, as it will now have a much larger and more powerful competitor. With heavy competition, it may be more important for Netflix to maintain its balance sheet, rather than focus on organic growth. Though I see the $2.8 billion termination payment as a financial benefit rather than an operating benefit, because of the competitive situation, I think it was an excellent management decision to preserve Netflix’s balance sheet.
Q2 Revenue Grew 13% but Investors Wanted More
In the second quarter, Netflix's revenues grew 13.4% to $12.56 billion, operating income grew 11.1% to $4.19 billion, and net income increased by 9% to $3.40 billion. Net margin was 27.1% compared to 28.2% last year.
From an operational standpoint, Netflix posted strong numbers. The market's response, however, showed how high expectations have become. Operating expenses continued to rise, partially offset by strong revenue growth. As a result, operating margin was slightly below the prior year level.
For 2026, Netflix expects revenues in the range of $51.0 to $51.4 billion and expects operating margin of 31.5%. The business is very profitable, but Wall Street is looking for growth outside of existing lines of business to offset declining growth rates and support new avenues for revenues.
Q3 Guidance Was the Main Disappointment
Netflix guided to revenue of approximately $12.86 billion and diluted EPS of $0.82 for Q3. The guidance fell below Wall Street expectations and shares dropped 8.6% in after-hours trading, then more than 10% in early trading the next day.
This makes the October 20 report date even more pivotal. For Netflix, it will be imperative to show that Q3 guidance was conservative. While focusing on revenue, I'll also be evaluating Q4 guidance and, if conservative, determining how aggressively it was justified.
Advertising Is Approaching a $3 Billion Business
In Q4, there are the strong seasonal holidays and a robust lineup of live events. I'll be paying attention to how bullish the outlook is heading into 2027.
Netlfix projects it will make $3 billion from advertising in 2026. Ad revenue would represent roughly double 2025 advertising revenue of more than $1.5 billion.
Netflix does not report advertising revenue in a manner separable from subscription revenue. S&P Global estimates advertising revenue for Q2 of 2026 at $618 million, up almost 80% from the year prior, but less than expected. I will discuss the $618 million estimate as an outside third-party estimate rather than a company reported number.
The $618 million estimate, if true, would represent less than 10% of the total revenue for the quarter, the bulk of which would have been subscription revenue. Advertising does not need to fully offset subscription revenue in order to positively impact the financials of the company. Improving revenue per user, even if it is of a low-margin nature, can offset some costs and provide additional operating leverage. Additionally, high-incremental-margin advertising revenues can positively impact the EPS over time by allowing the company to increase operating leverage.
Engagement Is Still Growing
During the first half of 2026, Netflix reports global viewing hours grew by 2%. This represents approximately 1.5 billion extra hours of content streamed, compared to the first half of 2025. While global growth was somewhat expected, it did accelerate from 1.5% to 2% growth for the first half of 2026, despite global competition from the Winter Olympics and the FIFA World Cup.
While 2% growth in viewership hours might not seem like a large number, it is very relevant in the world of retention and pricing. It is likely viewers will always find more content to watch, so if the hours watched continues to increase while Netflix pursues its advertising and live content strategy, they may be able to effectively monetize each user without relying solely on subscriber growth.
As a current user, I find this an accurate lens through which to view Netflix's mature phase of growth.
Live Programming Is Expanding the Ad Opportunity
Netflix is continuing its investment in live events. One of their anchors is WWE Monday Night Raw. Other events include the Six King’s Slam tennis tournament, the first Thanksgiving Eve NFL game, and two NFL games on Christmas Day. As part of their first NFL partnership, they streamed the first regular season game played in Australia, in addition to other games.
Live events, by their very nature, create a captive audience. Advertisers are willing to pay a premium to reach this audience, especially for events with broad appeal. The real challenge, and opportunity, becomes reaching people at the most opportune moment with the right message.
This strategy also moves Netflix away from being a pure scripted entertainment company. The company does not have to become a traditional sports network to benefit from live programming. A targeted slate of live programming can improve engagement and create appointment viewing and strengthen the ad-tier.
AI Is Starting to Influence Production Economics
Netflix has begun to use Generative AI more in the production process in 2026, primarily in Visual Effects and Post Production in about 300 titles. The company positions AI more as a tool to improve the quality of its output and to improve the efficiency of the production process more broadly.
There is certainly potential for AI to make a positive impact on the bottom line. The financial opportunity is more on the production side as AI has the potential to improve Visual Effects and Animation. Perhaps more importantly, Generative AI can potentially improve the economics of localization and enhance production output. Even marginal improvements in hundreds of titles at the scale of Netflix can improve overall production output of the company.
The real risk is more on the technology cost side, can AI improve output quality at a faster pace than it improves the costs? For investors, perhaps the biggest question is, will AI improve the output quantity and quality to a greater extent than it impacts the cost and pace at which technology improves?
October 20 Is the Next Major Test
Netflix will release Q3 2026 financial results on October 20 at approximately 1:01 p.m. Pacific Time. This will be followed by a management interview at 1:45 p.m. Pacific Time with co-CEOs Greg Peters and Ted Sarandos, CFO Spence Neumann and VP of Finance, IR and Corporate Development Spencer Wang.
For the report, I would primarily look at revenues compared to the $12.86 billion guidance, operating margin, advertising trends, user engagement and Q4 revenues. The market will also be focused on whether live and licensed content are gaining enough traction to be monetized to offset slower growth in core subscriptions.
At $69.70, the stock is trading roughly 22 times trailing earnings and 20 times forward earnings. While the valuation has improved from earlier in the year, the stock is still ultimately looking for signs to show that the growth rates can stabilize and perhaps improve.
Netflix Technical Analysis: NFLX Rebounds From $66.98 as Descending Trendline Caps Recovery
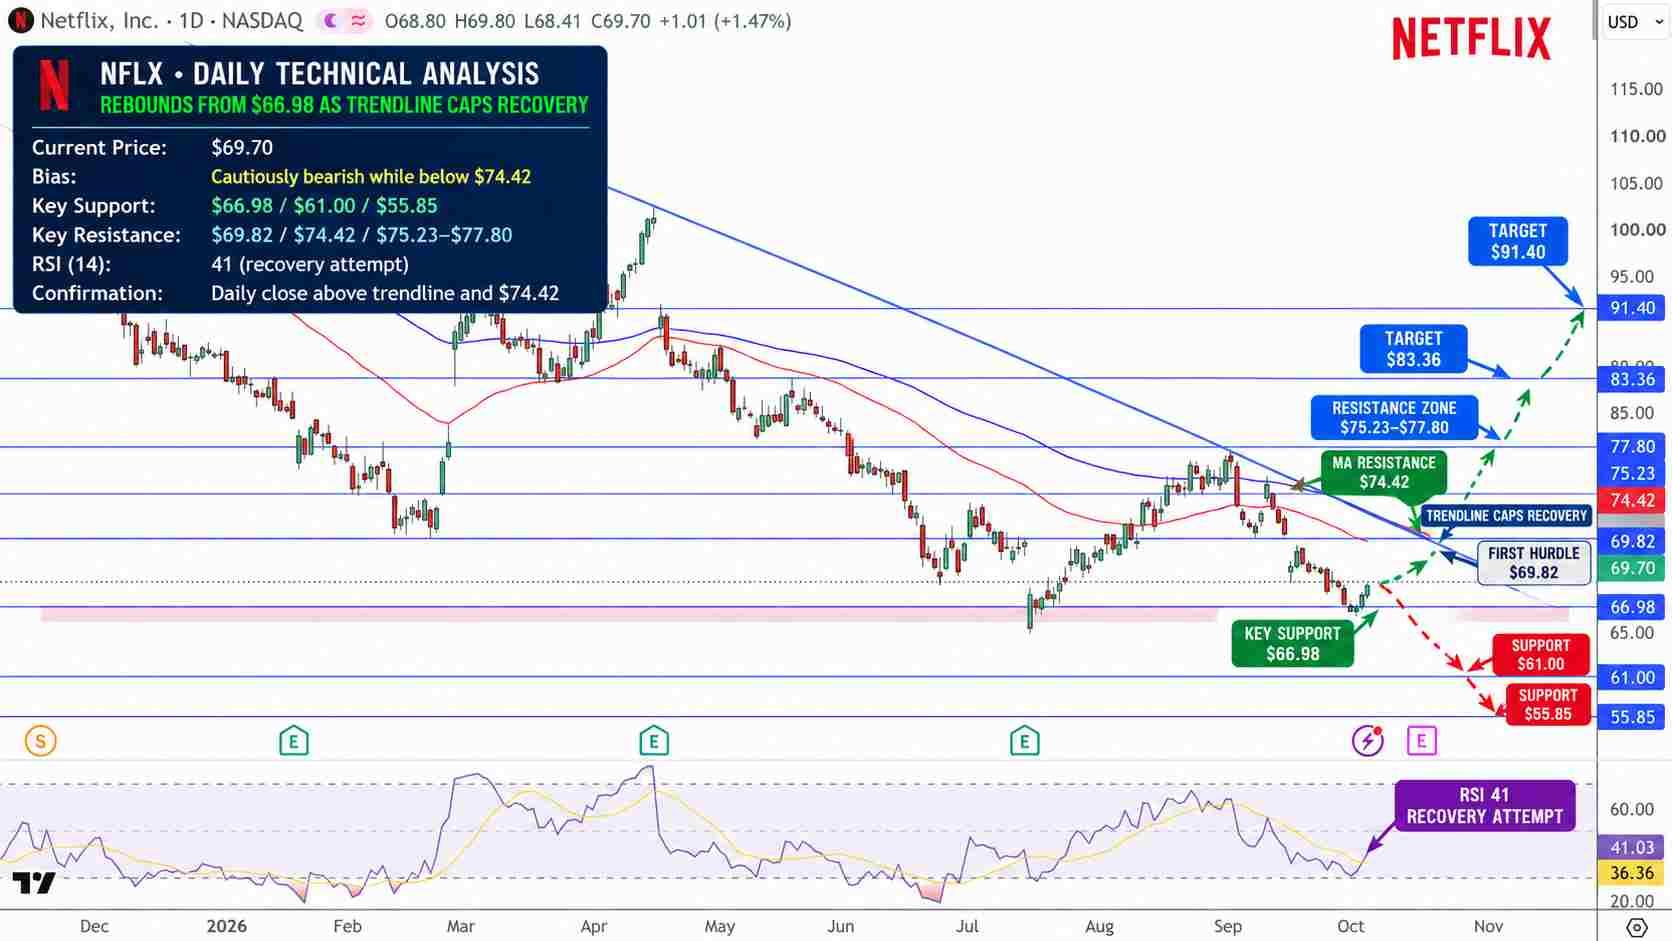
Netflix closed October 7 at $69.70 after bulls defended the important $66.98 demand area. From a price action standpoint, it's interesting to see the modest bullish move from the demand area considering the larger trend remains bearish. Netflix continues to trade below the two moving averages and a bearish trendline that has guided the decline since April.
Netflix Price Chart - Source: Tradingview
The Relative Strength Index (RSI) is at 41, above the signal line that rests at 36. This is an improvement from yesterday when it was near oversold territory, indicating a reduction in the downward momentum of the stock.
The near-term resistance is at the descending trendline that comes in around $71 to $72. A daily close above the trendline would open the door to the $74.42 50-day moving average, followed by $75.23 to $77.80.
On the downside, $66.98 continues to be critical support. A daily close below this level would be bearish and open the door to the $61.00 area, followed by $55.85.
The larger trend remains bearish while the stock trades below the $74.42 area. A defense of $66.98 could set the stage for a bounce to the $69.82 to $74.42 area. A break below $66.98 could signal a deeper decline.
Key Levels
• Latest Completed Close $69.70
• Major Support Levels $66.98, $61.00, $55.85
• Major Resistance Levels $69.82, $71 to $72, $74.42 to $77.80
• RSI about 41, recovering but under neutral
• Recovery Trigger: Sustained Daily Close above $74.42
• Breakdown Trigger: Sustained Daily Close below $66.98
Why is Netflix stock in focus now?
Netflix is in the spotlight as its Q3 earnings are on October 20. Also, its advertising business is nearing a $3 billion annual business, and there is content licensing from Disney and the new Paramount/Warner streamer combination. Investors will look for signs if these provide a catalyst for further growth after a softer 2026 for the stock.
What level confirms a stronger NFLX recovery?
A close above $74.42 would improve the short-term trend and raise the chances for a move to the $75.23 to $77.80 range. A close below $66.98 would reinforce the trend and bring $61.00 into view.
Bottom Line
Netflix is in a better position than the 2026 share-price decline indicates. Earnings growth continues to be in the double-digits, revenue continues to grow, operating margins remain above 30 percent, and viewer hours continue to increase. Additionally, the company continues to make progress in the advertising and live programming areas.
Nevertheless, the main concern for Netflix remains how the market prices the company moving forward. Netflix continues to be cautious below $74.42, and the October 20 report will need to show that the company is above and beyond conservative with its Q3 estimates and that there will not be a more sustained period of a slower growth outlook. An improved outlook for advertising and a better Q4 estimate and outlook will be the most beneficial to the investment case.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.