


Nebius Earnings Preview: Revenue Expected to Grow Over 500%, Wall Street Highest Price Target at $410



AI Podcast


Nebius Group will report Q3 2026 financial results on November 12, with Wall Street expecting $907 million in revenue. Despite strong demand and major contracts with Microsoft and Meta, the company faces elevated customer concentration, delivery timeline scrutiny, and substantial financing needs to support projected annual capital expenditures of $20 billion to $25 billion. While Q3 earnings are critical, management’s full-year guidance, capacity delivery schedules, and financing strategies will determine whether the stock’s recent decline has excessively priced in underlying execution and capital risks.

TradingKey - AI cloud computing company Nebius Group (NBIS) will report its third-quarter 2026 financial results before the U.S. market opens on November 12 and host a conference call at 8:00 a.m. Eastern Time.
Ahead of its earnings report, Nebius shares experienced sharp volatility. On November 5, NBIS dropped to an intraday low of $113.30, retreating about 62% from its year-to-date high of $299.86 and marking its lowest level since April; the stock subsequently rebounded over consecutive sessions, last trading at $141.45, up about 9.3% on the day, but still roughly 53% below its year-to-date high.
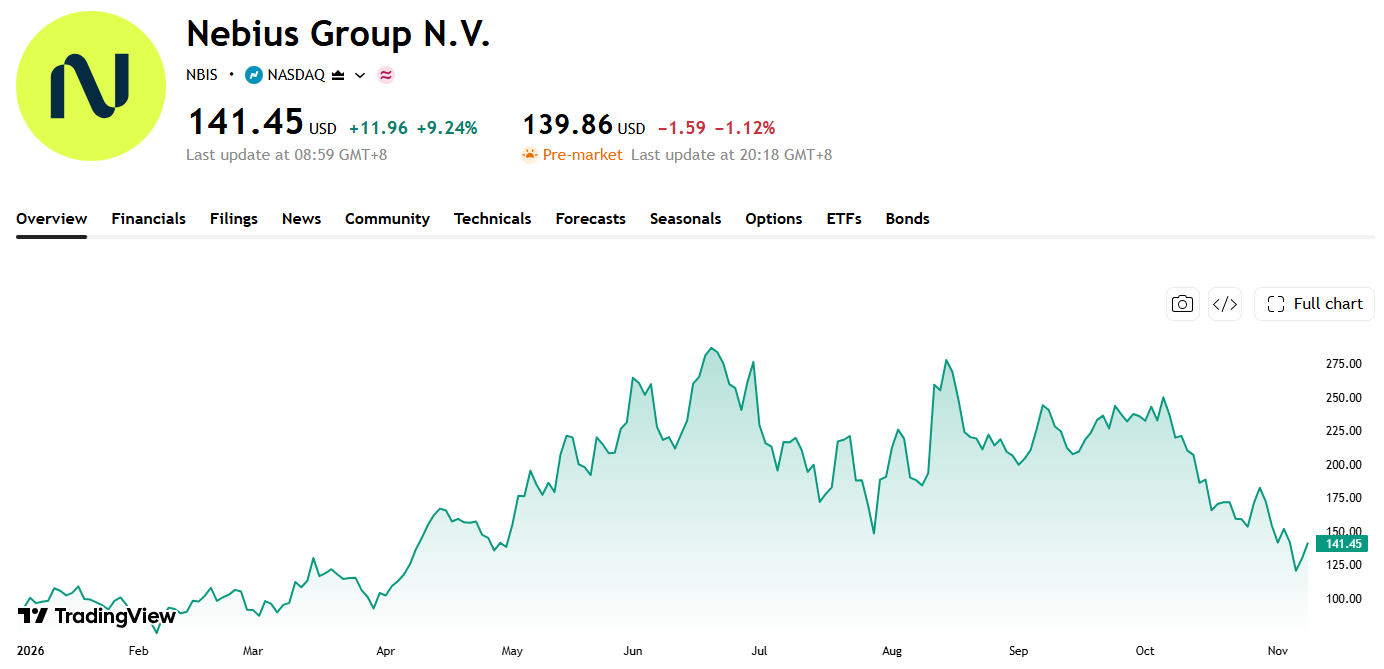
Source: TradingView
The market is concerned about whether Nebius can deliver data center capacity on schedule, whether customer concentration is excessively high, and how much additional debt or equity financing will ultimately be required for tens of billions of dollars in annual capital expenditures. The third-quarter results will serve as an important checkpoint to test these issues.
Third-Quarter Revenue May Top $900 Million, but Meeting Full-Year Guidance Is More Critical
Wall Street currently expects Nebius to report third-quarter revenue of approximately $907 million, up over 520% year-over-year, and an adjusted loss per share of about $0.72.
In the previous quarter, Nebius posted revenue of $582.3 million, up 454% year-over-year and approximately 46% sequentially, topping market expectations. Deducting cost of revenue, the company's gross margin was roughly 77%, and group adjusted EBITDA reached $236.2 million, representing a margin of about 41%; the adjusted EBITDA margin for its core Nebius AI cloud business approached 50%. However, because data center expansion, depreciation, interest, and other expenses remained elevated, the company recorded a net loss from continuing operations of about $190.4 million for the quarter.
Therefore, this quarter cannot be judged solely by whether earnings per share beat expectations. As Nebius is in a capital-intensive expansion phase, a significant gap between adjusted earnings and GAAP net income is likely to persist. Investors must determine whether revenue growth is being driven by higher utilization of deployed capacity or fueled by a fresh round of high-cost investments.
The company previously maintained its targets of $3 billion to $3.4 billion in full-year 2026 revenue, an annualized run-rate revenue of $7 billion to $9 billion by year-end, and a group adjusted EBITDA margin of approximately 40%. If third-quarter revenue reaches around $907 million, cumulative revenue for the first three quarters will approach $1.89 billion, meaning that fourth-quarter revenue must reach at least approximately $1.11 billion to hit the lower end of its full-year guidance.
This makes the fourth-quarter outlook more critical than historical third-quarter results. If management reaffirms its year-end annualized revenue target of $7 billion to $9 billion and provides a clear timeline for bringing capacity online, the market may regain confidence that the stock's current decline has excessively priced in risk.
Microsoft and Meta Orders Drive Growth, Amplify Customer Concentration and Delivery Risks
Nebius' revenue growth is primarily driven by bringing new capacity online and increased GPU usage by large customers. Management previously stated that AI compute demand continues to exceed available supply, with newly added capacity typically committed to customers before officially going online.
The company has also benefited from strong GPU pricing. Nebius previously disclosed that auction prices for some next-generation Blackwell compute capacity were approximately 15% higher than previous peak prices and about 20% higher than quotes for existing projects. Unit revenue from short-term compute contracts is also significantly higher than that of earlier projects, indicating that tight supplies of high-performance GPUs continue to provide the company with certain pricing power.
Nebius' contract with Microsoft (MSFT) is valued at approximately $17.4 billion, which could increase to about $19.4 billion if Microsoft purchases additional services. The contract requires the company to deliver GPU infrastructure across multiple phases; if Nebius fails to meet agreed timelines after a grace period and cannot provide alternative capacity, Microsoft has the right to terminate the corresponding service batches.
Recent reports indicate that Microsoft is stepping up scrutiny of projects from emerging cloud computing providers such as Nebius, IREN (IREN), and Nscale, while taking a more cautious stance toward certain new projects with high costs and significant delivery risks. Microsoft has not announced any cancellations of its core contract with Nebius, but investors will watch whether management confirms that project timelines remain unchanged and whether Microsoft is still willing to expand the partnership.
Meta (META), meanwhile, signed a five-year, $12 billion dedicated compute agreement with Nebius, with capacity delivery expected to begin in early 2027. Meta also agreed to purchase residual compute capacity in specific clusters that Nebius is unable to sell to third-party customers, for an additional amount of up to $15 billion, bringing the potential scale of cooperation between the two sides to approximately $27 billion.
These long-term agreements enhance future revenue visibility, but they also result in high customer concentration. Nebius disclosed that three customers contributed approximately 24%, 21%, and 14% of revenue, respectively, in the second quarter. If any one of them delays delivery, adjusts capacity requirements, or stops placing additional orders, short-term growth expectations could be significantly affected.
Over the long term, Microsoft and Meta are also building their own data centers. Large tech companies are currently using emerging cloud providers like Nebius partly because their own compute capacity buildout cannot keep up with AI demand. If self-built capacity increases in the future, Nebius will need to attract more AI model companies, enterprise, and government clients to avoid long-term reliance on a handful of hyperscalers.
$20 Billion to $25 Billion Capex Tests Financing Capacity
Nebius's growth model requires continuous purchases of Nvidia GPUs, data center expansions, and securing power in advance, making its capital requirements far higher than those of traditional software companies. In the second quarter, the company's capital expenditures reached approximately $5.7 billion, primarily used for GPUs, related hardware, and data center expansion. Management expects full-year 2026 capital expenditures to reach $20 billion to $25 billion.
The company hopes to support its expansion through a combination of customer prepayments, operating cash flow, asset-backed financing, convertible bonds, and equity financing. Some contracts signed in the second quarter include prepayments that can cover 50% to 60% of related capital expenditures, helping reduce the extent to which Nebius relies entirely on its own balance sheet.
However, financing remains the primary concern for shareholders. Nebius raised capital through at-the-market offerings in the second quarter, leading to an increase in shares outstanding; in August, the company completed an offering of convertible senior notes with an aggregate principal amount of approximately $5.75 billion. In October, Nebius further secured $3.5 billion in senior secured financing from Citi to support its global capacity buildout.
While these financings strengthen the company's short-term expansion capabilities, they also bring interest expenses and potential equity dilution. As long as data centers come online on schedule and utilization rates remain high, the newly deployed capital is expected to translate into revenue; however, if projects face delays, Nebius will bear debt service, depreciation, and operating expenses upfront while revenue recognition is postponed, which could cause cash flow pressures to escalate rapidly.
Wall Street remains relatively optimistic about Nebius's long-term prospects. According to TipRanks, 13 Wall Street analysts have covered Nebius over the past three months, with an average price target of approximately $296.73 for NBIS, a high of $410, and a low of $144. Compared to the latest price of $141.45, the average price target represents upside potential of approximately 110%.
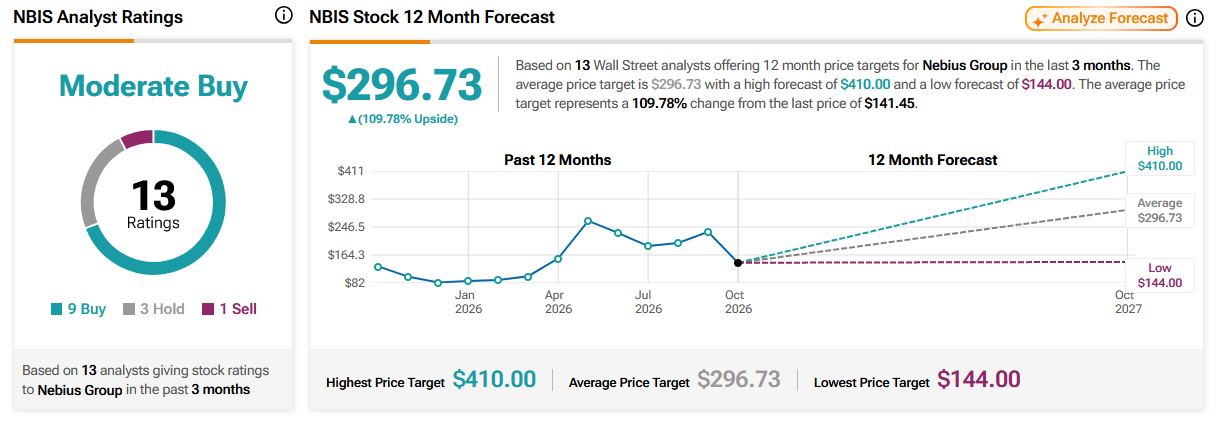
Source: TipRanks
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.