


DUOL: DAU Re-Accelerates; When Will Monetization Catch Up?


$Duolingo(DUOL.US) Q3 results were broadly in line. Signs of an operating inflection beneath the headline numbers deserve attention.
In detail. Key takeaways follow.
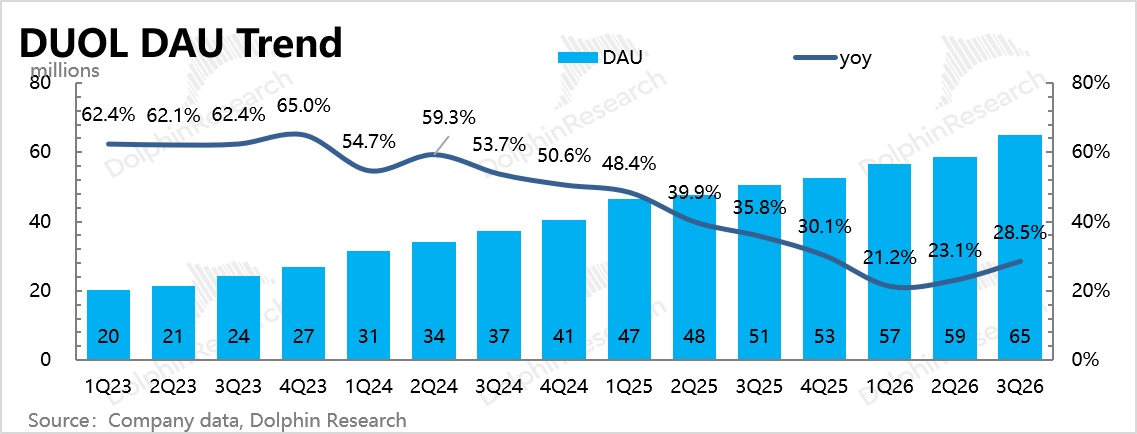
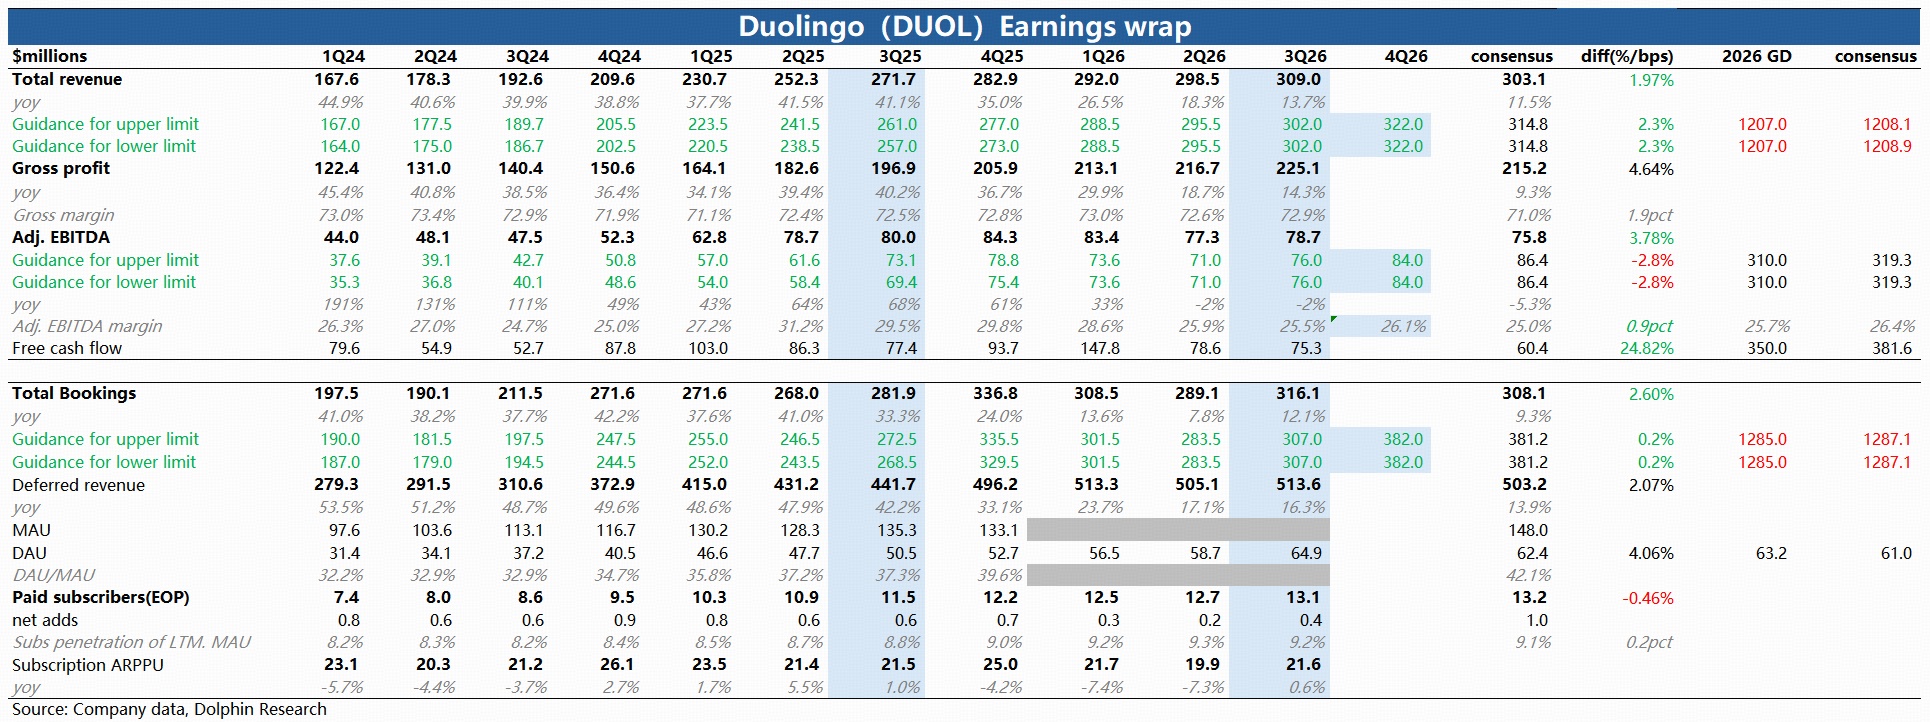
1) User growth kept rebounding: User growth continued to recover. Q3 DAU reached 64.9 mn, with daily actives up 29% YoY vs. 23% in Q2.
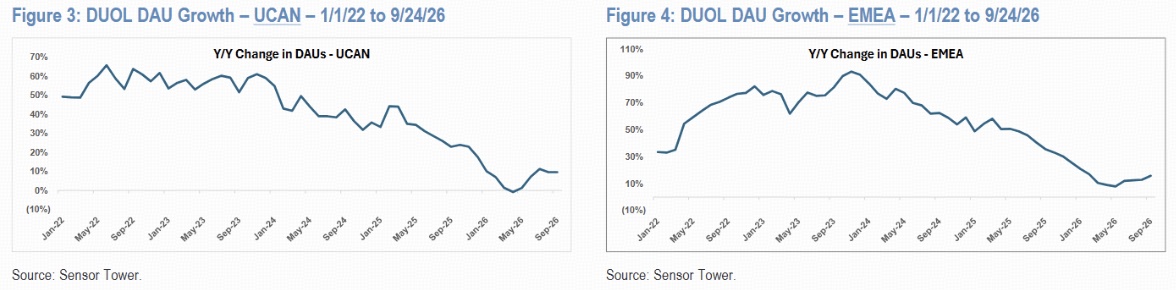
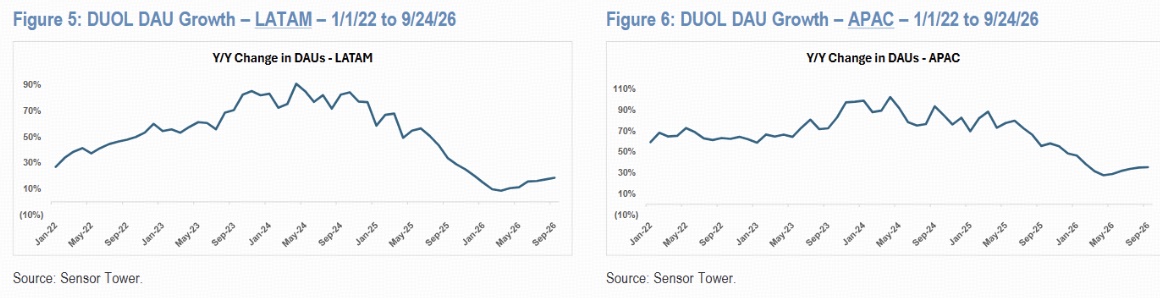
The 2026 priority is to re-accelerate user growth, and execution so far looks solid. APAC has strengthened after localization, and N. America returned to growth from Q2 following adjustments to the Green Machine tests.
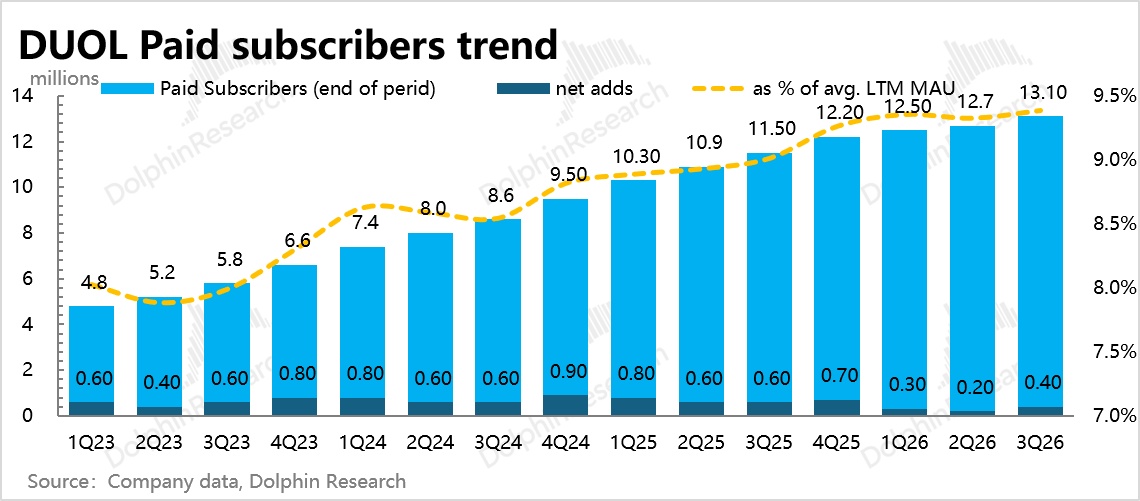
Subscription penetration held at 9.4%, with net adds of 0.4 mn QoQ. The rebound continued.
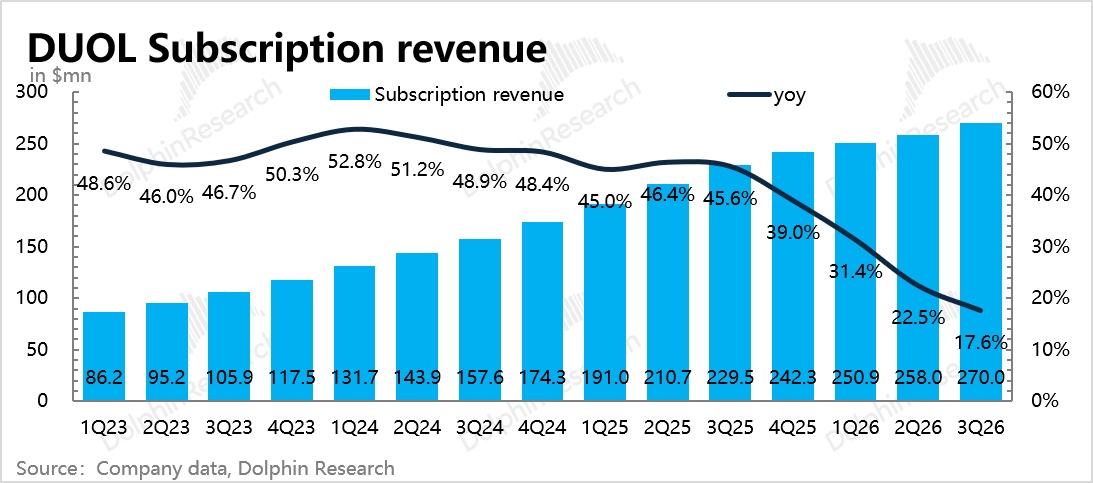
2) Monetization lagged but is turning with users: Q3 revenue was $309 mn (+14% YoY), with core subscription revenue up 17.6% YoY. Q4 guidance is broadly in line, calling for $322 mn with flat sequential growth.
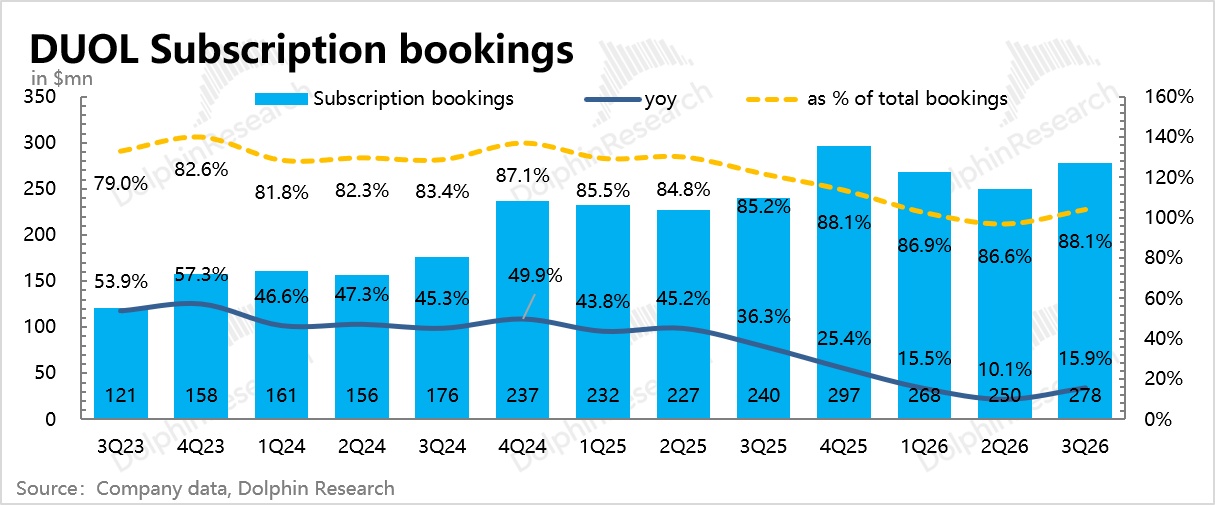
Monetization is trailing the user recovery by a step. Subscription revenue growth is still decelerating, total bookings growth is hovering just above 10%, and the full-year guide saw only a small upward tweak without a beat.
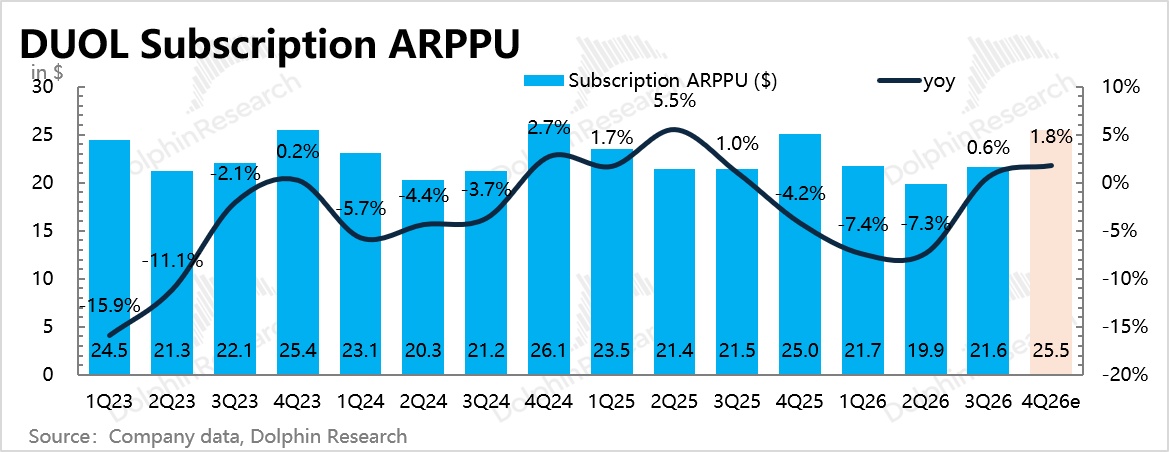
That said, subscription bookings showed signs of a turn in Q3. Both net subscriber adds and per-user ARPPU improved QoQ, a small but clear volume-and-price uptick, and in subscription streaming models an ARPPU inflection QoQ is an encouraging signal.
MAX will be discontinued this month, with individual MAX users migrated to the Super family plan at the same price. This could drag ARPPU in Q4, but based on the bookings guide, ARPPU is still likely to rise QoQ.
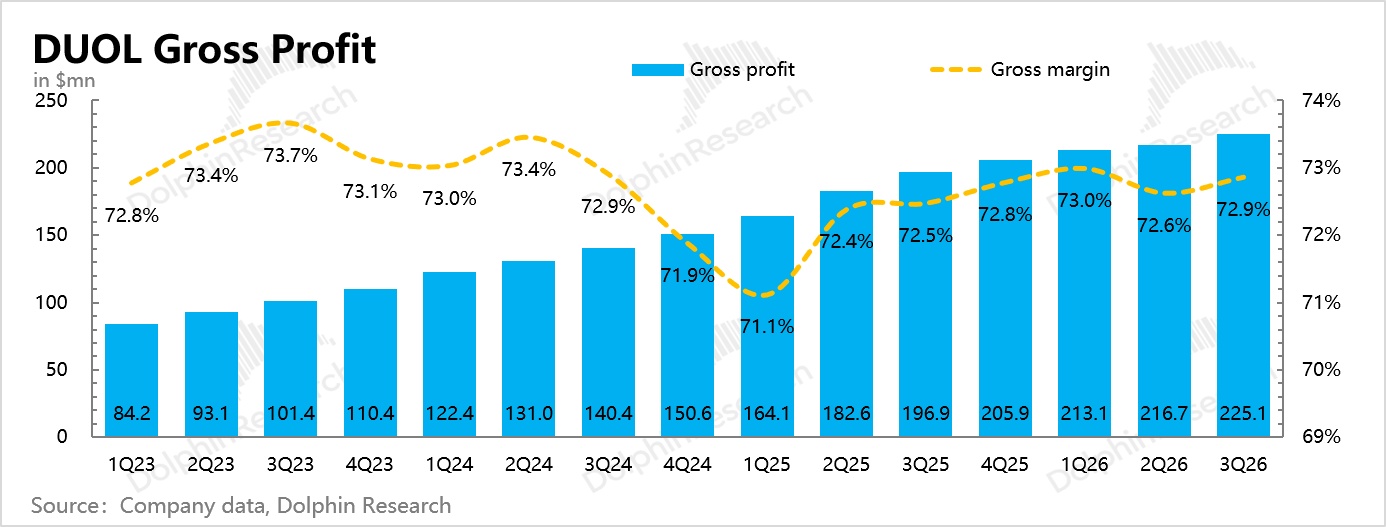
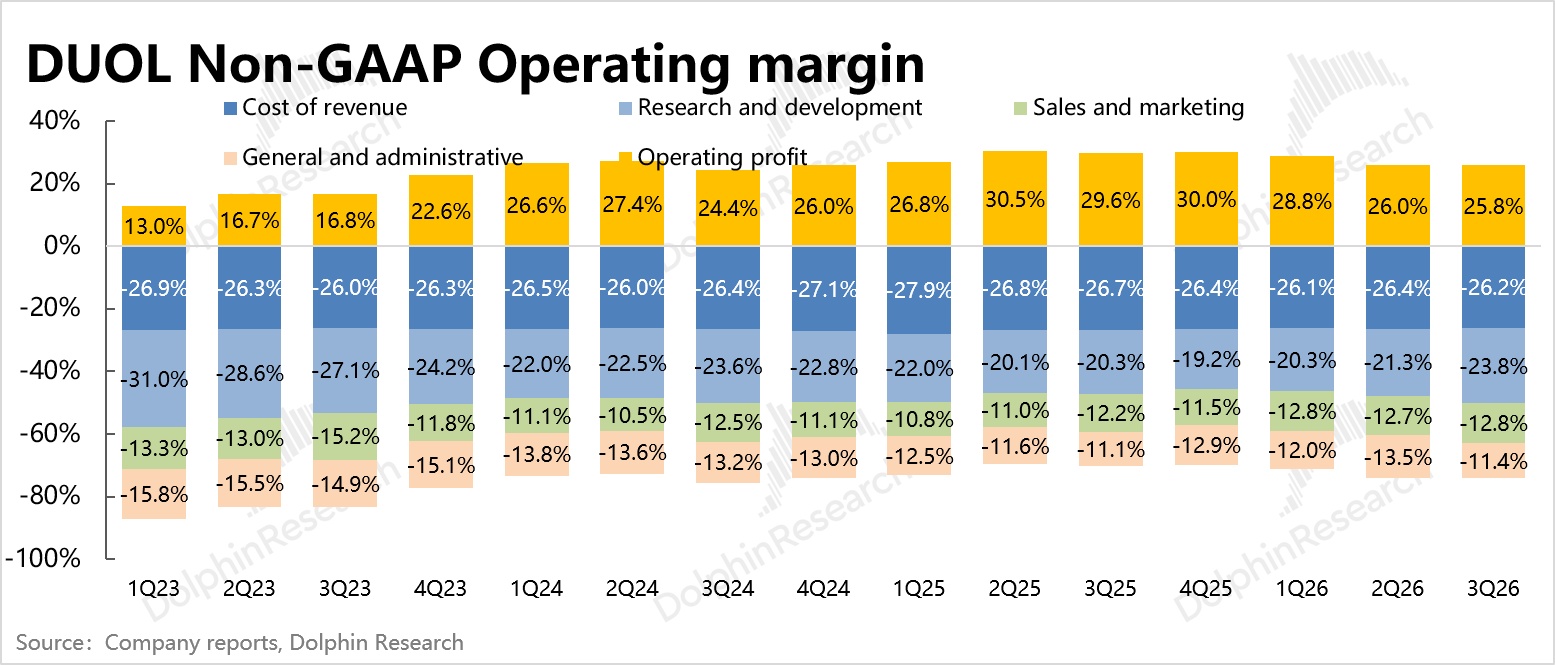
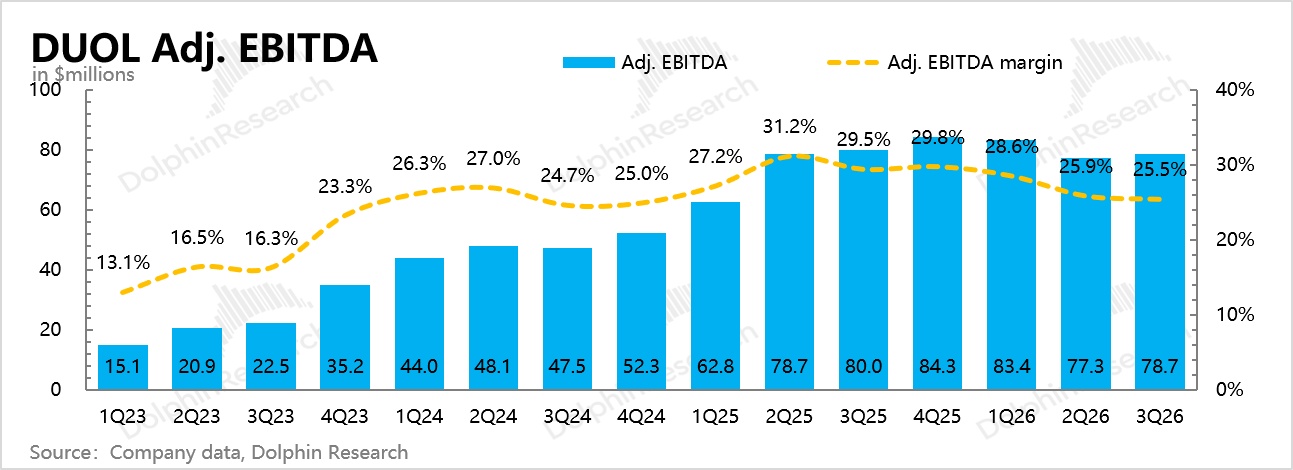
3) Profit under pressure during the transition: With a user-first focus this year, necessary marketing spend and product updates will weigh on the P&L, and Adj. EBITDA margin (ex-SBC) edged down QoQ. However, Q4 guidance implies a margin rebound, which may reflect seasonality but also suggests improving operating trends.
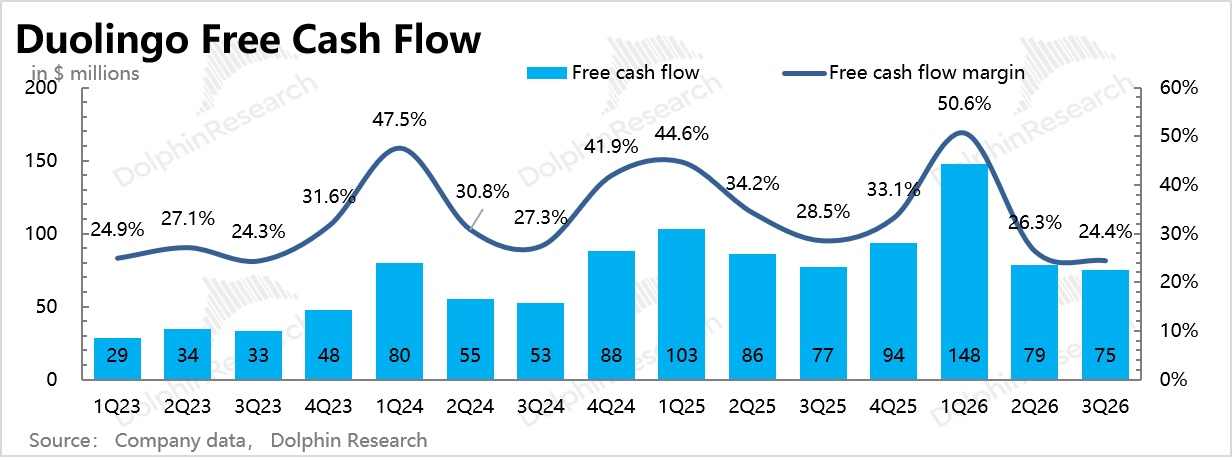
On cash, capex stepped up in Q3 and FCF dipped slightly QoQ. Cash plus short-term investments stood at $1.37 bn at quarter-end, and cumulative buybacks of $82 mn have offset the prior two years of share dilution.
4. DUOL Trans
5. Results vs. Est.
Dolphin Research View
The clearest Q3 signal is that DUOL has likely bottomed near term on operating metrics. The steady recovery in user KPIs validates management execution and should help anchor sentiment on pullbacks.
On a longer view, the user-growth-first strategy remains sound. The free experience has not been bluntly curtailed, and longer trials, speaking practice and gaming partnerships are supporting both retention and cash receipts, a healthier path than relying solely on price hikes.
Still, this year's user gains were achieved with heavy resourcing, and some of the uplift likely came from time-bound campaigns. This implies sustained investment is required, and user growth should not be extrapolated linearly.
Whether user momentum can durably translate into monetization still bears watching. In the broader AI substitution trend, the company must keep investing to match product iteration, but cannot raise monetization in lockstep.
Thus, although Q4 guidance points to a margin rebound, seasonality is likely the dominant driver. The prior thesis that stronger brand and social virality would allow sustained optimization of S&M and R&D to structurally lift margins no longer applies.
The company is at a ~$6.0 bn mkt cap, up 11% after hours to ~$6.7 bn. If it delivers $324 mn of Adj. EBITDA this year and bookings growth of 15–20% next year with flat margins, that implies $370–390 mn of Adj. EBITDA, and at 15x Adj. P/EBITDA, a value of $5.6–6.0 bn, below the post-AH level.
This suggests investors are paying an inflection premium. Given the need for more confirmation on operating signals and a limited margin of safety, we prefer to wait and watch near term, while tracking short-term user metrics closely.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.