


Arm Holdings PLC Stock (ARM) Moved Down by 3.18% on Oct 29: Drivers Behind the Movement



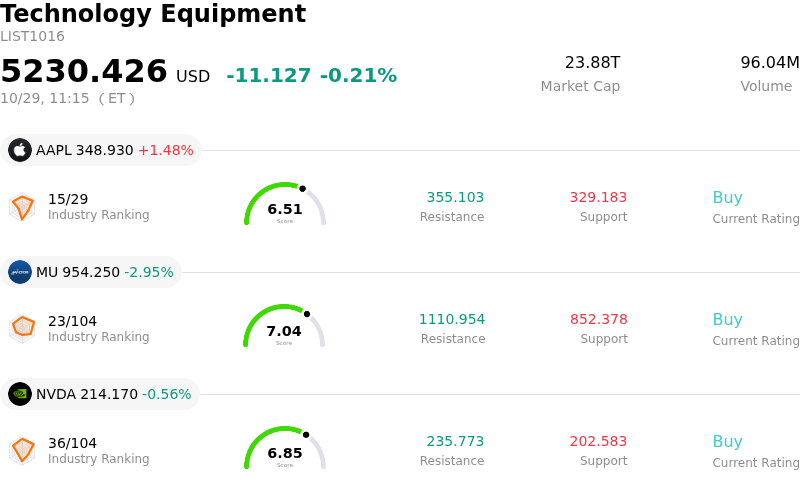
Arm Holdings PLC (ARM) moved down by 3.18%. The Technology Equipment sector is down by 0.21%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Apple Inc (AAPL) up 1.48%; Micron Technology Inc (MU) down 2.84%; NVIDIA Corp (NVDA) down 0.53%.
What is driving Arm Holdings PLC (ARM)’s stock price down today?
Arm Holdings experienced downward price pressure alongside broader weakness across the technology and semiconductor sectors. Sentiment across chip equities deteriorated following disappointing quarterly reports from global tech and semiconductor industry heavyweights. Disappointment in major tech earnings and cautious outlooks from international hardware suppliers dampened investor enthusiasm across the supply chain. As major tech earnings approached, market participants reduced exposure to high-growth tech names, driving losses across sector benchmarks and creating a risk-off environment for chip architecture designers.
Company-specific positioning and valuation metrics amplified the intraday volatility. Carrying an elevated earnings multiple relative to legacy semiconductor peers, Arm remains particularly sensitive to valuation compression during periods of market volatility. With the company scheduled to report its fiscal second-quarter financial results in early November, market participants appear to be de-risking positions and hedging exposure. Recent institutional 13F filings showing stake reductions by select asset managers, alongside scheduled insider trading activity, contributed to profit-taking behavior among traders.
Despite the session's pullback, Arm's core fundamental narrative remains tied to structural tailwinds in artificial intelligence infrastructure, enterprise data centers, and the expansion of high-margin licensing royalties. Demand for advanced CPU architectures and initial traction in direct processor initiatives offer long-term revenue visibility. However, in the near term, elevated valuation multiples and macro sensitivity to chip sector earnings reports are likely to keep price action volatile leading into the company's upcoming quarterly update.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of -2.233, indicating a sell signal. The RSI at 41.713 suggests neutral condition and the Williams %R at 62.650 suggests sell condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
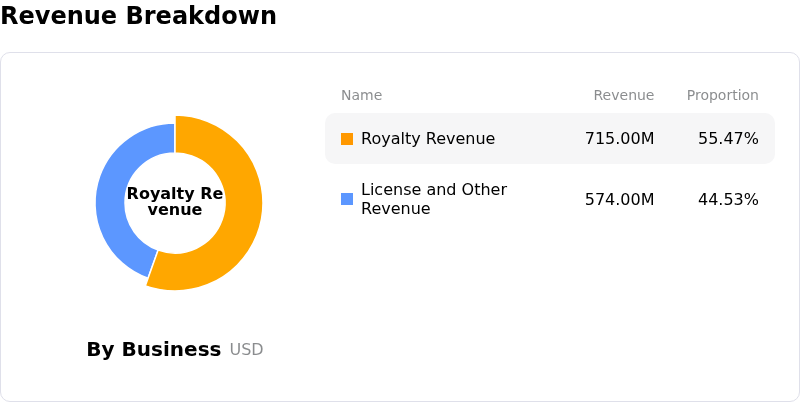
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $286.95, a high of $480.00, and a low of $125.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Qualcomm Litigation Adverse Rulings and Royalty Impairment: Following a Delaware jury ruling that Arm breached its architectural license agreement with Qualcomm, court proceedings are evaluating a potential five-year royalty suspension; because Qualcomm contributes roughly 9% of total revenue and nearly half of operating income, an adverse final ruling threatens multi-billion-dollar cash flow disruption.
- Extreme Valuation Multiples and Sensitivity to Sentiment Pullbacks: Trading at approximately 94x forward earnings and over 50x sales, Arm remains priced for perfection relative to semiconductor peers, making the stock hyper-sensitive to intraday volatility and steep drawdowns whenever broader AI hardware momentum flags.
- Margin Compression from Custom Silicon Pivot and R&D Inflation: Expanding from pure IP licensing into designing proprietary AGI CPU physical silicon has driven R&D spending up significantly, while first-generation physical hardware carries substantially lower gross margins in the high 30% range compared to Arm's core high-margin royalty engine.
- Ecosystem Friction and Direct Competition with Core Licensees: Transitioning vertically into finished data center CPU blueprints places Arm in head-to-head competition with its largest architectural licensees, increasing customer friction and raising the risk that partners diversify toward open-source architectures.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.