


NVIDIA Corp Stock (NVDA) Moved Down by 3.30% on Oct 14: Key Drivers Unveiled



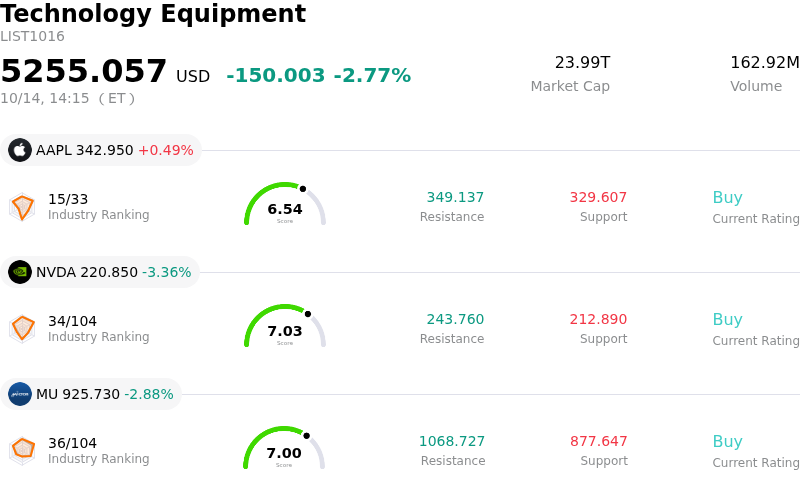
NVIDIA Corp (NVDA) moved down by 3.30%. The Technology Equipment sector is down by 2.77%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Apple Inc (AAPL) up 0.42%; NVIDIA Corp (NVDA) down 3.30%; Micron Technology Inc (MU) down 2.79%.
What is driving NVIDIA Corp (NVDA)’s stock price down today?
The recent pull-back in NVIDIA shares reflects broader macroeconomic headwinds stemming from hotter-than-expected inflation data, which pushed Treasury yields higher and triggered a broad sell-off across high-growth technology equities. As a high-multiple market leader heavily tied to massive long-term capital spending, NVIDIA remains particularly sensitive to shifting interest rate expectations. Rising bond yields compress price-to-earnings multiples across the technology sector and elevate financing costs across the broader enterprise AI stack, prompting institutional investors to trim exposure during risk-off trading sessions.
The intraday volatility was further magnified by sector-wide pressure across semiconductor equities, as market participants reassess technology valuations and the capital intensity required for global artificial intelligence infrastructure buildouts. Heightened scrutiny over debt-funded capital expenditures among key industry participants and shifting dynamics in memory supply chains added to profit-taking following the stock's recent strong performance near historical highs. Despite the short-term pullback, broader industry metrics highlighted at global semiconductor summits point to robust multi-year demand growth for logic and high-bandwidth memory architectures.
From an operational perspective, NVIDIA continues to reinforce its core market position through continuous technology execution and capital returns. The company recently expanded its hardware and software roadmap with enhanced computing libraries for semiconductor manufacturing, open infrastructure designs for next-generation architecture, and dedicated investments in regional research initiatives. Supported by a substantial multi-billion-dollar expanded share repurchase program and resilient data center demand, NVIDIA's medium-to-long-term growth thesis remains supported by structural tailwinds despite macro-driven volatility.
Technical Analysis of NVIDIA Corp (NVDA)
Technically, NVIDIA Corp (NVDA) shows a MACD (12,26,9) value of -2.641, indicating a neutral signal. The RSI at 43.193 suggests neutral condition and the Williams %R at 99.609 suggests oversold condition. Please monitor closely.
Media Coverage of NVIDIA Corp (NVDA)
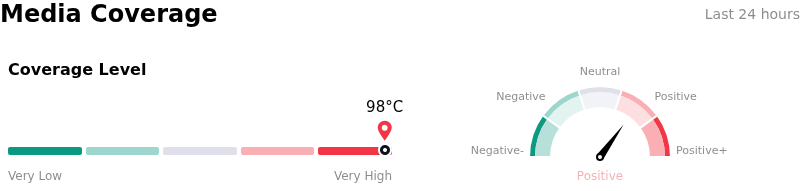
In terms of media coverage, NVIDIA Corp (NVDA) shows a coverage score of 98, indicating a very high level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of NVIDIA Corp (NVDA)
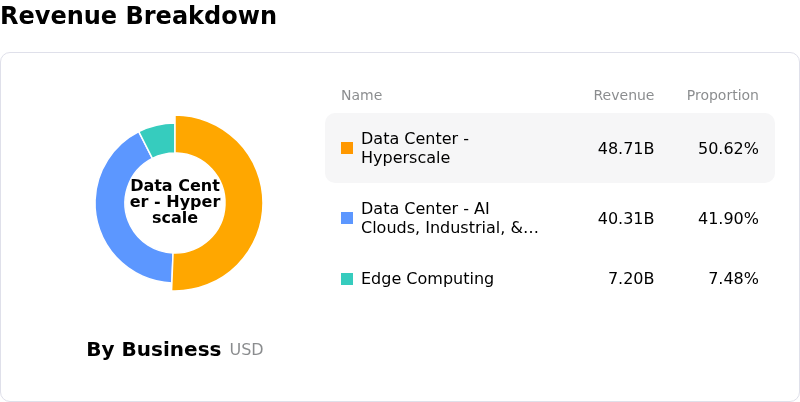
NVIDIA Corp (NVDA) is in the Technology Equipment industry. Its latest annual revenue is $215.94B, ranking 1 in the industry. The net profit is $120.07B, ranking 1 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $324.55, a high of $515.00, and a low of $180.00.
More details about NVIDIA Corp (NVDA)
Company Specific Risks:
- China AI Market Share Erosion: An IDC report revealed NVIDIA's market share in China's data-center AI chip market fell sharply to 34% in H1 2026, with shipments down 44% year-over-year due to stringent U.S. export curbs. Domestic Chinese rivals, led by Huawei, are filling the gap, confirming management's outlook of zero China data-center compute revenue going forward.
- Hyperscaler Substitution and In-House Custom Silicon: Major enterprise customers and cloud service providers are accelerating the deployment of internal AI processors—such as Microsoft's Maia 300—to handle dedicated inference workloads. This expanding alternative silicon ecosystem poses a structural threat to NVIDIA's long-term GPU pricing power and market share.
- Margin Compression from High Memory Costs: Industry analysts warn that persistent price inflation in high-bandwidth memory (HBM) is squeezing gross margins, which are projected to trough near 71% to 72% in upcoming quarters. Furthermore, NVIDIA holds massive long-term supply commitments totaling $279 billion, creating inventory overhang exposure if hyperscaler capex growth decelerates.
- Export Control Compliance and Smuggling Scrutiny: Recent U.S. Department of Justice indictments and Senate inquiries into the illicit diversion of restricted Blackwell and Hopper GPUs to foreign entities through shell companies are forcing tighter channel oversight. Increased regulatory friction and auditing requirements risk extending delivery lead times and elevating operational compliance costs for legitimate buyers.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.