


Taiwan Semiconductor Manufacturing Co Ltd Stock (TSM) Moved Up by 3.16% on Oct 2: A Full Analysis



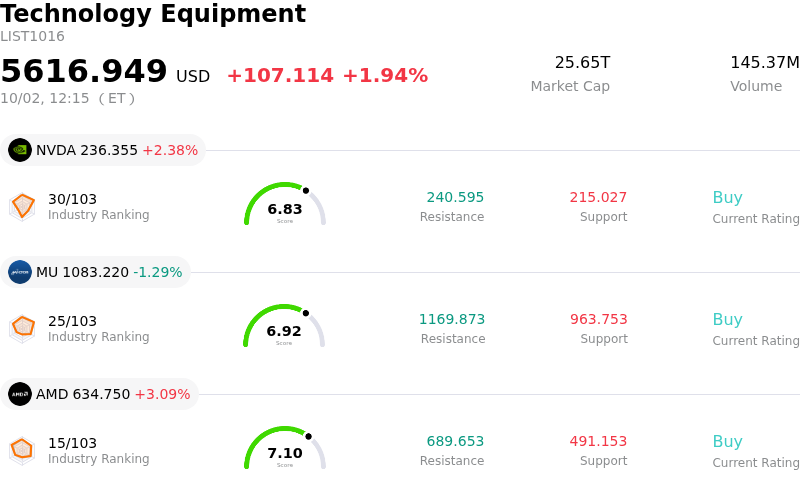
Taiwan Semiconductor Manufacturing Co Ltd (TSM) moved up by 3.16%. The Technology Equipment sector is up by 1.94%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 2.44%; Micron Technology Inc (MU) down 1.47%; Advanced Micro Devices Inc (AMD) up 3.09%.
What is driving Taiwan Semiconductor Manufacturing Co Ltd (TSM)’s stock price up today?
Taiwan Semiconductor Manufacturing Company experienced upward price momentum accompanied by heightened intraday volatility, driven primarily by reports highlighting the company's strategic expansion of its manufacturing footprint in North America to meet relentless demand for artificial intelligence hardware. Reports indicate that TSMC is evaluating a new multi-billion-dollar fabrication campus in Texas in addition to its substantial commitments in Arizona. This prospective expansion underscores the persistent supply tight spots across advanced manufacturing nodes as leading global technology firms continuously increase orders for high-performance computing silicon, reinforcing long-term top-line growth expectations.
Investor sentiment was further supported by recent structural catalysts, including upward revisions to output targets for cutting-edge semiconductor nodes. Favorable sell-side coverage and bullish analyst sentiment have reiterated confidence in TSMC's dominant market position and technological leadership within the foundry ecosystem. While elevated capital expenditure plans and potential gross margin pressures associated with next-generation node ramp-ups triggered some intraday price fluctuations, market participants ultimately focused on the company's unmatched pricing power and execution record.
Looking ahead, trading activity reflects proactive institutional positioning ahead of upcoming monthly revenue figures and third-quarter earnings releases. Broad tailwinds across the broader semiconductor sector, backed by sustained capital spending from major cloud hyperscalers, continue to provide a solid foundation for the stock. So long as advanced packaging and leading-edge wafer manufacturing remain the primary bottlenecks in the global AI buildout, TSMC's indispensable positioning in the supply chain remains a key catalyst for equity performance.
Technical Analysis of Taiwan Semiconductor Manufacturing Co Ltd (TSM)
Technically, Taiwan Semiconductor Manufacturing Co Ltd (TSM) shows a MACD (12,26,9) value of 5.769, indicating a buy signal. The RSI at 71.935 suggests buy condition and the Williams %R at 1.068 suggests overbought condition. Please monitor closely.
Fundamental Analysis of Taiwan Semiconductor Manufacturing Co Ltd (TSM)
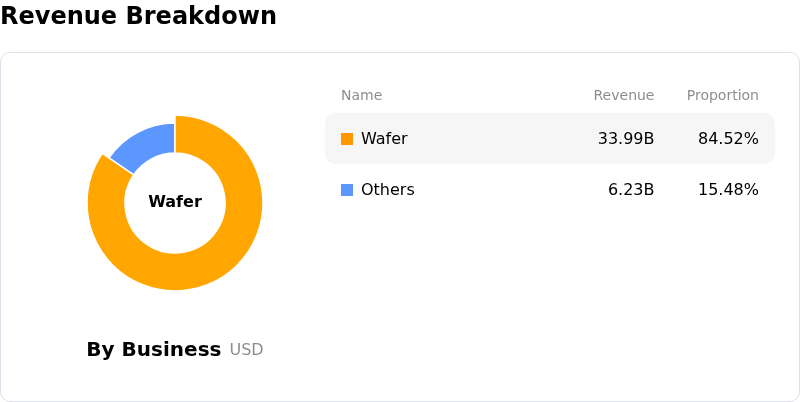
Taiwan Semiconductor Manufacturing Co Ltd (TSM) is in the Technology Equipment industry. Its latest annual revenue is $122.22B, ranking 3 in the industry. The net profit is $55.12B, ranking 3 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $547.45, a high of $700.00, and a low of $440.00.
More details about Taiwan Semiconductor Manufacturing Co Ltd (TSM)
Company Specific Risks:
- 2nm Process Ramp and Margin Compression: Accelerated scaling of the 2-nanometer (N2) manufacturing node is introducing short-term gross margin pressure due to steep initial yield learning curves and elevated setup costs ahead of mass production.
- Escalating Capital Expenditures and Free Cash Flow Drag: Capital expenditure guidance raised to $60–$64 billion, combined with costly overseas fabrication expansion plans in Arizona and prospective Texas locations, increases execution risk and strains near-term free cash flow generation.
- Valuation Overhang and High Q3 Expectations: With shares trading near 52-week highs and current valuation models flagging a ~20% premium to intrinsic fair value, the stock faces heightened downside volatility if upcoming Q3 earnings or September revenue prints fail to beat high consensus targets.
- Geopolitical Exposure and Customer Concentration: Persistent geopolitical friction surrounding Taiwan alongside heavy revenue concentration among top hyperscaler and chip design clients leaves the firm vulnerable to regional supply disruptions or customer capex pullbacks.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.