


Royal Caribbean Cruises Ltd Stock (RCL) Moved Up by 5.80% on Sep 29: What Signal Does It Send?



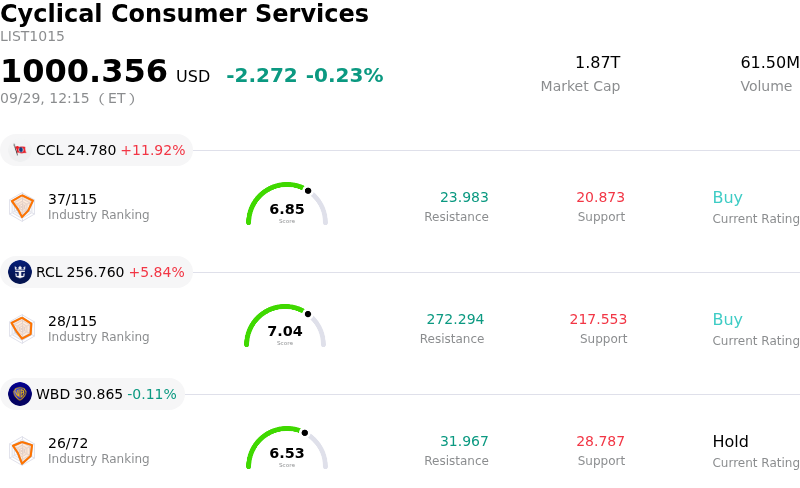
Royal Caribbean Cruises Ltd (RCL) moved up by 5.80%. The Cyclical Consumer Services sector is down by 0.23%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Carnival Corp (CCL) up 11.92%; Royal Caribbean Cruises Ltd (RCL) up 5.84%; Warner Bros Discovery Inc (WBD) down 0.11%.
What is driving Royal Caribbean Cruises Ltd (RCL)’s stock price up today?
Royal Caribbean Group experienced notable upward momentum, driven primarily by strong sector-wide read-through from peer earnings. Key rival Carnival Corporation released quarterly financial results that exceeded Wall Street estimates for both revenue and earnings per share, while highlighting record booking volumes for future travel. This robust performance served as a powerful catalyst across the entire cruise and leisure industry, reassuring market participants that underlying consumer demand for ocean voyages remains resilient despite broader macroeconomic pressures and recent fluctuations in marine fuel costs.
The positive momentum was further amplified by a series of bullish rating upgrades from major Wall Street institutions, including Bank of America and Deutsche Bank. Analysts pointed out that the stock's pullback over the preceding weeks had created a compelling entry point for a premium operator. The sell-off had compressed Royal Caribbean's valuation multiples well below historical averages, prompting research firms to reiterate high conviction in the company's best-in-class operating margins, balance sheet quality, and strong return on invested capital.
In addition to short-term earnings sentiment and valuation relief, institutional investors are increasingly focusing on the long-term growth opportunities embedded in Royal Caribbean's strategic initiatives. The market has reacted favorably to the company's recent expansion plans, including a major joint venture investment in luxury land-based resorts aimed at broadening its hospitality reach and expanding cash flow channels. Coupled with resilient customer spending and disciplined capacity management, these structural drivers reinforce investor confidence in Royal Caribbean's capacity to deliver sustained earnings growth.
Technical Analysis of Royal Caribbean Cruises Ltd (RCL)
Technically, Royal Caribbean Cruises Ltd (RCL) shows a MACD (12,26,9) value of 2.974, indicating a neutral signal. The RSI at 48.082 suggests neutral condition and the Williams %R at 14.706 suggests overbought condition. Please monitor closely.
Media Coverage of Royal Caribbean Cruises Ltd (RCL)
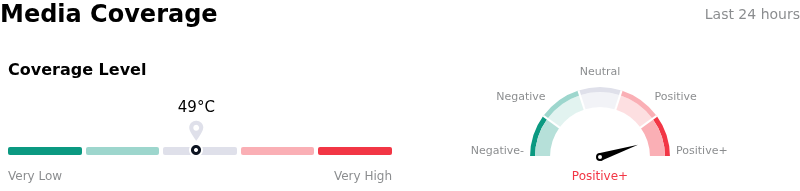
In terms of media coverage, Royal Caribbean Cruises Ltd (RCL) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Royal Caribbean Cruises Ltd (RCL)
Royal Caribbean Cruises Ltd (RCL) is in the Cyclical Consumer Services industry. Its latest annual revenue is $17.93B, ranking 7 in the industry. The net profit is $4.27B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $345.64, a high of $425.00, and a low of $259.71.
More details about Royal Caribbean Cruises Ltd (RCL)
Company Specific Risks:
- M&A Debt Leverage & Integration Risk: Following an SEC Form 8-K filing announcing a $3.0 billion cash acquisition for a 50% stake in Sandals Resorts, market volatility spiked over concerns regarding 100% debt-financed expansion, potential land-based integration delays, and added balance sheet strain.
- Operating Margin Compression & Fuel Inflation: Despite high top-line revenue growth, operating margins have faced downward pressure due to rising payroll costs, increased port expenses, and volatile unhedged fuel exposure across fleet operations.
- Acute Working Capital Deficit & Debt Servicing: The company maintains elevated leverage with a debt-to-equity ratio near 2.3 and a current ratio under 0.20, exposing the business to severe short-term liquidity constraints and high debt-servicing requirements.
- Regional Capacity Expansion & Pricing Yield Risks: Analyst commentary indicates accelerated high-single-digit passenger capacity growth coming online across Caribbean itineraries, which threatens to erode premium net ticket yields and force promotional discounting.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.