


KLA Corp Stock (KLAC) Moved Up by 3.10% on Sep 18: Facts Behind the Movement



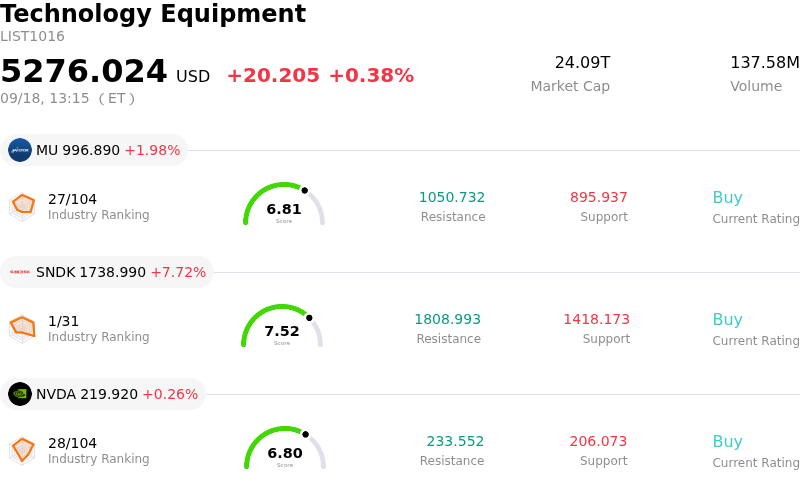
KLA Corp (KLAC) moved up by 3.10%. The Technology Equipment sector is up by 0.38%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) up 1.98%; SanDisk Corporation (SNDK) up 7.72%; NVIDIA Corp (NVDA) up 0.27%.
What is driving KLA Corp (KLAC)’s stock price up today?
KLA Corporation advanced notably during the trading session, reflecting strong demand across the semiconductor equipment complex as institutional investors rotated into key tools suppliers. The primary catalyst driving sentiment was major sell-side research highlighting the company as a top pick within the chip capital equipment space. Wall Street analysts pointed to KLA's superior risk-reward profile following recent sector consolidation, emphasizing its pivotal role in process control and yield management as global chipmakers ramp up next-generation fabrication facilities.
The broader semiconductor equipment subsector benefited from expanding long-term capital spending projections driven by artificial intelligence infrastructure buildouts. Projections for global wafer fabrication equipment spending indicate an accelerating multi-year upcycle, bolstered by hyperscaler investments, custom silicon deployment, and constrained tool availability. Within this environment, investors are increasingly differentiating process control leaders from general semiconductor equities, recognizing that complex node transitions and high-bandwidth memory production require KLA's specialized metrology and inspection tools to maintain yields.
Underlying institutional positioning and fundamental performance provided additional support for the positive price action. Disclosures showing major institutional stake increases, coupled with KLA's strong quarterly revenue growth and sustained capital returns through dividends, reinforced investor confidence. Although intraday volatility was elevated due to broader market gyrations and recent routine insider sales executed under pre-arranged trading plans, the prevailing narrative surrounding AI-driven fab expansion and strong long-term earning visibility prevailed, driving the stock higher by the close.
Technical Analysis of KLA Corp (KLAC)
Technically, KLA Corp (KLAC) shows a MACD (12,26,9) value of 0.256, indicating a neutral signal. The RSI at 43.735 suggests neutral condition and the Williams %R at 66.218 suggests sell condition. Please monitor closely.
Media Coverage of KLA Corp (KLAC)
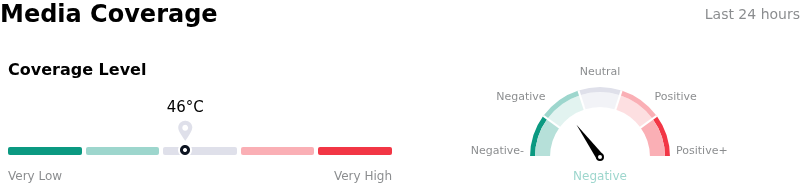
In terms of media coverage, KLA Corp (KLAC) shows a coverage score of 46, indicating a moderate level of media attention. The overall market sentiment index is currently in bearish zone.
Fundamental Analysis of KLA Corp (KLAC)
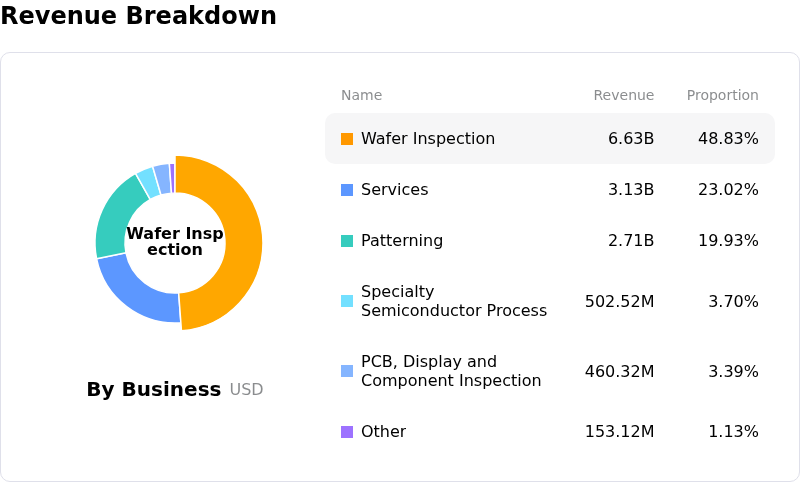
KLA Corp (KLAC) is in the Technology Equipment industry. Its latest annual revenue is $13.58B, ranking 15 in the industry. The net profit is $4.83B, ranking 11 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $229.27, a high of $325.00, and a low of $138.80.
More details about KLA Corp (KLAC)
Company Specific Risks:
- Executive Insider Selling Overhang: SEC Form 4 filings disclosed that President and CEO Richard P. Wallace sold 72,019 shares of common stock worth $12.38 million on September 15, 2026, trimming his direct equity stake by over 9% and amplifying market concerns over top-level profit-taking.
- Severe Valuation Premium and AI Capex Vulnerability: Intraday volatility and sector-wide selloffs highlight market sensitivity to AI infrastructure buildouts, with analysts warning that KLAC's current valuation—trading around 45x P/E compared to its 5-year median of 28x—leaves the equity highly exposed to multiple compression and derating.
- Margin Compression and Input Cost Headwinds: Recent forward-looking commentary underscores execution risks stemming from elevated memory-component costs, rising trade tariffs, and ongoing memory pricing pressures projected to strain gross margins through 2027.
- Geopolitical Trade Policy and Revenue Concentration: Institutional analysis emphasizes KLAC's ongoing reliance on mainland China for 25% to 35% of revenue, creating persistent downside exposure to escalating U.S. semiconductor export restrictions and capital expenditure delays by key foundry clients.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles





Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.