


Qualcomm Inc Stock (QCOM) Opened Up by 4.71% on Sep 15: What Signal Does It Send?



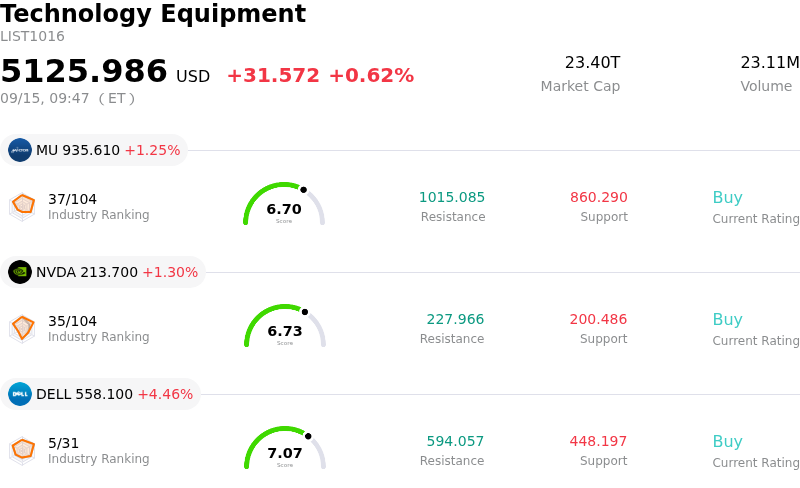
Qualcomm Inc (QCOM) opened up by 4.71%. The Technology Equipment sector is up by 0.62%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) up 1.15%; NVIDIA Corp (NVDA) up 1.27%; Dell Technologies Inc (DELL) up 4.67%.
What is driving Qualcomm Inc (QCOM)’s stock price up today?
Qualcomm experienced strong upward buying interest today as institutional investors continued to digest the company's aggressive expansion into data center artificial intelligence hardware. The market's enthusiasm is heavily anchored by its multi-generational partnership with Amazon Web Services to co-develop customized AI inference processors and high-bandwidth optical connectivity solutions. This milestone marks a strategic transition for Qualcomm beyond its core mobile communications footprint, establishing a viable second growth engine in cloud infrastructure. By securing a tier-one hyperscaler commitment, Qualcomm has demonstrated its ability to capture enterprise infrastructure spending, triggering positive earnings revisions and driving multi-session institutional accumulation.
Market sentiment is further fortified by mounting anticipation ahead of the company's annual Snapdragon Summit later this month. Investor expectations are elevated regarding upcoming flagship mobile platform unveilings, which feature significant architectural upgrades to its Hexagon Neural Processing Unit tailored for context-aware, on-device AI agents. As original equipment manufacturers accelerate the rollout of AI-capable smartphones, personal computers, and automotive cockpits, Qualcomm's leadership in power-efficient edge compute positions it to capture higher content value per unit. Furthermore, recent contract pricing adjustments across its premium hardware categories are being viewed by analysts as a key driver for margin expansion heading into the next fiscal cycle.
From a tactical portfolio perspective, Qualcomm is benefiting from rotational capital flows into semiconductor equities that combine high-growth AI exposure with reasonable valuation metrics. While concentration risks tied to handset market cycles previously restricted valuation multiples, the tangible expansion into cloud inference and edge AI infrastructure is shifting market perception. With broader semiconductor sentiment supported by robust enterprise tech spending, Qualcomm's dual-track momentum in both edge and cloud compute continues to attract sustained institutional buying.
Technical Analysis of Qualcomm Inc (QCOM)
Technically, Qualcomm Inc (QCOM) shows a MACD (12,26,9) value of 5.278, indicating a buy signal. The RSI at 70.819 suggests buy condition and the Williams %R at 0.842 suggests overbought condition. Please monitor closely.
Media Coverage of Qualcomm Inc (QCOM)
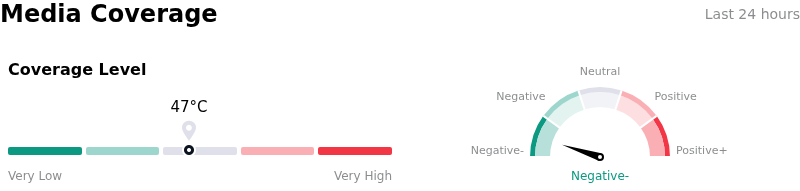
In terms of media coverage, Qualcomm Inc (QCOM) shows a coverage score of 47, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bearish zone.
Fundamental Analysis of Qualcomm Inc (QCOM)
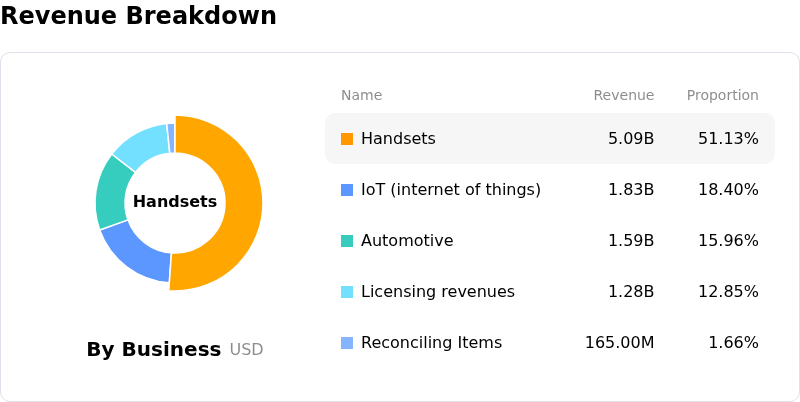
Qualcomm Inc (QCOM) is in the Technology Equipment industry. Its latest annual revenue is $44.28B, ranking 6 in the industry. The net profit is $5.54B, ranking 9 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $194.40, a high of $400.00, and a low of $100.00.
More details about Qualcomm Inc (QCOM)
Company Specific Risks:
- Escalating Supply Chain Costs and Pricing Resistance: Qualcomm was recently forced to announce double-digit chip price increases to offset soaring foundry and component expenses, exposing the company to customer pushback and order cancellations as AI infrastructure demand severely constrains manufacturing capacity.
- Protracted Weakness in Core Smartphone Market: Analyst reports caution that management does not expect a broad recovery in the smartphone sector, with soft China Android demand and customer vertical integration (such as Apple's modem development) continuing to pressure revenue through 2027.
- Uncertain AI Monetization and Valuation Exposure: Despite news surrounding its Amazon AI silicon collaboration, the deal relies on warrant-vesting performance milestones rather than guaranteed upfront revenue, leaving Qualcomm's elevated valuation vulnerable as material AI-driven earnings inflections are not expected until FY2028.
- Semiconductor Tariff Policy Overhang: Pending U.S. tariff proposals targeting chips and AI-enabled hardware threaten to inflate cost structures across Qualcomm's ecosystem, creating headwind risks for its Snapdragon X AI PC rollouts and international expansion.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.